

Airlines, airports, hotels and cities. I explain the strategy and infrastructure behind how we travel. San Francisco.
- Tweets12.2K
- Following2.1K
- Followers41.4K
- Likes24.8K


ALT Ranking of ten airline mergers since 1996. Best: Delta-Northwest, market value up 531% since 2008; IAG up 185%; Lufthansa-Swiss, one year of Swiss profit tops its price; United-Continental up 307%; America West-US Airways, margin up 10 points. Worst: American-TWA, St. Louis flights cut 50%; American-US Airways down 79% since 2014; Air France-KLM down 27%; Alaska-Virgin America, LA seats down 25% and SFO down 22%; Kingfisher-Air Deccan, stopped flying within 5 years.

ALT US map titled "If your airline gets bought, your hub is in trouble." Circles at the hubs of Northwest, Continental, US Airways, and Virgin America compare seats the year before each merger with now. Shrank: Minneapolis -13%, Detroit -16%, Memphis -86%, Cleveland -59%, Philadelphia -9%, San Francisco -22%, Los Angeles -25%. Grew: Newark +24%, Charlotte +25%, Reagan National +14%. Flat: Houston +2%, Phoenix +1%. Off the map: Tokyo Narita closed, Guam -14%, Honolulu -3%, Maui -12%.

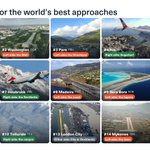
ALT Photo grid of 15 favorite airport approaches with which side of the plane to sit on: San Francisco either side, Washington left, Paro left, Rio right, St. Barts either, Queenstown right, Innsbruck right, Madeira left, Bora Bora left, Jackson Hole right, Nice left, Telluride right, London City either, Mykonos left, St. Maarten either.


ALT Bar chart from an Expedia Group survey by YouGov of 5,700+ adults in the US, UK, and India, March 2026: 66% wouldn't trust AI to buy or book anything for them, and 53% are comfortable letting AI suggest options.

ALT Bar chart from MakeMyTrip's results for July to September 2026: compared with customers who don't use its AI assistant Myra (1.0x), customers who use Myra completed 1.7 times as many bookings, and Myra users in smaller Tier II and Tier III Indian cities completed 2.1 times as many. Myra helped complete more than 3,000 bookings a day from about 90,000 daily conversations.

ALT Future-moves graphic: Breeze reports 59 A220s in its fleet and 90 firm A220 orders; these are separate measures, not a delivery subtraction. Three proposed moves are deeper schedules in established markets, nearby international flying, and more premium seats. Distinct photos show a Breeze A220 at Vero Beach, Tampa–Nassau inaugural flight tags, and Breeze's A220 first-class cabin; they illustrate the moves but do not prove future frequency or seating changes. The hurdle is a $118 million full-year net loss in 2025; future profitability is not assured.

ALT Breeze operating revenue and operating loss, 2023 to 2025, on a common dollar scale above and below zero. Square-ended teal revenue bars rise from $385 million to $684 million to $984 million. Purple loss bars narrow from $157 million to $63 million to $16 million. A top-left swatch key names both series. Padded callouts beneath each year show operating margins of negative 40.8%, negative 9.2%, and negative 1.6%. Source: U.S. DOT Form 41.

ALT Two-bar T-100 proxy comparing scheduled-departure shortfalls in 2025. Breeze's shortfall averages 762 route miles and 2.15% of scheduled departures, versus 812 miles and 2.28% at other scheduled carriers.

ALT One enlarged U.S. map of all 35 scheduled May 2026 Breeze routes from RDU. Every spoke has an airport-code label near its geographic endpoint; no distant right-side label rail remains. All route lines are purple. Thicker lines identify routes to Breeze's other currently listed bases; thinner lines identify other spokes.

ALT Full-width map of Breeze's 13 currently listed bases, colored by first documented opening year. A bottom-left key counts four 2021 bases, two 2022, one 2023, three 2024, one 2025, and two 2026. Florida has a geographic detail inset. No independently documented closed base was identified, so this is not a complete historical base chronology.

ALT Bar chart of Breeze's departure-weighted scheduled stage length: 631 miles in 2021, rising to 924 in 2024, then falling to 784 by May 2026. The share of departures on routes at least 1,500 miles peaks at 17.4% and falls to 9.7%.

ALT Breeze's 34 July 2025 routes over 1,500 miles. Routes are colored by western gateway, including green SFO. Three routes absent from the current schedule are red dotted lines and their airport labels are red.

ALT Five-step Breeze network timeline, with distinct purple, blue, magenta, ochre, and green era labels and five equal-sized photos: the 2021 inaugural E195 at Tampa, a 2022 A220 at Tampa, a 2024 A220 at Orlando, a 2025 A220 at Las Vegas, and a Tampa celebration of the 2026 Nassau launch. The 2025 panel includes EWR, IAD, and SLC, larger airports present in the retained July 2025 schedule snapshot but not earlier retained snapshots; their opening dates are not asserted. Boxes show selected destinations, not a complete route list.

ALT Three-panel Breeze business case, each with an idea header, visual description, and large takeaway. Breeze carried 43 passengers per day each way per carrier-route versus 343 at network mainline airlines, or 87% fewer. Its 137-seat A220 has a Breeze-attributed 20–25% lower trip-cost claim versus an A321. For BDL–CVG, the nonstop averages 2h03. Five selected paths via PHL, IAD, DTW, CLT, and ORD add a modeled 2h23, 2h25, 2h19, 2h46, and 3h29 respectively, including an illustrative 1h30 connection. The nonstop is 57% less modeled trip time than their unweighted average. Paths are not verified bookable itineraries.