

AI search & Data driven stock discovery platform. No opinions, Only FACTS backed by Data, Dis : Not SEBI registered, tweets ≠ buy/sell recommendation.
Bengaluru
Joined April 2024
- Tweets4.2K
- Following124
- Followers27.1K
- Likes2.6K




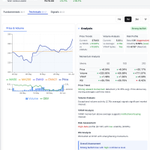
🧵 SOBHA's 93% profit surge in FY25 validates 3 strategic bets that could redefine India's realty sector.
Here's why this isn't just another quarterly beat - it's a blueprint for the next decade
Three strategic bets validated with hard numbers. Lets dive in 👉
screenshots from alpha.8sapience.ai/

Pipeline strength:
- ₹18.36B Q4 sales (+32% QoQ), ₹62.77B FY26 pipeline, 2-3 new city entries planned.
- Strong momentum as shown by recent 1 month - volume growth
- India's structural realty growth + SOBHA's execution = alpha potential.

Disclaimer : Do your own due diligence. Not a buy/sell/hold recommendation.
Use Smart Quant Analyzer - alpha.8sapience.ai/
If you like this and need similar analysis for any other companies - just comment/dm.
Like/Repost if it helps you in some way
What is meant by recent announcement by Dr. Reddy’s to Co-Develop Biosimilar Candidate for global markets...
source: nsearchives.nseindia.com/cor…
Deal Structure & Financials
Partnership: Dr. Reddy's + Alvotech for AVT03 (denosumab biosimilar)
Investment: ₹560 crores ($67mn) - ₹317 crores upfront + ₹243 crores milestones
Revenue Share: Sales-based payments to Alvotech
Rights: Exclusive US + Semi-exclusive Europe/UK markets
Market Opportunity
TAM: $3.7bn (FY25) → $5.59bn (FY29) at 13% CAGR
Reference Product: Prolia/Xgeva ($5.3bn revenue in 2021)
Indication: Osteoporosis (postmenopausal women) + cancer bone complications
Strategic Rationale
- Portfolio Upgrade: Shift from low-margin generics to high-value biosimilars US Market Entry: Exclusive access to world's largest pharma market
- De-risked Model: Alvotech handles R&D/manufacturing; DRL leverages existing commercial infrastructure
Recent Developments
- Regulatory: FDA BLA accepted, EMA application filed
- Clinical: Positive PK study results completed
- Timeline: Commercial launch expected FY26-27
Financial Impact
Revenue Potential:
- ₹2,000-3,000 crores annually post-launch
- Margin Accretion: Biosimilars command 30-40% higher margins vs generics
- Payback: 3-4 years on ₹560 crore investment
Key Risks
- Regulatory approval delays
- Pricing pressure from competition
- Market penetration challenges
Valuation & Recommendation
- Current biosimilar portfolio contributes <10% to revenues.
- Successful denosumab launch could add 15-20% to topline by FY28.
screenshot from - alpha.8sapience.ai/
Disclaimer: Educational, DYOR, Consult Advisor


7/7 🚀 Bottom Line: Nuvama = The only Indian stock giving you:
✅ Wealth management (sticky revenues)
✅ Asset services (institutional scale)
✅ International expansion (NRI wealth)
✅ AI advantage (cost efficiency)
Key catalyst: Singapore operations FY26
⚠️ Educational content only. Not investment advice. DYOR & consult advisors.
Disclaimer : Do your own due diligence. Not a buy/sell/hold recommendation.
Use Smart Quant Analyzer - alpha.8sapience.ai/
If you like this and need similar analysis for any other companies - just comment/dm.
Like/Repost if it helps you in some way
Suven Life Sciences surged 140.66% over the past year despite widening losses reaching ₹439.45 crore in Q4 FY25
And market capitalization of ₹5,109 crore at 47.4x book value contrasts sharply with a -84.6% ROE
So, why stock is soaring new heights? Let's try to decode the Biotech Valuation Paradox...
screenshots from : alpha.8sapience.ai/


Disclaimer : Do your own due diligence. Not a buy/sell/hold recommendation.
Use Smart Quant Analyzer - alpha.8sapience.ai/
If you like this and need similar analysis for any other companies - just comment/dm.
Like/Repost if it helps you in some way