


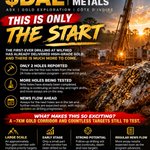


$DAL: GOLD DISCOVERY JUST GOT BIGGER. IS THE MARKET UNDERVALUING THE POTENTIAL?
Dalaroo’s latest results from Bondoukou in Côte d’Ivoire are looking increasingly interesting.
New gold intercepts 1.25km from the original high-grade discovery!
Key highlights:
• 13m @ 2.67g/t gold, including 6m @ 4.19g/t
• 60m @ 0.85g/t gold
• 1m @ 16.20g/t gold
• Previous discovery: 18m @ 7.31g/t gold
• Significant gold intercepts in 8 of 12 holes reported
What excites me most is the potential scale.
Gold mineralisation has now been identified at widely separated locations, strengthening the case for a potentially substantial gold system. Continuity remains unproven.
Next major catalysts:
• Expanded 1,750m diamond drilling expected to commence within seven days
• Additional RC assays pending
• 35.1km IP survey planned
• Further testing across the 7km gold-anomalous corridor
This is moving beyond a single high-grade discovery into a potentially much larger exploration opportunity.
The next drilling results could be crucial for $DAL’s valuation.
#DAL #ASX #Gold #GoldExploration #MiningStocks #CotedIvoire
DYOR. Not financial advice. Mineralisation continuity and economic viability remain unproven.
$MTM $MTMCF | Is Metallium Approaching Its Biggest Commercial Breakthrough Yet?
My view: Metallium’s latest quarterly report shows real progress.
90%+ preliminary metal recoveries. A$50.7M cash. First US$500K technology revenue received.
Texas is advancing, with PCB product sales targeted for H1 2027.
The next catalyst I’m watching is the 8,000-tonne processing module Implementation Plan.
Can $MTM turn promising technology into profitable commercial operations?
Source: Metallium ASX Quarterly Report, 30 October 2026.
Personal opinion only. Not financial advice. Commercialisation carries risks.
#MTM #MTMCF #ASX #RareEarths #CriticalMinerals #Investing #GrowthStocks
Another positive development for $AT1.
Atomo has partnered with Innovation Scientific to develop a 4th-generation HIV rapid test, targeting commercial launch within 24 months.
I like what I’m seeing here. Another product added to the pipeline, expanding global opportunities alongside Active Syphilis.
$AT1 is building for the future. One to watch.
Disclaimer: Personal opinion only. Not financial advice. DYOR.
$DBO | ANOTHER CRITICAL MINERAL ADDED TO THE STORY!
Diablo has now confirmed HIGH-GRADE TUNGSTEN at its Horn Project in Utah, USA.
CUPRIC RESULTS:
→ 0.37% WO3 tungsten
→ 0.22% WO3 tungsten
→ 0.17% WO3 + 2.82g/t Au
→ 12.5% Cu + 3.29g/t Au + 398g/t Ag
→ 4.5m @ 1.26% Cu + 0.46g/t Au
And here’s what makes this interesting.
TUNGSTEN IS A U.S. CRITICAL MINERAL.
America remains heavily reliant on foreign supply, making domestic discoveries strategically important.
Two historical 1940s adits provide underground access, with mapping and sampling underway.
MAIDEN HORN DRILLING TARGETED Q1 2027.
Silver. Gold. Copper. Antimony. NOW TUNGSTEN.
What started as a high-grade silver exploration story is developing into a much broader U.S. critical minerals opportunity.
These are early-stage surface results, but the potential is becoming increasingly interesting.
$DBO is one I’ll be watching very closely as drilling approaches.
#DBO #Tungsten #Silver #Copper #CriticalMinerals #ASX
DYOR. Speculative explorer. NFA.
$MTM | THIS COULD BE A GAME CHANGER!
Metallium has signed an MOU with TRAXYS - a global commodities giant turning over US$10 BILLION+ annually!
Why I’m bullish:
Global feedstock sourcing
Potential offtake agreements
Trade financing & strategic investment opportunities
Gallium, germanium, rare earths & defence metals
Traxys is a named supplier to the US-backed Project Vault initiative
Next major catalyst: Definitive agreements targeted by 31 December 2026.
For me, the bigger picture is becoming clearer.
TECHNOLOGY + FEEDSTOCK + BUYERS + FINANCING = POTENTIAL COMMERCIAL SCALE.
The MOU is non-binding. No financing or offtake is guaranteed, and MTM has no Project Vault participation secured.
But if this converts into binding commercial deals, I believe the market could start valuing $MTM very differently.
My speculative bull-case target remains $1.50–$2.00, conditional on successful execution - not a guaranteed outcome.
The next two months could be very interesting!
$MTM $MTMCF
#CriticalMinerals #RareEarths #Gallium #ASX
Personal opinion only. Not financial advice. DYOR.
AlphaMatrixX retweeted

$MTM’s US subsidiary signs an MOU with Traxys, a global commodities trader with US$10bn+ annual turnover.
Targeting feedstock, offtake and financing solutions for US critical metals processing.
investorhub.metalliuminc.com…
🤖 Made with AI

$X2M JUST ADDED ANOTHER 10MW AI DATA CENTRE PROJECT
X2M has signed an agreement for a 10MW AI-enabled data centre site in regional Queensland.
The numbers are getting serious:
$250M estimated project cost
10MW capacity
Existing 2.5MW grid connection
Development approval already secured
Additional 7.5MW planned via behind-the-meter generation
20MW now under agreement across two projects
More than $500M aggregate estimated project cost
200MW+ prospective pipeline still in play
X2M has also secured binding exclusivity over the site and power capacity for 60 days, with binding long-form agreements targeted within 90 days.
The story is shifting from pipeline building to pipeline conversion.
If X2M keeps converting its 200MW+ pipeline, the scale of this data centre business could change very quickly.
$X2M #X2M #AI #DataCentres #ASX
$CRI at 2.3c is starting to look seriously mispriced on paper.
Critica’s latest investor presentation now puts the story in one line:
Two 100%-owned Australian projects.
Two Scoping Studies delivered.
~A$3.0 BILLION combined after-tax NPV8.
Yet at the 20 October close, $CRI was valued at just A$69.7M.
JUPITER
A$2.0B after-tax NPV
48.4% after-tax IRR
~2 year payback
A$556M pre-production capex
1.7Bt rare earth Resource
Initial mine plan uses only ~6% of the Resource.
MT LINDSAY
A$1.0B after-tax NPV
55.6% after-tax IRR
~1.9 year payback
A$245M pre-production capex
Targeting first production by end-2029.
Rare earths. Yttrium. Gallium. Tungsten. Tin.
One company. Two development pathways. Multiple potential catalysts.
The question for the market now isn’t whether $CRI has scale.
It’s whether a ~A$70M company can successfully convert those Scoping Study numbers into funded projects.
That’s where the re-rate could come from.
Using the latest $CRI presentation and a 2.3c starting price, I’d frame the long-term upside as a scenario range rather than a single target.
CRI has about 3.03bn shares on issue, so at 2.3c the market cap is roughly A$70m. Against that, the two Scoping Studies show roughly A$3.0bn combined after-tax NPV8: about A$1.0bn for Mt Lindsay and A$2.0bn for Jupiter.
My rough long-term scenarios would be:
Base case: 7–12c - Mt Lindsay and Jupiter continue through feasibility, resource confidence improves, and CRI secures credible offtake/strategic partners. At 10c, CRI would be worth about A$303m on today’s share count.
Bull case: 15–25c - one project becomes substantially de-risked and financed while the second retains meaningful development value. At 20c, today’s share count implies about A$606m market cap.
Very bullish case: 30c+ -both projects advance successfully, strategic funding limits dilution, project economics broadly survive feasibility, and critical-mineral pricing remains supportive. At 30c, the current share count implies about A$909m.
The easiest valuation shortcut is to compare market cap with the approximately A$3bn combined Scoping Study NPV. If CRI eventually traded at 10% of combined NPV, that is around 9.9c per share on today’s share count. At 20%, it is around 19.8c; at 30%, around 29.7c.
But dilution is the biggest reason not to treat those as literal targets. Mt Lindsay requires roughly A$245m pre-production capital and Jupiter roughly A$556m, so CRI will need substantial debt, strategic investment, offtake funding, equity, or some combination.
So from 2.3c, my personal valuation framework would put 7–12c as a reasonable long-term base-case zone, with 15–25c becoming realistic if financing and feasibility materially de-risk the projects. 30c+ is possible, but it requires a lot to go right.
Not financial advice. Always DYOR.
#ASX #CRI #RareEarths #CriticalMinerals #Tungsten #Tin
$CRI at 2.3c and the Jupiter Scoping Study numbers are hard to ignore.
A$2.0 BILLION after-tax NPV
48.4% after-tax IRR
~2 year after-tax payback
A$12.3B modelled LOM revenue
A$446M average annual EBITDA
A$556M pre-production capex
8Mtpa operation
~14 year processing life
But this could be the most important number:
The current Production Target uses only ~6% of Jupiter’s total 1.7Bt Resource.
That leaves ~94% outside the current mine plan for potential future conversion, expansion or mine-life extension.
And the Base Case gives ZERO value to iron, gallium or scandium.
Jupiter also contains all four key magnet rare earths — Nd, Pr, Dy and Tb — representing ~23% of TREO.
At 2.3c, $CRI now has a Scoping Study putting serious numbers behind Jupiter.
The next phase is PFS, further metallurgy, resource conversion, offtake discussions, strategic partnerships and funding.
This story is no longer just about the size of the resource.
Now there are economics attached to it.
Not financial advice. Always DYOR.
#ASX #CRI #RareEarths #CriticalMinerals
$MTM | Interesting signal for long-term shareholders!
Metallium has issued 2.5M employee performance rights linked to share price VWAP targets:
🎯 $1.00 — 500K rights
🎯 $1.25 — 750K rights
🎯 $1.50 — 1.25M rights
Expiry: October 2031.
These aren’t price forecasts, but they create incentives aligned with significant long-term shareholder upside.
With FJH commercialisation progressing, it’s encouraging to see ambitious performance targets built into employee incentives.
Long-term value creation is the focus. 📈
#MTM #ASX #CriticalMinerals #Investing
$MTM SMASHED ON THE MARKET, BUT IS THE TECHNOLOGY STORY GETTING STRONGER?
Metallium shareholders have endured a brutal sell-off, but the latest announcement raises an interesting question.
Is the market overlooking the progress being made?
ECT has confirmed the successful production of MXene using $MTM’s Flash Joule Heating technology, with independent XRD analysis supporting the formation of chlorine-terminated MXene.
This is significant.
MXenes have potential applications in defence, electromagnetic shielding, advanced coatings and next-generation electronics.
And the bigger picture?
$MTM is no longer just targeting critical metals recovery. Its technology could potentially generate revenue through engineering services, licensing and advanced materials processing.
What comes next?
Further optimisation and repeatable MXene production
Independent testing against defence specifications
Samples for prospective defence customers
Customer qualification and potential commercial opportunities
The technology is progressing, but commercial-scale economics and repeatable production still need to be proven.
The share price has been smashed. The commercial opportunity hasn’t disappeared.
Could this be the disconnect investors look back on?
The next few announcements could be crucial.
$MTM #ASX #CriticalMinerals #MXene #Defence #AdvancedMaterials #SmallCaps #Investing
Disclaimer: Not financial advice. Speculative investment. Technical success does not guarantee commercial success or share price recovery. DYOR.
$CRI may have just moved Jupiter into a completely different category.
Critica has delivered Jupiter’s first Indicated Mineral Resource:
160Mt @ 1,700ppm TREO
That sits inside a total Jupiter Resource of:
1.7 BILLION tonnes @ 1,700ppm TREO
And here’s the part the market may focus on next:
Only around 10% of the Jupiter Resource area has been infill drilled at the tighter spacing used to support Indicated classification.
The rest is still largely Inferred.
That means this update isn’t about discovering Jupiter.
It’s about proving up what is already there.
The new Indicated Resource also carries a strong magnet rare earth component, with Nd, Pr, Dy and Tb making up around 25% of TREO.
So the setup is becoming clearer:
Massive scale.
First Indicated tonnes.
Higher confidence.
Magnet REO exposure.
Only a fraction of the resource area infill drilled.
And the Jupiter Scoping Study is still to come.
That next study could be the real valuation event.
$CRI is now moving from “how big is Jupiter?” to “what could Jupiter actually be worth?”
That’s a very different question.
Not financial advice. Always DYOR.
#ASX #CRI #RareEarths #CriticalMinerals #Mining
$DAL | THE STORY JUST GOT MORE INTERESTING!
Last week, Dalaroo delivered a high-grade gold discovery:
18m @ 7.31g/t Au
Today, another potentially significant development.
34m of alteration and quartz veining identified 1.25KM from the original discovery!
The exciting part for me is that the new hole shows geological similarities to the original discovery hole.
But remember, only TWO holes have reported gold assays so far.
And look what’s coming:
• 10 RC holes now completed
• BDRC010C assays expected before the end of October
• 7 more holes awaiting assays from early November
• Diamond drilling planned for October
• Further testing across a ~7KM gold corridor
For me, this is where things could get very interesting.
If upcoming assays confirm gold mineralisation 1.25km away, how much bigger could this discovery become?
The first two holes got everyone’s attention.
The next batch could help determine the scale of the opportunity.
What do you think? Is $DAL only getting started?
#DAL #ASX #Gold #GoldDiscovery #MiningStocks #SmallCaps #Exploration
Disclaimer: This is my personal opinion only. DYOR.
$DAL | ONLY 2 HOLES HAVE REPORTED. READ THAT AGAIN.
The first TWO holes ever drilled at Wilfred BOTH hit gold.
18m @ 7.31g/t Au
Including 12m @ 8.66g/t Au
Peak 1m @ 15.90g/t Au
23m @ 2.14g/t Au FROM SURFACE
Including 12m @ 3.35g/t Au
And this could be just the beginning.
Only 2 holes have assays reported from the initial 24-hole orientation program.
9 holes already completed.
BDRC010 underway.
BDRC003 + BDRC004 already at the lab.
BDRC005 samples being dispatched.
Drilling running DAY + NIGHT.
All across an approximately 7KM GOLD CORRIDOR.
The first 2 holes got the market’s attention.
Now the real question:
What happens if the NEXT holes start confirming GRADE + CONTINUITY + SCALE?
More holes. More assays. More news flow.
This story could only be getting started.
Where do you think $DAL goes if the next holes deliver similar results?
#DAL #ASX #Gold #GoldDiscovery #GoldStocks #MiningStocks #SmallCaps
Disclaimer: l Personal opinion only, not financial advice. Information sourced from Dalaroo Metals’ ASX announcement dated 7 October 2026. DYOR.
🤖 Made with AI

$DAL | THIS IS HOW A DISCOVERY STORY STARTS
Dalaroo has just hit high-grade gold in the FIRST two holes ever drilled at Wilfred.
18m @ 7.31g/t Au from 63m
Including 12m @ 8.66g/t Au
Peak 1m @ 15.90g/t Au
Plus 16m @ 1.46g/t Au from 113m
And the first hole?
23m @ 2.14g/t Au FROM SURFACE
Including 12m @ 3.35g/t Au
The standout 18m @ 7.31g/t delivers approximately 132 gram-metres.
But this is what has my attention…
These are results from just TWO holes along an approximately 7KM GOLD CORRIDOR.
Nine holes are already completed. Drilling is running day and night. The maiden campaign is targeting approximately 12,000m across Wilfred, Mag and Ali.
And the next catalyst is already coming.
BDRC003 + BDRC004 assays expected EARLY NOVEMBER.
Now it comes down to three things:
GRADE. CONTINUITY. SCALE.
If the next holes start repeating these widths and grades, $DAL could become a completely different story.
The first two holes have delivered.
Now we find out how big this system really is.
#DAL #ASX #Gold #GoldDiscovery #GoldStocks #Mining #SmallCaps #CotedIvoire
Disclaimer: Personal opinion only, not financial advice. Exploration is speculative. True widths, geometry and continuity are not yet known and no Mineral Resource has been defined. Information sourced from Dalaroo Metals ASX announcement dated 7 October 2026. DYOR.

AlphaMatrixX retweeted
Thanks for the question. The June 2027 reference reflects the conservative assumption we have adopted around revenues from metal products, consistent with our most recent Quarterly Report. We need to be particularly conservative with forward timelines in formal documents such as the Annual Report.
Importantly, it does not mean we expect to wait until June 2027 to produce saleable metal products or potentially generate sales from them.
Our e-waste strategy is targeting recovery of a broad range of metals, with current products predominantly metal chlorides and other metal-bearing intermediates. Establishing reliable commercial sales across multiple products requires qualification with prospective offtakers, including assessment of composition, impurities, consistency and downstream processing suitability. This qualification process can take time, which is why we have taken a deliberately conservative approach to the H1 2027 timeframe. We will of course be working to achieve product sales earlier.
Separately, Metallium has already commenced generating revenue from its FJH platform through the ECT agreement.
We are also extremely excited by the evaluation work underway with Government and industry. This is leading us to assess some very interesting and potentially strategically important future feedstocks. While this work is currently being prioritised within our available testing capacity, successful outcomes could create significant opportunities for the Company and potentially accelerate our conservative commercialisation timelines.
Thank you both for your interest in the company.
$AT1 setting up for its next phase.
The 2026 AGM notice highlights continued focus on commercialising Atomo’s proprietary diagnostics, including Active Syphilis and Liver Function, while scaling operations to support increased demand for Pascal cassettes for Lumos’ FebriDx growth in the US.
With AT1 directly exposed to the growing FebriDx opportunity through cassette supply, the Lumos US rollout remains an important development to watch.
#AT1 #LDX #ASX #MedTech #Diagnostics #SmallCaps
DYOR. Not financial advice.
$EAU FY26 highlights ⚡️🇧🇴
• EAU Lithium acquisition completed
• A$5.0m placement completed
• A$3.76m cash at 30 June
• VULSORB® A-DLE technology access via Vulcan
• Pilot Plant 4 purchase progressing
• SEPCON + VULTEC engineering support
• Bolivian brine testing program advancing
FY27 focus: pilot plant acceptance, mobilisation to Bolivia, further process testing and commercial discussions.
#Lithium #Bolivia #DLE #ASX $EAU
$MTM $MTMCF - Another Major Step Toward Commercialisation
Metallium has successfully completed a 12-hour FJH chlorination campaign at its Texas Technology Campus - running 3 reactors simultaneously on high-value catalytic converter feedstock containing platinum, palladium and rhodium.
For me, the progression is what matters:
June - multi-reactor commissioning under inert conditions.
Now - multi-reactor processing under reactive chlorination conditions with real PGM-rich feedstock.
Next - optimisation, customer qualification, PCB module economics and ultimately commercial sales.
Add the proposed Nasdaq ADR uplisting and a new CFO coming onboard, and there are plenty of milestones ahead.
Test. Prove. Optimise. Qualify. Commercialise.
If FJH successfully scales commercially, how big could the opportunity become?
#MTM #MTMCF #MTLMY #ASX #CriticalMinerals #PGM #Recycling #RareEarths
Personal opinion only. Not financial advice. DYOR.