

Energy, critical minerals & global supply chains. Focus on strategic resources and macro trends. Covering Vaca Muerta and the Lithium Triangle.
Joined February 2026
- Tweets1.2K
- Following102
- Followers2.6K
- Likes1.4K
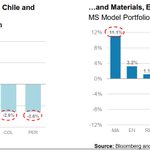



Morgan Stanley downgraded Brazil to Equal-weight, as a highly likely policy continuity scenario for the country increases pressure on fiscal risk.
> Brazil could face an increasingly challenging macroeconomic set-up: weaker currency, higher interest rates, and a slowing economy in need of an unlikely fiscal rebalancing.
> Despite the supportive global backdrop, MS expect sharp derisking to weigh on valuations.
> Why not UW Brazil?: Strong export story of Brazil, which together with the large banking sector, limit the downside of aggregate Brazilian earnings.
> Prefer to play the external side of the Brazilian
stock market, which has a lower cost of capital and its growth drivers are more linked to commodity prices than to domestic politics.
> Remain OW Chile and Argentina.
$EWZ $ARGT $ECH


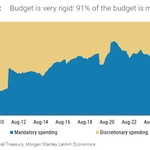
Brazil enters 2027 with rising debt, more than 91% of spending compulsory, limited room for further revenue-led adjustment, a spending rule increasingly weakened by exemptions, and a primary balance well below debt-stabilizing levels.
Measures announced during the election cycle are expected to add pressures, with a combined fiscal package implemented by the government since the beginning of the year exceeding BRL200bn (~2% of GDP).
#Brazil $EWZ

Austral Research retweeted
Lula threw nearly 2% of Brazil’s GDP into the election campaign between direct fiscal and quasi-fiscal measures.
Let that sink in.

Brazil enters 2027 with rising debt, more than 91% of spending compulsory, limited room for further revenue-led adjustment, a spending rule increasingly weakened by exemptions, and a primary balance well below debt-stabilizing levels.
Measures announced during the election cycle are expected to add pressures, with a combined fiscal package implemented by the government since the beginning of the year exceeding BRL200bn (~2% of GDP).
#Brazil $EWZ
Lula threw nearly 2% of Brazil’s GDP into the election campaign between direct fiscal and quasi-fiscal measures.
Let that sink in.
Brazil enters 2027 with rising debt, more than 91% of spending compulsory, limited room for further revenue-led adjustment, a spending rule increasingly weakened by exemptions, and a primary balance well below debt-stabilizing levels.
Measures announced during the election cycle are expected to add pressures, with a combined fiscal package implemented by the government since the beginning of the year exceeding BRL200bn (~2% of GDP).
#Brazil $EWZ
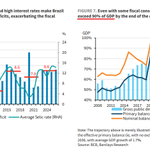
Lula will end his 3rd term with public finances in worse shape than he found them, with an average fiscal deficit of 8.6% (vs. prev 7%) of GDP over his term, debt on track to exceed 90% of GDP, while interest rates still running near decade highs.
Fiscal reform should be a key priority for the next administration, but any adjustment is more likely to come now from higher taxes than spending cuts, though a Congress more hostile to Lula could stand in the way and force him to negotiate.
Barclays estimate that a fiscal adjustment of around 3% of GDP would be needed just to stabilize debt growth.
#Brazil $EWZ


Austral Research retweeted
Lula will end his 3rd term with public finances in worse shape than he found them, with an average fiscal deficit of 8.6% (vs. prev 7%) of GDP over his term, debt on track to exceed 90% of GDP, while interest rates still running near decade highs.
Fiscal reform should be a key priority for the next administration, but any adjustment is more likely to come now from higher taxes than spending cuts, though a Congress more hostile to Lula could stand in the way and force him to negotiate.
Barclays estimate that a fiscal adjustment of around 3% of GDP would be needed just to stabilize debt growth.
#Brazil $EWZ
MS: Brazil’s 2026 election is fundamentally a fiscal-divergence story.
The candidates' economic programs imply materially different policy regimes: Lula proposes broad continuity with the current fiscal framework and a more active role for the state, while Flavio Bolsonaro favors tighter fiscal rules, administrative retrenchment, privatizations, and greater trade openness.
Execution, however, will depend not only on the presidency but on the composition of Congress and the gubernatorial map.
So far, state-level polling has been favoring centrist/center-right candidates for both Lower House and Senate seats; if sustained, this could imply a more constraining Congress for a Lula administration and a more supportive one for a Flavio Bolsonaro administration..
(...) The fiscal policy proposal of the next administration is key in shaping expectations for Brazil's macro outlook and matters disproportionately for asset prices, in our view. This is because, we argue, the urgency to do a fiscal adjustment is increasing. Brazil’s fiscal risk is not an immediate solvency problem; however, it has a debt-stabilization challenge increasingly intertwined with growth, interest rates, and structural budget rigidities.
$EWZ #BRL
Austral Research retweeted

Lula teve 11 MILHÕES DE VOTOS A MAIS do 1º para o segundo turno.
Flávio teve cerca de 3 MILHÕES DE VOTOS A MAIS do 1º para o segundo turno.
Acho que isso é algo INÉDITO no planeta! Matematicamente é quase impossível isso acontecer.
Por que digo isso? Porque com mais de 130 milhões de brasileiros, 47% escolheram Flávio e 45% Lula.
14 milhões de pessoas deveriam seguir um mesmo padrão, ou padrão parecido, mas o que aconteceu foi que dos 14 milhões que votaram em outro candidato ou não foram votar no 1º turno, foram:
21% em Flávio
79% em Lula
Mesmo que essa quantidade estivesse no NORDESTE, seguindo padrão do nordeste não seria isso tudo! O nordeste deu 65% para o Lula.
Foi MUITO ESTRANHO essa quantidade toda para Lula.

Austral Research retweeted
Lula will—for the first time—have to govern with a highly adverse Congress, with both chambers of Congress firmly controlled by the opposition.
This could complicate Lula’s fiscal agenda and leave him more politically vulnerable to potential impeachment proceedings.
#Brazil
Brazil’s election has moved to a runoff, but the Senate result may be just as important for investors and policymakers.
Flávio Bolsonaro led Lula 47.0% to 45.2% in the first round, with virtually all polling stations counted. Neither cleared 50%, so the two face each other again on October 25.
Bolsonaro's PL is projected to hold 28 of the Senate’s 81 seats: roughly 18 senators elected in 2022 remain in office, while the party added 10 seats in this year’s election, as two-thirds of the Senate’s 81 seats were contested on Sunday.
This matters because the Senate confirms Supreme Court justices, central-bank directors and ambassadors, and can also try Supreme Court justices in impeachment proceedings.
A more right-leaning Senate could therefore materially constrain or support the next administration.
For markets, the new Senate will help determine how much room the next government has to shape trade, tariffs, investment policy and institutional reforms.
$EWZ


Austral Research retweeted
Brace for impact. $EWZ -18% now in the overnight session, as we are heading for a historic bloodbath in the brazilian stock market tomorrow.


Austral Research retweeted

If $EWZ holds −22%, it will be the 2nd-worst day in the ETF's history, behind only COVID.
Here are the biggest one-day drops of 10 crises since 2000, and how far each one fell:

Brace for impact. $EWZ -18% now in the overnight session, as we are heading for a historic bloodbath in the brazilian stock market tomorrow.
Lula will—for the first time—have to govern with a highly adverse Congress, with both chambers of Congress firmly controlled by the opposition.
This could complicate Lula’s fiscal agenda and leave him more politically vulnerable to potential impeachment proceedings.
#Brazil
Brazil’s election has moved to a runoff, but the Senate result may be just as important for investors and policymakers.
Flávio Bolsonaro led Lula 47.0% to 45.2% in the first round, with virtually all polling stations counted. Neither cleared 50%, so the two face each other again on October 25.
Bolsonaro's PL is projected to hold 28 of the Senate’s 81 seats: roughly 18 senators elected in 2022 remain in office, while the party added 10 seats in this year’s election, as two-thirds of the Senate’s 81 seats were contested on Sunday.
This matters because the Senate confirms Supreme Court justices, central-bank directors and ambassadors, and can also try Supreme Court justices in impeachment proceedings.
A more right-leaning Senate could therefore materially constrain or support the next administration.
For markets, the new Senate will help determine how much room the next government has to shape trade, tariffs, investment policy and institutional reforms.
$EWZ

