BetterIRR (@BetterIRR) header
BetterIRR (@BetterIRR) profile picture

Stonks: Prefer low starting multiple + margin expansion + robust topline

Joined April 2020
Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)Photo by BetterIRR (@BetterIRR)
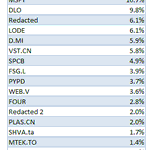
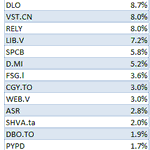
With FDA now officially allowing a path for peptides, $NURS.V / $VST.CN should be up a lot more.
2
1
13
1,920
BetterIRR retweeted
Free newsletter: Anthropic’s S-1 uses an anomalous quarter to con investors into becoming its exit liquidity, and explicitly states that its costs will grow aggressively as margins decline. Its $430bn in non-cancellable contracts are yet to start hitting. wheresyoured.at/exit-liquidi…
48
166
26
1,125
131,266
Lot of value in these @PlanetMicroCap events, already pitched an interesting (potential) multibagger during the networking session.
10
1,716
BetterIRR retweeted
Now I understand the fund performance
unavailable
3
3
2
103
29,079
Anthropic's S1 looks fine on the surface. Bear's argument was never that they couldn't show an OK quarter, rather the core arguments are: 1) existing ARR is inflated via a VC funding bubble 2) open source is an existential threat 3) if they misjudge demand their mandatory 1/2
8
3
97
23,214
spending commitments will bankrupt them.
23
2,646
Even if you pay with a convertable note, it would still be recorded as an expense no? Unless there is some funky SPV stuff.
This quoted post is unavailable.
7
22
11,342
The AI boom is narrower than almost anyone admits. The top 10% of firms account for 99.5% of all model-serving spend, 99% of neocloud, and 95%+ of OpenAI and Anthropic billings. And 80.4% of the heaviest AI spenders run on venture capital, not their own revenue. This is a concentrated, circular buildout. A handful of companies are the entire trade.
34
39
13
257
31,733
Is the AI boom a bubble outside Tech? 📉 Rev per worker: S&P 493 flat 📉 Profit margins: S&P 493 flat 📉 Productivity boost: None Non-tech sees AI token spend as a cost center, not growth. The macro AI story will be decided in the S&P 493, not the Mag 7. T at Apollo
12
25
15
133
15,744
This is a worse data set than ramp but tells the same story. All the AI growth (declerating as it is) is being driven by the top 1% VC funded companies. Ex AI lab VC funding is already 0.5T. This bubble only goes on if ever larger VC cheques are written.
👀Yipit coverage of Anthropic below
3
19
4,919
(And 500B is a lot already.) Either $NVDA (or someone?) starts parabolically funding VC firms or this is all over.
702
Modeling $REAX is an incredibly frustrating experience. That said I feel pretty good that we are close to 14x synergized pre-tax earnings (48M). Not the worst price to pay for a secular winner in REAL at the trough of the cycle.
3
8
2,994
If you think they can get there in say 5 years you're looking at a tripling of pre-tax income in 5 years. On top of that, you likely have a housing recovery sometime within those 5 years further juicing things. The base biz will also be growing, REAL had impressive share gains.
1
1
517
Anyone have a strong view on the name? Think it's a good setup.
1
519
Your hyperscalers are dead money for 2 to 3 years: -> Over earning across the board (implemented price hikes on non AI workloads via compute + memory constraints) -> Neocloud BKs will lead to distressed GPU pricing -> Equity investors will start paying attention to massive 1/x
3
2
1
70
14,362
Off balance sheet lease + obligations -> hypers will either have to keep funding the labs funding w/ no hope of return or do it themselves in house to not loose edge (perma a worse business than pre-ai) -> Over capacity comes with structurally higher cost base need absorb
2
11
2,629
Was it this easy to call the top in the dot com bubble?
22
1
3
81
20,711