

Canadian Investor 🇨🇦 - Building wealth in public - ETFs, stocks & personal finance - Maxing my TFSA - Research, lessons & the real journey - DYOR
Montreal, Quebec
Joined March 2023
- Tweets157K
- Following3.2K
- Followers12.1K
- Likes166K





Pinned Tweet
Supporting Canadian small businesses is always a win in my books! 🇨🇦
If you haven't checked out Seb's Soaps yet, they're a Québec-based company offering natural, vegan and cruelty-free products. 🧼
Not sure where to start? I'd recommend checking out their bundles:
🧼 Ambassador's Bundle - $58.95
🏕️ Camper's Bundle - $29.45
☕ Coffee Lover's Bundle - $28.45
✈️ Traveler's Bundle - $14.95
Even better, my community gets 15% OFF their first order!
Shop here: sebs-soaps.com/BRANDON
A great way to discover new products while supporting a Canadian business! 🇨🇦

Before buying any individual stock in a TFSA, I look at three things:
1. Durable competitive advantage
Can the business protect pricing, customers, and margins over time?
2. Clean balance sheet
Low debt, strong liquidity, and the ability to survive a downturn without diluting shareholders.
3. A valuation I can defend
Not just “cheap.” A price that still works if growth slows.
Everything else is noise.
What do you screen for first?
Canadian investors: don’t waste TFSA room on low-growth cash if you have decades to invest.
Put growth assets where compounding is tax-free.
Keep shorter-term money elsewhere.
The account structure should match the asset, not the other way around
Goodnight, FinX! 🌙
October has been a wild ride. Let’s see what the markets have in store tomorrow.
Rest up, everyone!


Brandon Wealth 🇨🇦 retweeted

$SOFI faithful let's stay out of goblin town. SoFi is back above the 200 week EMA and we really don't want to go below that again.
That 50 week going under the 100 week soon is bearish lagging and mostly just explains what has happened. Especially since SoFi has been sideways most of the year.

Canadian investors, I’m curious.
If you had to choose ONE strategy for the next 20 years:
Buy and hold $XEQT.TO
Build your own portfolio of individual Canadian stocks
Which would you choose, and why?
Let’s hear your reasoning.
Canadian Investing Fun Fact:
The Toronto Stock Exchange (TSX) dates back to 1861.
Before Confederation.
Before the Canadian dollar.
Before the oil sands boom.
That’s 6 years before Canada officially became a country.
Over 165 years of Canadian market history. 🍁
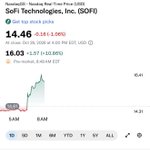
SoFi $SOFI Beats Q3 Earnings!
Shares up ~10 %premarket!
Revenue: $1.4B (+44% YoY) vs. $1.25B expected
EPS: $0.18 vs. $0.17 expected
Members: 17.1M
Deposits: $51.3B
Record loan originations: $16.9B
Raised full-year 2026 outlook
2027 revenue forecast: ~$6.4B
2027 EPS forecast: $0.90
Strong quarter for $SOFI!
X will be cheering them on all day!

GM FinX!
Happy Tuesday! New day, new opportunities.
Stay focused. Think long-term. Build wealth.
One day at a time!

🇨🇦 Celestica CLS.TO Q3 2026 Deep Dive: AI Growth Is Accelerating 🚀
Celestica delivered another exceptional quarter, raised its 2026 guidance, and introduced an ambitious 2027 outlook.
With shares down significantly from their highs, is this a long-term opportunity or are investors overlooking the risks?
Let’s look at the numbers. 👇
- The Business
Celestica is a Toronto-based technology manufacturer increasingly exposed to AI infrastructure and data centres.
Its Connectivity & Cloud Solutions (CCS) segment, which supplies networking, servers, and cloud infrastructure, now represents approximately 84% of revenue.
Q3 2026 Results (USD)
- Revenue: $5.83B (+83% YoY)
- Adjusted EPS: $3.30 (+109%)
- Adjusted operating margin: 8.5% (record)
- CCS revenue: $4.87B (+102%)
- ATS revenue: $960M (+23%)
Revenue and adjusted earnings exceeded expectations, with continued strength in hyperscaler demand.
What stands out is that Celestica isn’t just growing revenue. Its adjusted operating margins are expanding as well.
2027 Outlook: The Biggest Surprise
Management introduced ambitious targets:
- Revenue: $40B (+90% vs. 2026 outlook)
- Adjusted EPS: $21.50
- Adjusted operating margin: 9%
- Capital expenditures: $1.5B–$2B
For perspective, Celestica expects $21B in revenue for 2026.
Management also indicated that customer forecasts for 2028 are meaningfully higher than its 2027 outlook.
That’s extraordinary growth, but executing on that scale will require substantial investment.
The Concern: Free Cash Flow
Despite stronger earnings expectations, management reduced its 2026 free cash flow guidance:
- Previous: $600M
- Updated: $460M
That’s a 23% reduction.
The primary reason is higher working-capital requirements, particularly inventory needed to support future demand.
Celestica also raised approximately $3.45B through an equity offering, strengthening its balance sheet but diluting existing shareholders.
My concern: Revenue and earnings are accelerating, but cash generation isn’t keeping pace.
Investors need to see those investments translate into sustainable free cash flow.
Valuation
At the pre-earnings TSX closing price of approximately C$347, Celestica trades around 11.8x management’s projected 2027 adjusted EPS, assuming USD/CAD of 1.37.
For a company forecasting 90% revenue growth, that valuation looks interesting.
However, it depends heavily on management delivering its targets.
Bull Case
- Explosive AI infrastructure demand
- Strong hyperscaler relationships
- Expanding adjusted operating margins
- Ambitious 2027 growth outlook
- Strengthened balance sheet
- Potentially attractive forward valuation
Bear Case
- Significant customer concentration
- Reduced free cash flow guidance
- Rising inventory and capital requirements
- Shareholder dilution
- Heavy dependence on hyperscaler spending
- Execution risk associated with rapid expansion
What I’ll Be Watching
Over the next several quarters:
Free cash flow conversion and inventory levels
Progress toward 2027 revenue targets
Operating margin sustainability
Hyperscaler demand and customer concentration
Returns on the company’s substantial capital investments
My Long-Term Outlook
Celestica is becoming one of Canada’s most interesting AI infrastructure companies.
Revenue growth is exceptional, margins are improving, and the 2027 outlook suggests management sees substantial demand ahead.
But strong revenue growth doesn’t automatically translate into shareholder value.
At these valuations, the opportunity looks compelling if management executes.
My takeaway:
The biggest question isn’t whether Celestica can grow.
It’s whether that growth can translate into sustainable free cash flow per share.
Are you bullish on $CLS.TO at these levels, or waiting for better cash flow conversion?
Not financial advice. Financial figures in USD unless otherwise noted.
My portfolio got smoked last week and I'm still not selling
Hardest part of investing isn't picking stocks.
It's sitting through the red days without doing something dumb.
Celestica ($CLS.TO) delivers an impressive Q3!
Q3 Highlights (USD):
- Revenue: $5.83B (+83% YoY)
- Adjusted EPS: $3.30 (+109% YoY)
- Adjusted operating margin: 8.5%
Growth Outlook:
- 2026 revenue guidance raised to $21B
- 2027 revenue projected at $40B (+90%)
- 2027 adjusted EPS forecast: $21.50
AI infrastructure demand continues to drive exceptional growth.
After a sharp recent selloff, these results reinforce the company’s growth story.
Is $CLS.TO still a buying opportunity at these levels, in my opinion it is!

October has been a challenging month for my TFSA. 🇨🇦📉
Currently down 1.93% over the past month, but my long-term investment strategy remains unchanged.
Still hoping to finish October in the green.

$HLF ripping +76% today.
Japan’s Umios buying High Liner at $27 cash.
~79% premium to Friday’s close.
Deal valued at ~$804M.
HQ stays in Nova Scotia. Closing targeted Jan 2027.
Bang 💣

Brandon Wealth 🇨🇦 retweeted
Quality matters in the neocloud space. I think lumping them all together is a mistake. Neoclouds can still get loans but it’s getting harder and how much they pay comes from how risky they look.
Lenders care a lot about how strong customers are and how long those customers are signed up for since that’s the money that is paying back the loan. How new the company is and how much debt it already has are obviously key as well.
Musk is arguing lenders have mostly stopped lending to companies that don’t bring in a lot of revenue outside AI data centers and he uses $SPCX as the example.
They have Starlink and launch revenue and last week it cost about 2.3% a year to insure their debt against default. $CRWV makes almost all their money from AI data centers and it cost about 11% a year to insure their debt.
But it doesn’t look like you need outside revenue to borrow yet. $NBIS makes almost all their money from AI cloud. They have customers like Microsoft and Meta and on Oct 17 during this selloff they got a one year $3.5B loan from Citi starting at about 6.7%.
Compare this with Volta which is a new company and got a loan at about 10.5% two days earlier. They had to pay more than first planned to get it sold.
Trump says a Canada trade deal is coming “pretty soon.”
His team says talks are “very close.”
Canada says it won’t rush a bad deal.
New 50% tariff tweaks hit Oct 30.
Deal, or midterm talk, what do you think ?
Good morning, FinX! ☕🇨🇦
Happy Monday, New week, new beginnings as I start my new job today!
Wishing everyone a great day and a productive week!

Brandon Wealth 🇨🇦 retweeted
I think Trump’s deal with Russia is about getting Ukraine to stop hitting Russian refineries. Trump keeps pushing for it since Ukraine hitting those refineries is a big part of what’s holding back Russian fuel. If Ukraine stopped Russia could fix them and export more but bigger repairs take months.
I don’t think Russia is offering unlimited diesel. Their deputy prime minister said buyers can have as much as they want from what Russia will export. And so far this month Russia is exporting about the same amount as last month. Not sure this does much for diesel prices.
The deal is also a big change in US policy. The US is letting Russian diesel in even though Congress banned it. I have seen senators from both parties say this breaks that law so we have to see how this develops.

U.S. stock futures are looking relatively flat heading into tomorrow’s trading session.
Let’s see what tomorrow brings!
Good night, everyone!

