

«All of humanity’s problems stem from man’s inability to sit quietly in a room alone» | Value | Special Sits | Global Equities | 23
Stockholm, Sweden
Joined November 2020
- Tweets1.8K
- Following200
- Followers1.7K
- Likes16.7K



Pinned Tweet
Planned a tweet, but had too much to say on $EVC.
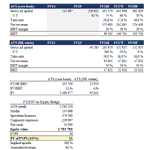
ATS growth went from +123% to +230% (4Q25 to 2Q26) and EBIT >tripled, yet the EBIT multiple fell from 21x to ~5x (ex media+spectrum) w/ px up just 53%. New CMO, 2 new directors and a strong ranking add to the case.
Link in bio!

Using a/r and exit rate from the HK account as a proxy for spend (assuming unchanged payment terms), there was a pick-up at quarter-end (+10% vs. Q2), suggesting spend has either stabilized or is ramping. Also indicative of Smadex’s clients adjusting, rather than pulling spend.


$EVC Q3 print: ATS rev +133% yy (-3% seq) vs. guided floor of > 100% yy. Take-rate rose to 39.4% (38.8%), while the core book grew 68% yy and 19% seq. Concentration risk fell w/ the HK customer now = 30% of group rev. #2 whale now = 8% (+59% seq), and EVC sold 1 station for $30m.


$EVC Q3 print: ATS rev +133% yy (-3% seq) vs. guided floor of > 100% yy. Take-rate rose to 39.4% (38.8%), while the core book grew 68% yy and 19% seq. Concentration risk fell w/ the HK customer now = 30% of group rev. #2 whale now = 8% (+59% seq), and EVC sold 1 station for $30m.
Planned a tweet, but had too much to say on $EVC.
ATS growth went from +123% to +230% (4Q25 to 2Q26) and EBIT >tripled, yet the EBIT multiple fell from 21x to ~5x (ex media+spectrum) w/ px up just 53%. New CMO, 2 new directors and a strong ranking add to the case.
Link in bio!
ATS EBIT+margin fell q/q on sales, engineering and adops hiring plus a multi-cloud migration. Media’s Q3 was very weak (though political spend is mostly Q4), but the silver lining is that mgmt is exploring options for the TV stations, pointing to a partial media/ATS separation.


TheOracleOfOslo retweeted

After two decades helping grow some of the biggest names in gaming, from Angry Birds and Candy Crush to NBA 2K, Luis de la Camara is joining Smadex as our new Chief Marketing Officer!🎉
Read the full announcement 👉 lnkd.in/enKaaF-q
TheOracleOfOslo retweeted

Small Cap stocks don’t even try to go up anymore. They just look at you like this.

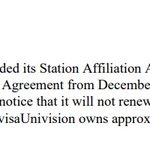
$EVC's TelevisaUnivision affiliation got a 3-month extension, w/ quarterly rolling. It provides some visibility, but reads like a stopgap while talks continue.
Maybe a bit far-fetched, but could TelevisaUnivision be eyeing EVC's TV stations now that the 39% cap is being lifted?


Small contract, but it ends a months-long silence. $HAV notes that scopes like this typically generate NOK 40-60m in revenue, and that engineering and procurement kick off this year.


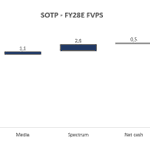
On EVC, assuming the core book keeps compounding, a 64% drop in HK spend and 12/4x multiples = >3x. $HAV flipped in the q on weak order intake, but the asymmetric setup, promising mgmt commentary re the strategic review and better 2027 visibility by Q3 reinforce my conviction


$EVC: mgmt guided for >100% Y/Y in Q3 and Q4, but the stock got beaten up on concentration and the guide down. Meanwhile ATS core (ex. HK whale) grew 81% Y/Y. I dig into whether Smadex is any good, the CTV inflection, an updated valuation and everything in between. Link in bio!

$HAV: SEAM's 2025 numbers are out. Hanwha paid ~20x FY25 EBIT (NOK 102m) for 38% rev growth/10.8% margin vs. 62% at 10.4% margin for NES. NES growth has accelerated this year but applying the same multiple to its '25 EBIT = 165% upside w/ 0 value to RemainCo. On FY26e, it's a 4x


$HAV Q2: rev +38% y/y, EBITDA NOK 17.3m (6.5% margin vs. 2.1% in 2Q5). VERY disappointing order intake at NOK 35m (0.13x book-to-bill), and the backlog dropped further to NOK 826m. But w/ NOK 237m of net cash, you're paying sub 4x EBITDA run rate for a biz mgmt expects to inflect


I'll be publishing an update on $EVC soon, but Dylan's letter is a must-read. He covers the 3 assets (ATS, Media and spectrum) in great detail, Smadex's differentiation and flywheel, CTV, Starlink/MNOs driving spectrum value, and more. Highly recommend!

$CEDER 4Q26: rev +14.5% y/y, EBITA SEK 28.1m (6.7% margin vs. 9% in 4Q25). BUT the margin was hit by a larger holiday-pay liability swing and Main Market listing prep costs. Adjusted for both, underlying EBITA margin was 8.7%, translating into a valuation of ~4x EBITA run rate


$HAV Q2: rev +38% y/y, EBITDA NOK 17.3m (6.5% margin vs. 2.1% in 2Q5). VERY disappointing order intake at NOK 35m (0.13x book-to-bill), and the backlog dropped further to NOK 826m. But w/ NOK 237m of net cash, you're paying sub 4x EBITDA run rate for a biz mgmt expects to inflect