



Pinned Tweet
When $AMD was at $80.
Me: “I’m convinced. AMD will be the next $1T giant.”


Christian Darnton retweeted
“You know when you find something so interesting you just want to keep it to yourself? Me neither.”
A comment I received on my latest Bending Spoons ($BSP) research.
Pretty much sums up why I started writing about investing in the first place.
I spend an unreasonable amount of time researching businesses, and I genuinely enjoy sharing what I find.
Most of my deeper research now goes to members of Quantum Group, but I've made this overview public for everyone.
Enjoy.
substacktools.com/sharex/kvo…

Christian Darnton retweeted
In 2025, Bending Spoons ($BSP) received 800,000 job applications.
It hired JUST 286 people...
Revenue per employee has DOUBLED in two years.
This tells us something fascinating about what Bending Spoons is actually building.
And it's not what most investors think...
🧵

Christian Darnton retweeted
$amd was like $110 here...
Christian Darnton retweeted
Literally doesn’t matter.
Catalysts don’t move stock prices long term.

$ASTS Analyst Updates 👇
🟢 Clear Street: Buy — $115
🟢 Roth: Buy — $108
🟢 Deutsche Bank: Buy (↑ from Hold) — $93
🟢 Berenberg: Buy — $92
🟢 Scotiabank: Sector Outperform (↑ from Sector Perform) — $55.70
🟡 Bank of America: Hold — $80
🟡 B. Riley: Neutral (↓ from Buy) — $65
🟡 Piper Sandler: Neutral (↓ from OW) — $54 (from $98)
🟡 UBS: Neutral — ~$78
Average price target: ~$75–80
Most analysts remain constructive on the strategic setup, but price targets vary widely.
Bull Case 🟢
• SpaceX becoming a carrier could push AT&T, Verizon & T-Mobile toward neutral partnerships.
• Spectrum value supports a large part of enterprise value.
• Next-gen SpaceX D2D still depends on Starship (~2028, unproven cadence).
• ASTS remains positioned ahead in commercial broadband timing.
Bear Case 🟡
• Launch cadence and timeline delays.
• Falcon 9 dependency and New Glenn constraints.
• Potential pricing pressure and launch-access competition from SpaceX.
Christian Darnton retweeted
Yes.
Not sure why so many are angry about this.
Odd.
$NAUT

Is $DUOL Going to $0 or $1,000?
Christian Darnton retweeted
FYI.
I haven't sold.
If I am wrong, you will all be able to see, publically.

So this $HIMS permabull who authored the gem below a few months ago suddenly says that he “sold at the top”.
How convenient.

And AI is accelerating this.
In 2025, AI contributed to fewer than 10% of software code changes.
By Q1 2026, it exceeded 90%.
For a company acquiring businesses that often require extensive technological restructuring, the operational leverage gains are substantial.
There are risks, of course.
Despite extraordinary growth, organic revenue has been modest.
Net revenue retention remains below 100%.
The question is whether management is creating sustainable cash flows or extracting more value from businesses that eventually deteriorate.

My thesis is relatively simple.
Bending Spoons' most important feature isn't acquiring Evernote, Vimeo or AOL.
It's the organisation itself - "The Platform"
Management is attempting to make organisational optimisation reproducible, then use that capability to compound capital over decades.
I've published my research on $BSP completely free, including the financials, operating model and risks.
My deeper research is available here - for free:
christianinvesting.substack.…
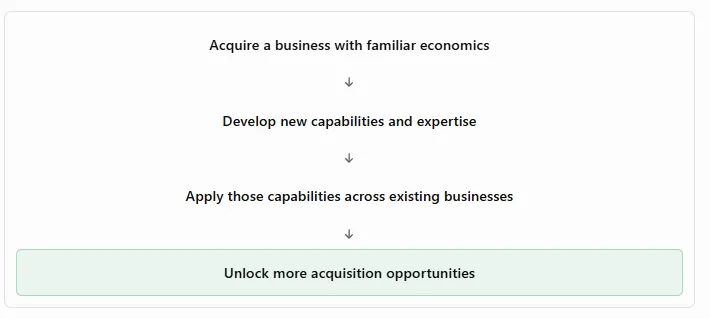
Now think about the implications.
A better pricing model developed for one business improves monetisation across the portfolio.
Each acquisition contributes more data and experience.
The Platform itself could become increasingly valuable.
Free cash flow has also increased substantially.
2023: ~$55M
2024: ~$204M
2025: ~$290M
That's more than a fivefold increase in two years.
The important question is how much sustainable cash flow $BSP can generate from each acquired business relative to the price it pays.
And the financial results have been extraordinary.
Revenue:
2023: $387M
2024: $671M
2025: $1.31B
That's 84% annualised revenue growth.
Of course, some of this growth has come from acquisitions.
But the cash generation is equally interesting...

Consider Evernote.
Millions of users. Proven demand.
But inefficient operations.
$BSP acquires the company, restructures its organisation and integrates it into the Platform.
The product already works.
Management believes it can make the organisation work better...
I've argued for years that exceptional businesses share a recurring set of characteristics.
Culture. Incentives. Structure.
These properties determine how effectively a company makes decisions and allocates resources.
$BSP appears to have recognized the same thing...

But $BSP isn't simply identifying what makes organisations exceptional.
It's attempting to turn these characteristics into a repeatable operating system.
One that can be installed across every business it acquires.
This is the most interesting part of the entire company...