

Enrolled Agent | Author | Tax Preparer and Advisor My sites: https://nitter.gq/t.co/sI1SL1hPXM Buy The Crypto Tax Book on Amazon: https://nitter.gq/t.co/OF4zUTZEpL
Florida, USA
Joined March 2009
- Tweets32.1K
- Following2.3K
- Followers1.3K
- Likes243K




Pinned Tweet
In case you haven’t heard . . .
I wrote a book!
Not just any book. And not an obvious book like The Accountant’s Guide to Tax Preparation. Not only would that be boring—so boring nobody would read it—it’s also on a topic that has been written about thousands of times.
Sold crypto in 2026? Early next year, your exchange will send you a new tax form called Form 1099-DA. Here’s what to know before you file. 📊
Your form will sort your crypto into two groups:
✅ Covered: crypto you bought in 2026 and kept on the same exchange until you sold it. The exchange knows what you paid, so it reports both your sale price and your cost to the IRS.
⚠️ Noncovered: crypto you bought before 2026, or moved in from another exchange or a personal wallet. The exchange only reports what you sold it for. It may not know what you paid.
Why it matters:
• A blank “cost” box does not mean your cost was $0. If you don’t report what you paid, you could end up paying tax on the entire sale amount instead of just your profit.
• Sharing your records with the exchange doesn’t make it responsible for your numbers. Proving what you paid is still up to you.
• One sale can come with more than one form. That’s normal when older and newer coins are sold together.
If your form doesn’t match your own records, it isn’t automatically a mistake, as long as you can back up your numbers.
What to do now: gather your purchase history, especially for crypto bought before 2026 or moved between wallets and exchanges.
1
2
950
Starting January 1, 2027, a new federal tax credit can lower your tax bill dollar-for-dollar. The Federal Scholarship Tax Credit (also known as the Education Freedom Tax Credit) rewards cash donations to approved Scholarship Granting Organizations (SGOs) that fund K-12 scholarships.
An individual can claim up to $1,700 per year, and married couples filing jointly up to $3,400. Unlike a deduction, which only lowers taxable income, this credit reduces the taxes you actually owe.
Donations cannot go to a single school or a specific student. They go to the SGO, which must serve at least two schools and 10 or more children. Families then apply for funds that can cover tuition, tutoring, and test prep.
Most states have opted in. Washington, California, Michigan, and Pennsylvania have not. However, you do not need to live in the SGO’s state. As long as you give to an SGO on a participating state’s approved list, you can claim the credit.
If you are looking for where to give, Dave Ramsey recommends ACE Scholarships. ACE is a national nonprofit SGO that has been delivering K-12 scholarships for more than 25 years.
You can read more about ACE here:
acescholarships.org/eftc/

51
Ralph Mendoza, EA retweeted

Coinbase just made crypto loans available in all 50 states.
Borrowing against your Bitcoin isn't a sale.
Getting liquidated is.
And you can owe tax on a liquidation that puts $0 in your pocket.
Here's how it works.
You pledge BTC. Coinbase converts it 1:1 to cbBTC and moves it to Morpho. You get USDC.
A loan generally isn't income, so the USDC you receive isn't taxed.
But if your debt plus interest hits 86% of your collateral's value, a liquidator can repay the loan and take your collateral, plus a 4.38% penalty on the debt repaid.
You didn't click "sell." The IRS will likely treat it as a sale anyway.
Hypothetical:
• You bought 1 BTC years ago for $10,000
• You pledge it and borrow $50,000
• BTC slides to $58,000, and your loan hits 86%
• If the whole loan is liquidated, about $52,000 of your BTC (0.9 BTC) is taken to repay it plus the penalty
That's roughly $41,000 to $43,000 of long-term capital gain, depending on how the penalty is treated.
At a 15% rate, about $6,200 to $6,500 in federal tax.
Cash you get from the liquidation: $0. It all goes to the lender.
Same coin, same price drop, but the borrower who topped up collateral in time owes $0 and still owns 1 BTC.
Two more things almost nobody mentions:
• Interest on a loan you spend on personal stuff isn't deductible. Use it to buy investments and it may be investment interest, but only if you itemize.
• The IRS hasn't issued guidance on whether wrapping BTC into cbBTC is a taxable swap. Keep your original purchase dates and cost basis either way, and talk to a pro before you file.
Borrowing can be a smart way to get cash without selling.
Just know your liquidation price, set alerts, and keep cash ready to top up.
Would you rather borrow against your BTC or sell and pay the tax now?
If you overreported capital gains on the disposition of crypto, but found cost basis that show a loss instead, you are likely sitting on a possible tax refund.
This is one of the most common and most expensive errors digital asset investors make. When a taxpayer cannot locate their historical acquisition costs across multiple decentralized wallets and defunct exchanges, they often file with a $0 cost basis. Consequently, the IRS taxes 100% of the gross sale proceeds as pure profit.
If you have since located the missing transaction data, here is exactly how you can correct the record and claw back your overpaid taxes:
1. File an Amended Return (Form 1040-X)
You are not permanently locked into the artificial gains you reported on your original return. By aggregating your fragmented wallet histories and establishing the true acquisition cost, you can file an amended return to correct the historical Schedule D and Form 8949.
2. Trigger a Retroactive Refund
By officially proving the disposition was actually a loss, you wipe out the fabricated capital gains tax liability you paid for that specific tax year. This triggers a direct refund from the Treasury for the overpayment.
3. Unlock the Capital Loss Deduction
Correcting the record does more than just erase a phantom gain. Establishing the actual capital loss allows you to offset up to $3,000 of your ordinary income for that tax year. Any remaining loss balance is then carried forward indefinitely to shelter your future investments from capital gains taxes.
4. The Strict Statute of Limitations
You cannot delay this process. Under IRS rules, you only have a three-year window from the original filing deadline (or two years from the date the tax was paid, whichever is later) to submit your Form 1040-X and legally claim the refund. Once that statute of limitations expires, your overpayment belongs to the government permanently. As of today, the standard three-year window allows you to file an amended return (Form 1040-X) and claim a refund for tax years 2023, 2024, and 2025.
2
322
Ralph Mendoza, EA retweeted

Most business owners would be better off learning how to make more money/reinvest into cash flowing assets than obsess over paying less or minimum taxes.
Both are good, but don’t let the tail wag the dog.
The IRS and Treasury just finalized the new SECURE 2.0 automatic enrollment rules and business owners have a strict new compliance mandate to prepare for. The U.S. Department of the Treasury and the Internal Revenue Service (IRS) today issued final regulations to help more Americans save for retirement through their workplaces. The regulations implement a key provision of the SECURE 2.0 Act, providing employers with clear guidance on automatic enrollment for certain 401(k) and 403(b) retirement plans. The rules help workers build retirement savings while preserving their control over how much they contribute. Treasury estimates that SECURE 2.0’s automatic enrollment expansion provision will increase retirement savings by an average of $4.2 billion annually over the 2023-2032 period.
Covered plans are now required to automatically enroll eligible employees at a starting contribution rate of 3%. Covered plans are now required to automatically enroll eligible employees at a starting contribution rate of 3%. Employees may opt out or choose a different contribution rate. The Treasury estimates this structural shift will force an average of $4.2 billion in new retirement savings annually.
For employers, these finalized regulations generally apply to retirement plan years beginning after December 31, 2027. However, the IRS has clarified that certain statutory exceptions apply for qualifying small businesses, newly established businesses, governmental plans, and SIMPLE 401(k)s.
You can read more from the IRS here:
irs.gov/newsroom/treasury-ir…
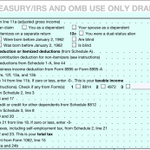
Now that the IRS has released the draft form 1040, it can be confirmed the charitable deduction for non-itemizers will go on line 12f as an additional deduction. However, it does not affect the adjusted gross income. It will reduce your taxable income.

Ralph Mendoza, EA retweeted

New from me: Itemizing is so back.
That's a key takeaway from a fresh batch of IRS data on the tax returns filed this year.
Tax year 2024: 31% itemizing rate for incomes $250k-$500k.
Tax year 2025: 57%.
For more:
wsj.com/personal-finance/tax…

Ralph Mendoza, EA retweeted

A Georgia resident is bringing a class action against one of the promoters of nonexistent sovereign tribal tax credits, the latest in a string of lawsuits from people who thought they were lowering their tax bills but ended up owing even more to the IRS. news.bloombergtax.com/daily-…

If you are considering changing your tax professional for the upcoming filing season, waiting until January or February to make the switch is one of the most expensive mistakes you can make. The tax professional who was a perfect fit for a simple W-2 might be the wrong fit if you have started a business, entered high-income brackets, or begun trading digital assets. If you have outgrown your current preparer, here is why you must initiate the transition right now, before the calendar year closes:
1. The Window for Proactive Tax Strategy Closes December 31
A standard tax preparer simply records history; a tax advisor helps you change it. If you wait until tax season to meet your new professional, the tax year is already locked. By engaging an advisor now, you have time to execute crucial end-of-year strategies—such as maximizing retirement contributions, executing Roth conversions, harvesting capital losses, or making strategic equipment purchases that actually reduce your final tax bill.
2. Securing Historical Carryforward Data
Switching tax professionals requires a meticulous transfer of historical data. Rushing this process in March often leads to lost deductions. Your new advisor needs time to request and review your prior returns to capture essential carryforward items, including:
-Net Operating Losses (NOLs)
-Capital loss carryovers from previous market downturns
-Depreciation schedules and fixed asset histories
-Passive activity loss carryovers
3. Evaluating New Complexities (Like Form 1099-DA)
If your financial footprint has expanded to include multi-state income, a new corporate entity, or heavy cryptocurrency trading, a high-level practitioner needs time to review the architecture. For example, with the incoming IRS Form 1099-DA crypto reporting rules, waiting until the spring rush means your new preparer will not have the bandwidth to properly aggregate your wallets and reconstruct missing cost bases.
4. Top-Tier Firms Cap Their Rosters Early
Elite Enrolled Agents and CPAs actively manage their capacity to maintain high service standards. The best professionals often close their books to new clients well before the spring filing rush begins. If you wait until tax season, you will likely be turned away by top-tier advisors and forced to settle for a volume-based filing mill.
You should never feel like a reactive afterthought to your tax professional. You should start to build a proactive, audit-ready architecture for your wealth as soon as possible.
The IRS just issued its first official alert for the 2027 tax filing season, and sweeping legislative changes mean you cannot wait until April to get your financial records in order. Under the newly released IR-2026-140, the IRS is urging taxpayers to prepare for changes in how returns are filed, what deductions are available, and how refunds are issued for the 2026 tax year.
Here is what you need to prioritize before year-end to ensure a seamless filing season:
1. The End of Paper Refund Checks
In accordance with Executive Order 14247, the IRS is actively phasing out paper tax refund checks. Direct deposit is now essentially mandatory. Ensure you have accurate bank routing and account numbers ready, whether through a traditional bank, credit union, or digital wallet or your refund will face severe logistical delays.
2. New Deductions to Track
The implementation of the Working Families Tax Cuts introduces several new, highly specific tax-saving opportunities for 2026. You must gather precise documentation now if you plan to claim the new deductions for qualified tips, qualified overtime compensation, passenger vehicle loan interest, or the enhanced standard deduction for seniors.
3. Digital Access & Form 4547
The IRS is rapidly expanding its digital infrastructure. By setting up an IRS Individual Online Account (accessible via ID.me or Login.gov), you can instantly retrieve your Identity Protection PIN (IP PIN), authorize your tax professional digitally, and submit required forms online—including the newly introduced Form 4547 for the Trump Account.
4. Crypto & Digital Asset Aggregation
The IRS explicitly highlighted "records of digital asset transactions" as a primary documentation requirement for this filing season. With increased scrutiny and impending broker reporting rules, you must aggregate your wallet histories and exchange records now to ensure your cost basis and capital gains are accurately calculated.
Do not wait for tax season to uncover missing records or missing tax breaks. Start getting ready now so your tax filing is easier in early 2027.
ID.me

Here is a breakdown of what the new Form 1099-DA will actually look like for your 2026 digital asset transactions and how to prepare for the inevitable reporting gaps.
Starting with the 2026 tax year, cryptocurrency brokers are legally required to report both your gross proceeds and your exact cost basis to the IRS. (While gross proceeds reporting technically began for 2025, mandatory cost-basis reporting kicks in for covered assets sold during 2026.)
However, brokers will not have the complete picture. The information displayed on your 1099-DA will depend entirely on whether your crypto is classified as a "covered" or "noncovered" asset.
1. Covered Assets (Full Reporting)
An asset is considered "covered" if it meets all of the following criteria:
-You acquired it on or after January 1, 2026.
-You acquired it inside a specific broker's account where that broker maintained custody.
-The asset remained in that exact same account uninterrupted until the moment you sold it.
If your asset is covered, the broker will report your gross proceeds, acquisition date, and accurate cost basis directly on the 1099-DA.
2. Noncovered Assets (The Missing Basis Trap)
If your digital assets do not meet the strict criteria above, they are "noncovered." This generally applies to:
-Any cryptocurrency you acquired before 2026.
-Any crypto you transferred into a broker's exchange from a personal hardware wallet, a decentralized protocol, or a different exchange.
Because the broker cannot verify the history of noncovered assets, they will likely check "Box 9" on the Form 1099-DA and leave the cost basis section completely blank.
How to Protect Yourself
A blank or $0 cost basis on your 1099-DA does not mean your actual tax basis is zero. If you do not manually correct this, the IRS will assume your entire sale was pure, taxable profit.
Here is what you need to do before your broker issues your 2026 statements (which are due by February 15, 2027):
1. Aggregate Your Records Now: You must proactively reconstruct your own cost basis using wallet histories, decentralized exchange (DEX) receipts, and transfer records.
2. Establish Your Tax Lots: Track your digital assets strictly by individual wallet and account. If you want to use the "Specific Identification" method to optimize your taxes, you must officially identify those lots no later than the time of the sale and keep the supporting records. If you fail to do this, the default First-In, First-Out (FIFO) accounting method will generally apply.
3. Prepare to Override the 1099-DA: When filing, you will need to use IRS Form 8949 (utilizing adjustment Code B) to manually override the broker's blank basis and report your true acquisition costs. Do not simply assume Code B is correct without verifying the specific Form 8949 instructions for that tax year, as the IRS may update reporting codes.
Ralph Mendoza, EA retweeted
New York City is mailing tax bills to nearly half of the property owners it originally notified as potentially subject to a new surcharge on second homes worth more than $5 million, according to data released by city finance officials. news.bloombergtax.com/daily-…

Can a Chicago ICU nurse earning $92,000 avoid future Bitcoin taxes by buying $500 per month inside a Roth IRA?
Potentially! But the details matter.
In a regular taxable crypto account, buying Bitcoin generally is not taxable. Selling, swapping, or using it to buy something generally can create a taxable gain or loss. Short-term gains generally are taxed at ordinary income rates, while long-term gains may receive lower capital-gain rates.
Inside a properly established Roth IRA, investment trades generally do not create annual capital gains or losses on your Form 1040. Qualified Roth IRA distributions can be tax-free. But not every withdrawal is qualified, and special rules apply to nonqualified distributions.
For 2027, a single filer’s direct Roth IRA contribution phaseout begins at $158,000 of modified AGI and ends at $173,000. A $92,000 salary is below that range if modified AGI is also below $158,000. Contributing $500 per month equals $6,000 per year, below the basic $7,500 2027 IRA limit—assuming no other IRA contributions and sufficient taxable compensation.
The Roth IRA must generally receive cash contributions. The IRA (not the individual) must purchase and custody the Bitcoin through a qualifying trustee or custodian. Personally holding the IRA’s private keys or moving IRA-owned crypto to a personal wallet may create a prohibited transaction and jeopardize the account’s tax-advantaged status.
Finally, selling Bitcoin at a loss inside the Roth IRA generally does not create a deductible tax loss. A Roth IRA may defer or eliminate tax on qualified future distributions, but it does not provide tax-loss harvesting.
You can read the trending financial situation from Yahoo! Finance here:
finance.yahoo.com/markets/cr…

88
With Democrats securing control of Congress in the 2026 midterms, the cryptocurrency industry’s hopes for a sweeping legislative breakthrough have been replaced by a reality of defensive lobbying and impending investigations. Based on recent reporting from The Hill, here is how the shifting balance of power in Washington will impact crypto policy and legislation in the upcoming 120th Congress:
Comprehensive legislation aimed at redefining crypto market structure (such as the industry-backed CLARITY Act) is now considered highly unlikely to pass. Democratic lawmakers are reportedly pivoting away from proposals that favor the CFTC, seeking instead to draft new frameworks that empower the SEC with stronger supervisory authority and stricter consumer protections.
Instead of passing new pro-crypto laws, Democratic committee leaders plan to launch aggressive oversight campaigns. This includes investigating the SEC for recently dropping various crypto enforcement actions, probing crypto companies with close business ties to President Trump, and scrutinizing political contributions within the industry. While sweeping market frameworks are effectively dead in the water, smaller, bipartisan efforts still have a chance. Industry experts note that targeted bills focusing on crypto tax legislation (such as the Digital Asset Tax Certainty Act, which advanced out of committee in September) and national security safeguards could still see movement.
Because Congress is unlikely to deliver major statutory victories, the crypto industry is being advised to adopt a "traditional, longer-term lobbying presence." Rather than expecting immediate legislative wins, the goal for the next two years is to build relationships with skeptical Democratic lawmakers, prove the industry supports a safe environment for investors, and lay the groundwork for 2028.
For the next two years, the actual implementation of US crypto policy will be dictated largely by federal regulators using their existing authority, while the crypto industry plays defense against a wave of congressional scrutiny.
You can read more from The Hill here:
claconnect.com/en/resources/…

1
122
If you are tricked into authorizing an early withdrawal from an IRA or 401(k), current federal tax law may require you to report the taxable distribution and pay the 10% additional tax, even if a scammer immediately takes the money. But the result is not automatic: unauthorized withdrawals, valid rollovers, specific statutory exceptions, and potentially deductible profit-motivated theft losses can change the analysis.
Right now, if an identity thief fraudulently drains your 401(k) or IRA, the IRS often classifies it as a taxable distribution, leaving victims with massive tax liabilities and locked into years-long payment plans for money they never received.
However, a major legislative fix is currently fighting the clock in Congress. A massive coalition of advocacy and financial groups, including the CFP Board, AARP, and SIFMA, is aggressively pushing the Senate to pass the Tax Relief for Fraud Victims Act during the lame-duck session.
Elimination of IRS Penalties
The bill completely waives the 10% early distribution penalty in cases where a retirement account was compromised by fraud.
Restoring the Theft Loss Deduction
Under current law, casualty and theft losses are restricted to federally declared disasters. This bill updates the tax code to allow taxpayers to write off fraud and scam losses (to the extent the loss exceeds 10% of their Adjusted Gross Income).
Extended Timelines & Retroactivity
Victims would have the flexibility to claim the deduction in either the year the fraud occurred or the year it was discovered. Crucially, the bill is retroactive to January 1, 2021, meaning taxpayers who previously paid taxes on stolen funds can file amended returns to claim massive refunds.
The Reality Check: The bill passed the House in September, but its fate now rests in a deeply congested Senate calendar before the new Congress takes over in January 2027.
If this legislation passes, it will trigger a wave of amended returns for victims who have been unfairly taxed on stolen wealth over the last five years.
104

Ralph Mendoza, EA retweeted
The IRS CEO just said this about 2027:
"Things that we could get to only 3% of the opportunity, we're going to get into 100."
Frank Bisignano was talking about AI. He calls it "super intelligence."
He said it should help the government collect more revenue.
Here's what that means if there's a crypto mistake on an old return.
For 2025 sales, brokers started sending the IRS Form 1099-DA.
Matching those forms against returns used to be limited by people and time.
That's exactly the kind of limit AI could remove.
Hypothetical:
You left $40,000 of short-term crypto gains off your 2025 return.
If it all lands in the 22% bracket, that's $8,800 of federal tax.
If the IRS finds it first, you can owe a 20% accuracy-related penalty on top. That's another $1,760.
Plus interest.
If you fix it first, with an amended return filed before the IRS contacts you, it's generally a "qualified amended return."
That penalty usually doesn't apply. You still owe the tax and the interest.
There are exceptions, including some IRS summonses sent to exchanges, so talk to a pro before you amend.
Same mistake. Different bill.
The only difference is who found it first.
What I'd do before year-end:
1. Pull every 1099-DA and your full exchange history for 2025.
2. Compare the proceeds to what you actually reported.
3. Find your real cost basis before you assume the worst.
4. If something's missing, amend before a letter shows up.
This is why I helped write Section 502 of H.R. 10357, a proposed low-penalty path for people who made honest crypto mistakes.
It's not law yet.
Today, a clean amended return is still the best move you have.
Would you rather fix it now, or wait to see if the IRS finds it first?
Ralph Mendoza, EA retweeted

🚨In May of 2024, I told crypto investors to take IRS AI seriously.
Some said I was fearmongering. I called it a warning.
Now IRS CEO Frank Bisignano says the agency plans aggressive use of AI in 2027.
I'm not celebrating being right. I want people prepared.
Crypto taxpayers should read the details.
Speaking on October 29th, Frank Bisignano described plans for aggressive AI use in 2027.
His priorities:
• Improve taxpayer service.
• Accelerate the agency's work.
• Increase revenue collection.
He expects work that once took five years to take one.
My takeaway: prepare for an agency trying to do more, faster.
If your crypto records contain gaps, use the time you have now to address them.
Can you explain the numbers on your crypto return?
Can you support your cost basis?
Can you produce the records behind your gains and losses?
Those questions matter more than whether you liked my warning.
Ralph Mendoza, EA retweeted
If your books aren't reconciled, your year-end tax projection is a guess. Reconcile now — while there's still time to change the answer. #Bookkeeping