
Ex hedge fund analyst. Mostly small-caps. Mostly consumer discretionary. Mostly value. Other thoughts at times. Always opinions. Never investment advice.
Joined August 2021
- Tweets3.7K
- Following51
- Followers2.9K
- Likes198

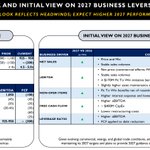


$NWL - 2027 comments:
1. Sales growth above market
2. Taking pricing early 2027 to offset add'l inflation in '26 and '27.
3. Operating margin growth of more than 50 bps above '26 levels (ex-tariff refunds)
4. Strong FCF year with deleveraging.
$NWL - seems people are overlooking the return to sales growth and focused on 2 discrete cash flow items - one is accounting related, and the other is due to less reliance on A/R factoring (no longer necessary). Short-sighted and silly.

$CPRI - guess ticker wasn't highlighted on previous post. Q3 guide is solid even with some wholesale shipments moved up into Q2. Real momentum, low P/E, massive buyback.
$CPRI- solid beat and raise. Bought back 10.3m shares at $14.56. Expect to return to sales growth the rest of this fiscal year. Guide is $2.20. Rerating imminent.
$NWL - seems people are overlooking the return to sales growth and focused on 2 discrete cash flow items - one is accounting related, and the other is due to less reliance on A/R factoring (no longer necessary). Short-sighted and silly.
$CPRI- solid beat and raise. Bought back 10.3m shares at $14.56. Expect to return to sales growth the rest of this fiscal year. Guide is $2.20. Rerating imminent.
Yesterday felt like tax loss selling/capitulation in a lot of names that I follow (a few of which I own). Will be curious to see where they are by mid-late October. One name I own that bucked the trend was $CPRI - sounded really good at GS conf yesterday and still sub 7x P/E.
$PLAY - I don't know what the plan is here. If they stop growth and just spend on maintenance/games there's still plenty of cash flow unless EBITDA margins completely crater. Wonder if you get rights offering or warrants. TBD.
$PLAY working with Moelis per Bloomberg. Should've worked with them before they bought Main Event and blew up their balance sheet on growth and buybacks. Decent trade from $6.30ish to $8 if you did it. Moving on.

$PLAY working with Moelis per Bloomberg. Should've worked with them before they bought Main Event and blew up their balance sheet on growth and buybacks. Decent trade from $6.30ish to $8 if you did it. Moving on.
$PLAY - What's the point of activist shareholders if they can't convince the board of the obvious? Maintenance/Games CAPEX is 100M a year max, which means it should be $50M through 6 months and FCF should be $110M YTD on 35 million shares. Enough already! Wake the f^&k up!

$CAKE - I wish I saw this yesterday. Would've let Dave take the incoming.

$OI - listened to the call. A lot of detail. Actually have more company specific levers to pull than I expected. Every region/sub-region has it's own story. Interesting play once tax loss selling subsides.
$VFC - Vans guided down 2% or better in 2H. DTC is already positive with wholesale swing starting in fiscal Q4 (March) and into summer of 2027. What gives them confidence? CEO - "We're looking at orders. That's what gives us the confidence."
$OI - they've cut numbers 4 times this year. So hard to believe anything about 2027 right now (even with very low bar), and perhaps a final tax loss selling flush. I'd pick $WHR over this in the crappy industrials bracket.

$CAKE - SSS were 3% in 2023, 1% in 2024, 0.1% in 2025. Historically a low single digit comp story prior to COVID due to high AUVs/wait times. Just put up traffic driven 15.2% in Q3 vs a 0.3% prior year. Mean reversion coming soon (off much higher base) to a location near you.
$CAKE - why is this thing comping 15%? It's been around for almost 50 years, the quality has gone downhill, portions have shrank, prices have gone up.
$CAKE - why is this thing comping 15%? It's been around for almost 50 years, the quality has gone downhill, portions have shrank, prices have gone up.
$OI - Europe still a mess. Americas is fine. 2027 story now (or 2028.........or never).


$WHR - if there wasn't history, I'd look at the deck - see the y/o/y margin decline much smaller in Q4 and projected margins expansion and call a bottom. Here, it's a tougher call but it honestly wouldn't surprise me.

$WHR - ugly print and guide, but decent news on FCF (probably from running inventories down). Possible estimates get so low now for Q4 and 2027, that the bottom is close. Wouldn't rule out a bounce like $NKE - but far less belief here - deservedly so.
$WHR - no position. Stock basically straight down for 2.5 months. Surge in rates hasn't helped. Steel tariffs haven't helped. Brazil election probably doesn't help. Call me an interested observer as it gets closer and closer to a binary bet.
$WHR - no position. Stock basically straight down for 2.5 months. Surge in rates hasn't helped. Steel tariffs haven't helped. Brazil election probably doesn't help. Call me an interested observer as it gets closer and closer to a binary bet.
$WHR - just listened to conf call. Given the company's recent history, take this with a grain of salt, but certainly possible the bottom is in and margins expand from here. No debt maturities until 2028.
$BHR - Even the Company's proposed board slate is missing a certain someone. Monty NOT 4 Life!!
braemar.q4ir.com/investor/ne…
$RH. Lol. $110 to $140 in a week.