

Connecting investors and vendors with top-tier metals & mining projects. Your source for top quality insights in the mining sector.
Joined January 2025
- Tweets68
- Following242
- Followers101
- Likes46


Been following Formation Metals and the work at N2 pretty closely. The scale of what’s already there, plus the room to grow with more drilling is what is going to send this flying.
My honest take: I think this turns into a 5 Moz+ deposit over the next few years. $FOMO

We keep drilling. We keep finding gold.
West, south and north of Zone A at N2: every direction tested to date has returned gold. Mapped on Québec's own geology and drillhole records.
$FOMO (OTCQB: FOMTF | FSE: VF1)


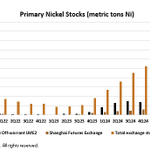
Primary nickel exchange stocks (LME including off-warrant plus Shanghai Futures Exchange) declined from roughly 300,000 metric tons in early 2021 to multi-year lows near 50,000 tons by mid-to-late 2023 before reversing sharply and climbing to around 450,000–470,000 tons by 2Q26—the largest overhang in over a decade—driven by Indonesian supply growth outpacing demand; this surplus is expected to keep inventories elevated or modestly higher through 2026–early 2027, with only gradual drawdowns likely thereafter unless battery and stainless demand accelerate significantly or Indonesian output is constrained, thereby capping near-term price upside and creating a challenging environment for nickel exploration and development companies.

After reading Canaccord's site visit note... completely agree, Hemlo is just getting started.
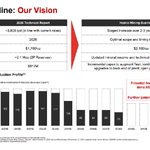
Today's ~3,800 tpd mine-limited rate is the floor, not the ceiling — the path builds toward a modeled 9,300 tpd by 2030, with permitted capacity up to 13,500 tpd. That's attributable production climbing from ~119 koz in 2026 to 200+ koz within a few years, costs falling as scale kicks in. Every upcoming catalyst — 2026 guidance, resource conversion drilling, throughput studies, the H2/2027 technical report — strips out another layer of execution risk.
As Hemlo proves out its ramp, the market should stop pricing it like an unproven junior and start pricing it like the senior, multi-decade producer it's becoming.

Altius Minerals (TSX: ALS) expects to report record Q2 2026 attributable royalty revenue of approximately $30.0 million, more than doubling from $12.7 million in Q2 2025.
The revenue mix highlights growing diversification, with base metals (primarily copper) the largest contributor followed by lithium, electricity, and potash. This performance was driven by higher realized prices/volumes, timing of Chapada deliveries, the Lithium Royalty Corp. acquisition, and renewable project ramp-ups (including Sequoia I), with further upside expected from the pending increase in GBR ownership from 29% to 50%.
It also serves as a reminder that precious metals royalty companies aren't the only ones benefitting from the current commodities bull market—though companies like Silver Crown are still among the best places to be for leveraged exposure to the precious metals upside.
Q2 2026 Revenue Breakdown for Altius:
Base metals: 31.4%
Lithium: 21.4%
Electricity: 20.2%
Potash: 16.8%
Iron ore: 5.2%
Interest and other: 4.9%
juniorminingnetwork.com/juni…

The AI-driven surge in power demand is set to ignite a major bull run for uranium equities, with more reactors coming online… Get ready… it's going to be a strong run for Uranium X and the entire Athabasca Basin 🚀🚀🚀

The new uranium buyer is the data center.
Microsoft signed a 20-year deal with Constellation to restart Three Mile Island.
Meta has signed agreements for up to 6.6 GW of nuclear.
AI needs always-on power. Nuclear delivers it.
$STMN #Uranium #Nuclear #AI
Source: Constellation Energy; World Nuclear News

We refreshed our peer analysis of gold developers and explorers. The group average now sits at approximately C$90/oz AuEq — notably lower than the prior C$234/oz when we last did this analysis— underscoring continued sector undervaluation amid strong gold prices. Several names command premiums above C$400/oz reflecting advanced assets or near-term catalysts, while a significant cohort trades in the teens to low C$100s, offering substantial leverage to exploration success, resource growth, and higher metal prices (using US$4,100/oz gold, US$65/oz silver, and US$6.00/lb copper, based on latest financials). The dispersion remains striking and highlights compelling asymmetric opportunities across the peer group.

In its Q1 2026 Gold Demand Trends report released last week, the World Gold Council highlighted continued strong central bank buying, with 244 tonnes purchased (+17% q/q and +3% y/y), valued at $38.2 billion (+38% q/q and +75% y/y). Global gold mine production fell 9% quarter-on-quarter (seasonally typical) but rose 2.4% year-over-year thanks to ramp-ups at Barrick’s Loulo-Gounkoto, Batu Hijau, and several Canadian mines; despite six straight years of record-high gold prices, annual production has grown at a sluggish 0.7% compound rate.
link: gold.org/download/file/20771…
Overall, this is structurally bullish for gold miners, primarily through sustained high gold prices and a tight supply backdrop, though the benefits are more pronounced for established producers with operational leverage than for the sector as a whole in the very short term.
Looking forward to seeing how valuations change in the coming weeks and months ahead...
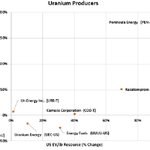
Since September 28, 2025, when we last looked at the sector, uranium producers have shown varied changes in valuation multiples.
Peninsula Energy (PEN-AU) recorded the largest increases, with P/NAV rising approximately 183% and EV/lb Resource up about 102%. Kazatomprom (KAP-LSE) also advanced, with gains of roughly 50% in P/NAV and 70% in EV/lb. Paladin Energy (PDN-AU) saw its EV/lb increase by around 110%, while its P/NAV rose more modestly. In contrast, Lotus Resources (LOT-AU) experienced declines of about 22% in EV/lb and 26% in P/NAV. Uranium Energy (UEC-US), Energy Fuels (UUUU-US), Cameco (CCO-T), and Ur-Energy (URE-T) showed mixed or relatively flat performance, with some modest EV/lb gains offset by stable or declining P/NAV.
The data indicates greater valuation expansion for companies with strong resource growth and development momentum. @PEN_Energy @Ur_Energy @Energy_Fuels @Paladin_Energy @cameconews

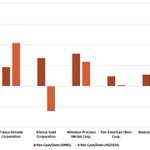
From the end of Q4 2024 to the most recent quarter (MRQ), major precious metals companies experienced a remarkable strengthening of their balance sheets, largely fueled by record-high gold prices and robust free cash flow generation.
Agnico Eagle Mines Limited delivered the most dramatic turnaround, swinging from a net debt position of $512 million to a strong net cash position of $3,489 million. Barrick Gold Corporation followed closely, improving from $1,701 million in net debt to $2,050 million in net cash, while Kinross Gold Corporation achieved a significant reversal from $1,210 million in net debt to $1,349 million in net cash. Wheaton Precious Metals maintained its position among the sector’s strongest, with net cash rising from $1,170 million to $1,571 million. Mid-tier producers such as Alamos Gold, Pan American Silver, and Franco-Nevada also posted gains or remained in solid territory (though Franco-Nevada saw a decline from a high base while staying debt-free), and IAMGOLD reduced its net debt by $693 million. Only B2Gold experienced a modest widening of its small net debt position.
Overall, these substantial changes highlight disciplined capital allocation, aggressive debt repayment, and cash accumulation across the sector, significantly enhancing financial resilience and flexibility for future dividends, share buybacks, and growth opportunities.

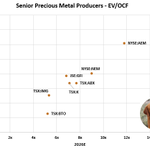
In early 2026, with gold trading near record levels, major gold miners trade at attractive forward EV/CF multiples, mostly between 7x and 9x on 2027E cash flow. B2Gold (BTO) stands out as the cheapest at just 3x in 2027E (down 50%), signaling strong expected cash flow growth. Mid-tiers like IMG and Kinross also look discounted at 5–7x, while seniors NEM and ABX sit at 7–8x. Premium names AEM (12x) and Fresnillo (14–15x) trade at the higher end. Overall, modest multiple compression reflects robust cash flow growth ahead, making the sector appear reasonably valued with BTO offering the most compelling value.

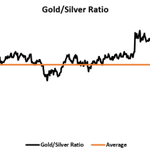
The gold/silver ratio currently stands at approximately 64.8, well below its 3-year average of around 83. This lower reading indicates that silver is outperforming gold on a relative basis, reflecting stronger industrial demand for silver (from solar, EVs, and electronics) and a maturing precious metals bull market where silver often accelerates in the later stages. For junior miners on the GDXJ, this setup is generally positive, as many miners carry significant silver exposure and tend to see leveraged gains when the ratio compresses.

We analyzed a dataset of 21 gold developers and explorers, focusing on their relative enterprise value (EV) per ounce in Canadian dollars. The average across the group came in at C$234/oz.
Formation Metals (CSE:FOMO), by contrast, boasts an EV of roughly C$25 million, with a historic resource of 855,000 ounces. The company plans to drill 30,000 meters to further validate the N2 Project and highlight its upside potential for a 3.0-million-ounce deposit...
Crunch the numbers and see for yourself how undervalued this truly is...

Our dataset of 30 base metal stocks (TSX, ASX, LSE, TSXV) are mostly trading closer to their 52-week highs than lows. On average, they need +32% to reach highs and -64% to hit lows. Compared to when we did this analysis in September last year (+17.5% to highs, -51.8% to lows), the sector has pulled back moderately but remains positioned toward the upper end of its recent range.

On February 23, we reviewed YoY P/NAV valuation changes for GDXJ’s top ten publicly traded holdings. On an equal-weighted basis (via our proxy), the average multiple has expanded to 1.29x from 0.79x versus the same time last year.

Considering all gold deposits in Quebec and Ontario listed on the TSX or TSXV that exceed 600 koz of gold (excluding major outliers), the average metrics per deposit are 69 million tonnes at 2.99 grams per tonne of gold for 3.4 million ounces.
Assets included in this analysis: Golden Rose (TSXV:CQR), Whitney (TSX:PAAS), Lingman Lake (TSXV:SGU), Sakami (TSX:FURY), Elmer (TSXV:AZM), Coldstream (TSX:WDO), Hasaga (TSX:EQX), Eagle River (TSX:WDO), Granada (TSXV:GGM), Eastmain (TSXV:BZ), Cameron (TSX:FF), Gold River (TSX:PAAS), Kiena (TSX:WDO), Detour Gold Trend (TSX:WM), Larder Lake (TSX:PAAS), Galloway (TSXV:FKM), O'Brien (TSXV:RDS), Hosco (TSX:ORE), West Cache (TSXV:GGO), Wawa (TSXV:RPX), Timmins (TSX:PAAS), Clearwater (TSX:FURY), Philibert (TSX:IMG), Madsen (TSXV:WRLG), Musselwhite (TSX:OLA), Perron (TSXV:AMX), Casa Berardi (TSX:ORE), Goliath (TSXV:NEXG), Cheechoo (TSXV:SOI), Douay JV (TSXV:MGM), Chimo (TSXV:ECR), Rainy River (TSX:NGD), Hemlo (TSX:ABX), Fenelon (TSX:WM), Young-Davidson (TSX:AGI), Lamaque (TSX:ELD), Fenn-Gib (TSXV:MFG), Springpole (TSX:FF), Horne 5 (TSXV:FPC), Duparquet (TSX:FF), Great Bear (TSX:K), Moss Lake (TSXV:AUXX), Nelligan (TSX:IMG), Porcupine (TSX:DSV), Tower (TSX:STLR), Island (TSX:AGI), and Greenstone (TSX:EQX)
