

https://nitter.gq/t.co/q72Ma5ILbq Not financial advice.
Orlando, FL
Joined April 2009
- Tweets1K
- Following1.1K
- Followers1.3K
- Likes2K




Pinned Tweet
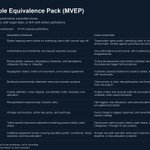
A margin call triggers at 2am Saturday. The tokenized Treasury posts as collateral instantly. Liquidating it to cash is a different problem. The redemption pool may be depleted. The secondary market may have no active makers at 2am. The fund administrator does not process redemptions until Monday. MVEP v2.0 is the diligence framework for this problem. Ten categories, each with required evidence and a pass condition. Reverse-engineered from SVB, stress-tested against seven scenarios. Updated paper on SSRN, updated article on Medium. #Tokenization

Open access, no paywall: frontiersin.org/journals/blo…

If you measure holder or governance concentration, the method and every one of the 133 exclusions are public. Check my calls, or run the same exclusion on your own data.
Auditing Governance Concentration Beyond Token Allocation, open access. Link in the reply.
Clean up the holder list and you still have not measured the vote.
Where governance runs on delegation, voting power concentrates above holdings in 13 of 18 protocols: 2.5x in the mildest case, 25.6x at Polkadot.
Five disperse it by design: ENS, GMX, HNT, JUP, LPT.
The launch allocation pie chart doesn't predict decentralization.
Insider share at launch has no relationship to how concentrated a protocol is today (r = 0.09, p = 0.55, N = 50).
What tracks is how many of those insiders are still among the top holders (rho = 0.44, p = 0.005).
Raw holder lists measure custody, not control.
Staking contracts, treasuries and exchange wallets sit in the top-1,000 as if they were holders. Across 52 protocols, leaving them in overstates concentration by a median 2.3x, up to 18x.
Out now in Frontiers in Blockchain.

Crypto Zach retweeted

Before joining Borderless Capital, @CryptoZach, founder of Tokenization Systems, spent years comparing blockchain protocols, studying tokenomics, and reading whitepapers long before crypto became mainstream.
🎙️@Lindsey___I
🔗podswit.ch/p/i/e/1799063494/…
#Tokenomics #Blockchain #Crypto
Happy to share my first podcast! I explain my 10 year journey through the crypto, venture capital, and tokenization industries and what led me to founding the research and advisory firm Tokenization.Systems, earlier this year. Enjoyed the chat, Lindsey!

Most institutions assume a tokenized asset is "safe" once it clears a risk committee.
But what if the framework they're using was never built for how tokenized assets behave under stress?
On the latest Token for Your Thoughts, @CryptoZach, founder of Tokenization Systems, joins @Lindsey___I to discuss the hidden risks in tokenization and why the next phase of digital finance needs a new way of thinking.
🎧 podswit.ch/p/i/e/1799063494/…
#Tokenization #Crypto #RWA
Before 2008, rating agencies treated mortgage-backed instruments with different credit profiles as equivalent within the same tranche. Today, collateral frameworks treat tokenized Treasury products with different legal structures as equivalent within the same margin pool. Three products. Three different sets of rules. One custodian. No federal regulator supervises the boundary where they are combined. Submitted a comment to the OCC on the GENIUS Act rule explaining why that matters.
#USYC #BUIDL #BENJI #GENIUSAct #stablecoins #tokenization #OCC
13/13
Paper: papers.ssrn.com/sol3/papers.… package: github.com/Research-Publicat…
Prepared for the Fifth Conference on the International Roles of the U.S. Dollar.
Feedback especially welcome on where the gateway thesis should break.
#Stablecoins #USDC #USDT #DeFi #MonetaryPolicy #FederalReserve #CryptoRegulation #FinancialStability #GENIUSAct #CLARITYAct
12/13
None of that is visible in token-level data.
You would see USDC falling and USDT rising.
You wouldn't see Curve 3pool becoming an emergency valve, one market-maker becoming a key bridge, or Tier 1 share collapsing over a weekend.
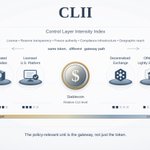
Monitoring stablecoins at the token level is like monitoring the banking system by watching cash. You see the instrument moving. You don't see which bank handled it, whether that bank was supervised, or whether the whole system depended on one clearinghouse that nobody was watching.
11/13
It is not just about stress. Chain choice is policy-relevant every day.
On Ethereum, you can see who routes most of the dollar volume.
On Tron, a large share of high-value addresses are still completely unattributed.
Same token, different chain, radically different regulatory visibility.
10/13
USDT did not depeg. It traded at a premium as flows rotated in.
And Curve 3pool, scoring 0.18 on the control index, surged to $2.3B in daily volume (12x its normal throughput) as the system's de facto emergency valve.
The stress path was not just about which token you held. It also depended on which gateways stayed open.