

Data-driven macro, oil and stock research. Earnings breakdowns, charts and deep dives. Not financial advice.
Joined October 2026
- Tweets180
- Following22
- Followers502
- Likes25





Pinned Tweet
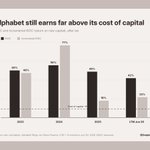
New article: how I check if a company’s CapEx pays off, using $GOOGL as the example.
ROIC is 42%. But the new money earns 20%, a third of what it did in 2024.
Link in bio.

Iceland's Blue Lagoon is going public.
The spa plans to list on Nasdaq Iceland in November, after years of volcanic eruptions next door forced it to close several times and postpone a 2022 IPO.
All 700 permanent employees will get the option to buy shares…
A tourist attraction as a public company.
I'm rotating, guys. I've had enough!


Hello?
This is nuts.
nitter.gq/AarushYadav47/status/2…

We’ve raised $1.3M from YC & Afore Capital so you never have to type or speak again.
Typing is slow. Talking into your computer is awkward. Subvocal fixes both
Our glasses give you the speed of speech without you making a sound or touching a keyboard.
It tracks your internal speech muscles with non-contact sensing and decodes silent, almost invisible mouthing into text at more than 200 words/min.
Pre-orders are now live at:
subvocal.co/preorder?utm_sou…

This is not good for $INTC
Q4 guidance: EPS $0.25 vs $0.43 expected, gross margin down to 38%.
Let’s see what they have to say on the earnings call...


$INTC down 20% after hours.
Q3 was a beat:
Revenue $16.5B, up 21%.
EPS $0.52 vs $0.40 expected.
Data center up 78% to $7.3B.
The problem is Q4 guidance. Revenue $15-16B, EPS $0.25, gross margin 38% vs 44% this quarter. Profit per share roughly halves next quarter.

You can be dead right about the business and still get absolutely crushed trading AI earnings right now. $AMZN could blow away every expectation tonight and get punished for raising capex to meet unprecedented demand. That’s how absurd this fear driven market has become. Almost any data point or management comment that can be twisted into a negative narrative becomes fuel for the fear trade regardless of context. Makes it difficult to build conviction to lever into earnings when the biggest risk isn’t the business disappointing. It’s the market’s reaction to the business succeeding. Know the market you’re trading. We’re playing with fire
$GOOGL fell 10% because CapEx passed operating cash flow. So I ran the number that actually tells you if that spending pays off: ROIC.
Alphabet earns 42% on its invested capital. The cost of that capital is about 9%. Still an excellent business.
Incremental ROIC went from 77% in 2024 to about 20% now. Each new dollar earns a third or less of what it used to.
The cloud backlog already justifies the CapEx through 2026. On my numbers, it’s 2027 that decides it.


Just wrote a full article on $MSFT and $GOOGL Q3 results.
Microsoft is near its record high. Alphabet is 28% below its own after a 10% drop, and I think the market overreacted.
I went through the filings: segments, cash flow, CapEx and the bear case. It’s on my Substack.
nitter.gq/DelphisLens/status/211…

Microsoft and Alphabet reported yesterday night.
Microsoft: Azure +48%, backlog up 73% to $677B, positive free cash flow. Stock near its record.
Alphabet: Google Cloud more than doubled, but CapEx was bigger than cash flow, buybacks went to zero and it issued $29B of debt in one quarter. Stock −10%, 28% below its record.
I went through both filings. I think the market overreacted on Alphabet, and I explain why in my new piece on Substack. $GOOGL $MSFT


$NOW had a decent quarter and the stock fell about 17% after hours.
Subscription revenue grew 21% to $3.99B, the operating margin was 32.5% and they raised their AI contract target to $1.7B.
The problem is the outlook. Contracted revenue for the next 12 months (cRPO) grew 20.5% this quarter, and they guide only 18.5% for next quarter.
Also gonna be looking close in the filings, after dropping almost 20% after close, it's worth watching what happened to identify if this could be a great opportunity.
I like Software businesses.
$GOOGL revenue came in line, and the stock still fell around 10% after hours.
Google Cloud more than doubled to $30.7B. Search grew 12% and YouTube ads 9%.
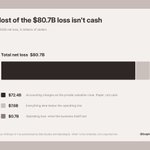
EPS was $2.12 vs $3.02 expected. $0.55 of that gap is an $8.7B paper loss on equity stakes, not the business.
What I think worried people is the spending. Capex was $51.4B in one quarter, free cash flow was −$9.1B, and they said CapEx will rise “significantly” in 2027.
Will definitely have to dive further into Alphabet.