

Custom-fit infrastructure for neobanks, wallets, and fintech products. One platform. Fully modular. Built by fintech veterans.
Joined September 2025
- Tweets51
- Following20
- Followers449
- Likes4




Pinned Tweet
Big milestone for @FinHarbor 🎉
We’re proud to share that we have completed the core deployment of a hybrid #neobank platform for #Asterium in #Uzbekistan — designed to support both traditional banking services and digital asset operations within a single compliant environment.
Read the full article here 👇
apnews.com/press-release/glo…
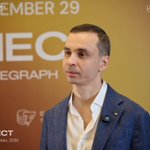
At #CONNECT by @Cointelegraph: Seoul Edition, @FinHarbor joined the conversation around one of the most important shifts in corporate #crypto adoption: digital assets moving from a pure investment thesis into treasury strategy and balance-sheet management.
Our Co-Founder and CEO, Ilya Podoynitsyn, took part in the panel “The Treasury Revolution: Public Companies, Crypto Balance Sheets, and the New Reserve Asset Playbook” alongside leaders from @Sharplink, @RockawayX, and @PanteraCapital.
The discussion went beyond the question of whether companies should hold #Bitcoin. The more difficult questions are operational: how to manage liquidity and risk, how treasury processes change once on-chain activity is introduced, and what infrastructure companies need to operate safely across traditional finance and digital assets. For us, that is where much of the real work begins.
Thank you to @Cointelegraph and the #CONNECT team for bringing together such a strong group of speakers and participants in Seoul. A few moments from the event below.
#CONNECT #Cointelegraph #KoreaBlockchainWeek #KBW2026 #FinHarbor


KBW2026 gave us a useful view of where the conversation in #crypto is moving. A few years ago, much of the industry was focused on how quickly a product could be launched. Today, more of the discussion is about what happens around the product: treasury controls, security, compliance, operational processes, and the infrastructure required to scale safely. That shift matters.
For FinHarbor, these are exactly the problems we work with every day — connecting traditional financial operations with crypto infrastructure, and helping businesses build products where technology, operations and regulatory requirements work together rather than as separate layers.
Our Co-Founder & CEO, Ilya Podoynitsyn, also joined #CONNECT by @Cointelegraph: Seoul Edition, where the conversation touched on operational maturity, regulatory change, and what companies need to consider before scaling crypto products.
Thank you to everyone we met in Seoul, and to the teams behind #KBW2026 and CONNECT for bringing so much of the industry together in one place. See you at the next one.
#KoreaBlockchainWeek #KBW2026 #FinHarbor #Fintech #Crypto #DigitalAssets #Web3 #FinancialInfrastructure

Building a hybrid #fiat #crypto product should not require stitching together multiple vendors across banking, exchange infrastructure, compliance, and treasury.
That fragmented model slows teams down, adds operational complexity, and makes scaling harder than it should be.
At @FinHarbor, we have repackaged our Hybrid #Neobank Module into a unified infrastructure stack that combines regulated fiat banking, a full-featured centralized exchange, and embedded compliance in one deployable system.
The result is a more streamlined path for operators launching crypto-native financial products with fewer integration bottlenecks and a stronger foundation for growth.
Read more in the article below 👇
globenewswire.com/news-relea…
Launching a #neobank is still too slow, too costly, and too fragmented.
That’s exactly the problem FinHarbor is solving with its latest platform update: bringing #IBAN accounts, card issuing, payments, and crypto-fiat exchange into one orchestrated infrastructure stack designed for faster deployment and lower operational complexity.
A recent client went live in just 28 days — a strong example of what becomes possible when infrastructure is built to operate as one system, not as a patchwork of disconnected providers.
Read more in our article 👇
markets.businessinsider.com/…

An OTC desk isn’t just “buying and selling large volumes of crypto.” It’s a full operating system where liquidity, pricing, settlement, and compliance all have to work together in real time.
From the outside, OTC can look simple.
Inside, it’s a tightly connected process where multiple functions are running at once — and each one affects the others.
Here’s what that actually looks like in practice:
1. Liquidity sourcing and risk management
An OTC desk works across multiple liquidity providers, venues, currencies, and time zones.
It’s not just about matching buyers and sellers. It’s about managing inventory, balancing exposure, and making sure positions can actually be covered when markets move.
2. Pricing logic and margin control
OTC pricing is never just “market price plus a fee.”
Quotes depend on trade size, counterparty profile, relationship context, and current exposure. That means pricing engines need live market data, configurable spreads, and the ability to adjust instantly.
3. Settlement and reconciliation
Fiat may settle via SWIFT or SEPA, while crypto settles on-chain. Large trades often settle on T+1 or T+2 timelines, which creates a coordination problem: both sides of the trade have to stay aligned while funds, timing, and counterparty risk are managed across different rails.
4. Compliance and transaction monitoring
High-value trades require more than basic checks.
KYC tiers determine limits. AML systems monitor unusual patterns. Every transaction needs a full audit trail from quote to settlement. In OTC, compliance isn’t a layer added afterward — it’s part of the core workflow.
5. Operational visibility
Running an OTC desk requires a real-time view of everything: P&L, exposure, settlement status, risk limits, compliance alerts, and client activity. Without that visibility, scaling the desk becomes guesswork.
On FinHarbor’s platform, these components run through the same infrastructure: the same compliance engine, the same reporting layer, and the same audit logic.
Whether it’s a $100 retail transaction or a $10M institutional OTC trade, the underlying risk and compliance framework stays consistent.
The difference between an OTC feature and an OTC desk is operational depth.
One can process trades. The other can support a real business.

Speed matters. But in financial infrastructure, speed without flexibility creates long-term drag. What looks like an efficient launch model at day one can turn into a constraint on product development, compliance, scalability, and expansion just a few months later.
In this article, I share my perspective for @hackernoon on why modular architecture is redefining how #neobanks and #fintech products should be built in 2026 and beyond 👇
hackernoon.com/modular-finan…

⚡️By 2027, traditional #banks won’t exist as we know them ⚡️ Not because of #crypto. Not because of fintech. Because enterprises will bypass them entirely using #stablecoin rails. $4 trillion will move without touching a single bank. And nobody sees it coming.

API-first isn't a buzzword. It's an architectural decision, one that compounds over years — for better or worse.
Most integration delays aren't technical problems. They're documentation versioning problems, consistency problems. API-first solves all three.
In fintech, integrations aren't just features — they're the foundation of your business model. When compliance providers, card processors, and banking partners all need to connect seamlessly, your API design becomes your competitive advantage.
Here's what API-first actually means in practice:
1. Design before implementation.
API contracts come first, code second. This forces clear thinking and versioning before you write a single line of code, accelerating everything downstream.
2. Documentation as a first-class citizen.
Open API specs aren't generated from code — they are the specification. With code examples and sandbox environments. If your partner can't integrate with your API using your interactive docs, your integration will fail.
3. Consistent patterns across all endpoints.
The same authentication model for all services. Predictable error codes. Standardized pagination. When developers learn one endpoint, they understand your entire system.
4. Versioning strategy from day one.
Breaking changes happen. API-first means planning for them. Semantic versioning, deprecation timelines, backward compatibility. Your partners shouldn't fear your updates.
At FinHarbor, this translates into concrete infrastructure: gRPC for internal services (type safety, performance), REST for external integrations (compatibility, tooling), and a comprehensive webhook system for real-time events.
The result? Partners integrate in days, not weeks. New features ship without breaking existing flows. Developer experience accelerates product velocity.
In fintech, API quality directly impacts your business relationships. Poor API design costs partnerships. Great API design builds ecosystems.
What's been your experience with API-first architecture? Where does it actually matter?

Building a #crypto wallet? 💰
The user sees one app. Behind it: onboarding, ramps, compliance, monitoring. Here’s how it all connects when everything lives on one platform.
Most crypto wallet projects underestimate what happens after the user creates an account. Here’s the full picture — the complete user journey from signup to daily operations:
1️⃣ Onboarding: Set the Foundation
#KYC verification with configurable risk tiers, automated sanctions screening, wallet generation with proper key management. Not just “create account” — establish the compliance and security framework that protects every future transaction.
2️⃣ Deposit: Multiple On-Ramps
Fiat ramp-in via #SEPA/card payments, direct crypto deposits with real-time blockchain confirmations, automatic currency conversion at competitive rates. Users expect both traditional and crypto funding — no reason to force them to choose.
3️⃣ Usage: Daily Operations
Send/receive across 20+ #cryptocurrencies, swap between assets with transparent fee structure, card payments (virtual and physical) when integrated. The wallet becomes their financial hub — not just #crypto storage.
4️⃣ Compliance: Continuous Monitoring
Real-time transaction monitoring for #AML compliance, automated alerts for suspicious patterns, integration with sanctions lists updates. This isn’t post-processing — it’s real-time protection that doesn’t slow down user experience.
5️⃣ Support: Complete Audit Trail
Full transaction history for disputes, user activity logs for support queries, compliance reports for auditors. When something goes wrong (and it will), you have the data to resolve it quickly.
At FinHarbor, we see teams trying to stitch together 8–10 different providers to cover these flows. The result? Data inconsistencies, compliance gaps, and integration maintenance that never ends.
One platform handles the entire journey — from user signup to regulatory reporting. That’s the difference between building a feature and building a business.
#Crypto #Wallet #Fintech #Compliance #Infrastructure #FinHarbor

💭 Vendor lock-in isn't just inconvenient — it's expensive in ways you don't see until it's too late.
You picked a platform to move fast. Launch in Q2, worry about the rest later. A year later, you can't leave — even when the platform no longer fits your business.
We've seen this pattern with fintech founders across #EU and #MENA. The real cost isn't the migration itself. It's everything you can't do while you're stuck.
1. Technical debt accumulates faster than you think.
Custom workarounds for missing features. hashtag#API calls that cost more than they should. Data exports that don't exist. Each compromise becomes permanent infrastructure.
2. Compliance gaps emerge when regulations change.
Your platform supports #MiCA, but not the local requirements in your new market. Now you're building compliance on top of compliance, instead of updating core logic.
3. Product decisions get dictated by vendor roadmaps.
Want crypto custody? Wait 6 months for their implementation. Need specific #KYC flows? Use their format or build your own layer. Your feature velocity becomes their feature velocity.
4. Data ownership becomes a legal nightmare.
Customer data, transaction history, audit logs — all in formats you can't easily export. Migration isn't just technical, it's regulatory and operational.
5. Pricing scales with their model, not yours.
Per-transaction fees made sense at 1k users. At 100k users, you're paying for their inefficiencies, not your growth.
In our experience, the companies that scale sustainably think about vendor relationships from day one. Modular architecture, API ownership, data portability — these aren't technical details. They're business insurance.
👇The questions worth asking before choosing any platform:
- Can I export all my data in standard formats?
- Do I own my customer relationships?
- Can I replace individual components without starting over?
What's your experience with platform dependencies? 🫶
#Fintech #VendorLockIn #Infrastructure #Founders #FinHarbor #StartupStrat

Most #fintech products still aren’t hard to build because of innovation. They’re hard because of infrastructure.
Stitching together 10+ providers, reconciling data across systems, patching compliance at the very end — this is still the default setup for many banks and fintech teams. It slows launches, increases costs, and creates fragile systems that are painful to scale.

We put together a short overview of how a modular financial infrastructure changes that logic — from onboarding and compliance to wallets, cards, payments, and back office.
We explain why “integrate everything yourself” is the wrong starting point, how modular architecture reduces vendor lock-in, and how teams can launch faster without compromising compliance.


From this year to the next — we’re carrying the same mindset forward: build what lasts.
2025 was a year of real work. The kind that doesn’t always look dramatic from the outside, but makes all the difference inside a fintech product: tightening processes, strengthening security, improving reliability, and making the platform more scalable, step by step, release by release.
At FinHarbor, we spent this year doing exactly that: building financial infrastructure that can support serious growth. Across the stack — from custody and crypto/fiat rails to processing and card programs — our focus stayed the same: create a platform that’s stable under pressure, flexible in new markets, and ready for the complexity that comes with scale.
What makes this journey meaningful isn’t just the product, it’s the people around it.
To our partners and clients: thank you for trusting us with important things. For the challenging questions, the high standards, and the collaboration that pushes the work forward.
To our team: thank you for the discipline, the precision, and the quiet endurance it takes to build infrastructure — the part of fintech that has to work every day, not just on launch day.
As we close the year, we’re grateful, and we’re excited. The next year will bring new rails, new integrations, and new challenges. And we’re ready for it.
Wishing you a warm holiday season, a peaceful reset, and a strong, focused start to the year ahead ✨
From all of us at FinHarbor, Happy Holidays and Happy New Year! 🎄🥂
