

Floor trader → ran derivatives desks → 25+ yrs in options. LTCM, Dotcom, 08, Flash Crash, Volmageddon...
Earth → SPX 0DTE
Joined March 2026
- Tweets2.6K
- Following587
- Followers2K
- Likes3.9K




Pinned Tweet
$SPX 0dtes - Full guide below 🧵 in the tread
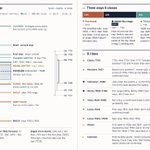
A lot of you asked how to actually read the daily card - how to use it and lean on it intraday, not just look at it. So I made a little guide.
It goes through the card block by block, with the Sep 11 SPX card as the example, then grades it against how Friday really printed.
Keep in mind -what's on the card is maybe a tenth of what goes into it. Every level sits on a real engine running behind the scenes - hours go into each one. And this part stays with me...
Implied moves, GEX and walls are the surface everyone's marketing now. This runs on a lot more.
Read the map. Trade the edges.
xitter.cf/GammaGirlLab/status/20…

$SPX Fri 9/11 0DTE: negative gamma, no pin, coiled under a stacked ceiling - 7684 flip into the 7700 wall. Personally leaning upside into CPI, but it's all on the number. Clear 7684/7700 and it calms; lose 7550 and the air pocket to 7500 opens. Fat tail's still down if the print runs hot.


$SPX Oct 27 0dte
Tue: open looks like ~7690, just under the 7697 switch.
Cap 7700-7705, floor 7645-7650.
Above 7697, rallies get sold into.
Lose 7645 and the first stop is 7631, then 7625 and 7600.


Gamma Lab Girl 🧪 retweeted

What Sunday morning looks like after a one-night stand with a European man:
German - windows open at 7:42am, starts recycling the bottles
Dutch - sends you a €6.80 request for half the condoms and the Uber
Italian - his mother and fiancee already called twice
Spanish - neither of you has slept yet
Polish - give you a vodka shot and explains why Black people are the worst to be around
French - smokes naked by the window, acts offended you're still there
$SPX Oct 26 0dte
Monday odds: range 7596-7673 40%, break below 40%, up 20%.
Down is the heavier side: a 1% drop forces about 3.6x the flow of a 1% rally.
The 7595 floor is the line.


Gamma Lab Girl 🧪 retweeted

Thoughts around AI
1) Given AI is the largest technology revolution in history at roughly 3.5% of GPD (larger than electrification, highways & internet combined); there is overinvestment due to the potential rewards for the eventual winners.
2) But much like during the Internet buildout, which had several large drawdowns including in 1997 (Asian currency crisis) and 1998 (Russian bond default), and then ripped higher, the question is whether this is THE TOP.
3) AI had 3 separate investment waves: training, inference and now Agentic
a. Agentic demands 10-100x more tokens than inference and started with OpenClaw in January for the tech savvy followed by Muse in late September for the rest of us.
4) Currently, the market is repricing two things
a. Financing costs are higher in both debt & equity mkts
i. Debt- $CRWV unsecured debt trading at 15%
ii. Equity- expected timing for AI related IPOs like OpenAI, Anthropic delayed earlier this year while filed IPOs of Firmus, AirTrunk, NScale, SB Energy delayed/ pulled
iii. Meta 8K “timing is important to secure capital before competitors saturate various funding options… in an increasingly challenging environment for raising capital.”
b. AI native growth rates slowing
i. Anthropic revs 145% q/q in Q2 to 45% in Q3
ii. Openweight driving ASPs down ~50% since May
5) Datacenter moratoriums seem to be the only thing both parties agree on
a. This could get worse after the mid-terms with a less AI-friendly political climate
In summary, because of the advent of Agentic, I do not believe this is THE TOP. But having higher cash levels and being circumspect as the market reprices has been important. This has been my advice for the past several weeks.
Unfortunately, my belief that it was time to start putting money to work for at least a short-term rally this past week due to oversold conditions in areas like semiconductors has been early so far. The SOX was down 3.2% last week vs the S&P down 0.5% but time will tell.
$MSFT $AMZN $GOOGL earnings this upcoming wk
1) I think much like with $Meta earnings this past week where I previewed concerns, the stock reactions for the above three will have a lot more to do with their comments around future capex investments, expenses, cash flow and financing needs.
2) I worry whether a datacenter moratorium causes an issue with cloud growth guidance for the December quarter despite very strong growth in the September quarter. NextDC in Australia cut their rev guide by 22% for CY27 due to local community pushback and the stock was hit for 39% last week.
Microsoft seems committed to being cash flow positive and I see them being an ultimate winner in enterprise AI. 1. They provide a safe environment to run Co-Pilot AI applications given almost all S&P companies run M365 already. Co-Pilot seats were 30M+ in the June quarter up from 20M+ in March and 15M in December.
2. One potential risk is their high margin PC business being impacted by the large declines being caused by surging memory prices.
3. Azure expectations vs their guidance of 45% y/y for September vs 43% in June have also picked up given the share gains being seen by OpenAI against Anthropic recently in enterprise.
Google should see accelerating cloud growth & be an ultimate winner in consumer AI through their Android distribution on smartphones. My short-term concerns are the following:
1. Cash flow was negative for the first time since being a public company in the June quarter.
2. A slight miss in search revs in the June quarter raise concerns around AI Agents not looking at ads.
3. More aggressive analysts expect GCP growth of ~100% y/y for CQ3 y/y (but this includes TPU sales) up from 82% in CQ2 and 63% in Q1. This is more than double the growth rate expected for AWS and Azure so I worry that these datacenter moratoriums may on the margin impact the revenue growth possible at GCP.
4. Google needs to get out their consumer Agentic AI product. This should be a catalyst for their stock given it should integrate with the 14 Google products that have over 1B users each.
Amazon should benefit from physical AI improving efficiency in their heavy asset e-commerce business.
1. I also think their e-commerce demand is solid as shown by them hiring more seasonal workers (+20% y/y) for the first time since 2023.
2. But as the biggest public cloud vendor and the one with the most capex, could they be too big to escape the data-center moratorium impact on their December quarter? As an example, Amazon last week abandoned its plans for a large 4 building datacenter in Loudoun County Virginia which has been dubbed "Data Center Alley." AWS grew 28% in Q1 an accelerated to 37% in Q2 with no formal guidance but hopes for a slight acceleration in Q3.
3. However, Amazon reports on Thursday so their AWS expectations will be reset by whatever results are from Microsoft Azure and Google GCP on Wednesday.
Best of luck in the week ahead.


👀

Pretty much.
As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.
SpaceX closed $40B of debt for GPUs, but we’re investment grade and have Starlink & launch revenue.
That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.


Gamma Lab Girl 🧪 retweeted
Great read, obvious that most of the data supporting this has not been shared on the blog, but who gives this much away for free anyway?

THE PERKINI REPORT: THE 2028 REALITY CRISIS
What if the most obvious financial bubble in all of history turns out to be.... a bubble... and what if that is just really.... bearish?
there were signs, there are always signs 🤣
free link:
hub.tslombard.com/the-perkin…
inspired by @citrini
