





Things your economy can get away with:
✅ An imbecile as a president.
✅ Government shutdowns.
✅ Cutting government spending by 80%.
Things that will kill your economy within a decade:
❌ Open borders + Welfare
❌ Overtaxing productive citizens while subsidizing the unproductive.
❌ Price controls
❌ Bureaucratic overreach.
John Cowperthwaite did more for human prosperity than any development economist drawing a government salary ever managed, and he did it by refusing to do almost anything at all.
As Hong Kong's Financial Secretary from 1961 to 1971, Cowperthwaite ran one of the most radically free economies the modern world has ever seen. He kept taxes flat and low (the top income tax rate sat at 15%), ran consistent budget surpluses, abolished import tariffs, and blocked nearly every subsidy request that crossed his desk. When British civil servants demanded economic statistics to justify intervention, he refused to collect them. Not out of laziness. He genuinely believed that giving planners numbers gave them excuses.
The results? In 1960, Hong Kong's per capita income stood at roughly 28% of Britain's. By 1997, Hong Kong had surpassed Britain. That trajectory happened without natural resources, without foreign aid, and without a single five-year plan drafted by well-intentioned economists from Oxford. Hong Kong had a harbor, people willing to work, and a bureaucrat with enough intellectual discipline to keep the state out of their way.
Capital flows toward secure property rights and reliable rules, and flees the moment politicians start allocating it. Every industry Beijing picked as a "priority sector" during those same decades burned through subsidies and produced junk. Hong Kong's industries emerged organically, serving real demand, building real wealth.
You benefit from this history whether you know it or not, because Hong Kong's success gave the world a controlled experiment that still embarrasses every advocate of managed development. The control group thrived. The planned economies didn't.
Cowperthwaite retired to St Andrews, received a knighthood, and gave almost no interviews. That restraint was entirely in character.


An offshore bank that also holds your Bitcoin.
Xapo lets me borrow against my BTC, swap to USD, buy stocks and pay with a card, and I have a private banker. A tad expensive, but worth every sat.
Get USD 500 in BTC when signing up with my link:
application.xapobank.com/mem…
🤝 Paid partnership

Capital flows where it is treated best.
California is driving away rich, productive people and attracting poor, unproductive people. Don't act surprised when it is a wasteland 15 years from now. Change happens surprisingly quickly.

Every mainstream economist, NGO bureaucrat, and State Department analyst predicted Nayib Bukele would detonate El Salvador's economy. He did the opposite.
When Bukele declared Bitcoin legal tender in September 2021, the IMF warned of "macroeconomic instability." Bloomberg ran pieces about imminent fiscal collapse. Moody's downgraded Salvadoran debt. The consensus was uniform: this was a reckless stunt by a millennial authoritarian who had watched too many crypto YouTube videos.
What actually happened? By early 2024, El Salvador struck a $1.4 billion deal with the IMF, negotiated from a position of genuine fiscal improvement rather than desperation. The country's GDP grew 3.5% in 2023. Tourism revenue hit record numbers, with arrivals up roughly 95% from pre-Bukele baseline figures. Bond prices, which markets had priced for default, recovered sharply.
The security transformation is where the predictions aged worst. El Salvador held the highest homicide rate on earth for years, running above 100 murders per 100,000 residents in 2015. Bukele's crackdown brought that figure below 2 per 100,000 by 2023, a number that competes favorably with most Western European cities. The same analysts who called his economic policies reckless called his security policies fascist. Salvadorans who previously couldn't walk to a corner store without facing gang extortion now experience ordinary life.
Property rights and personal security are not soft political preferences. They are the foundation that makes voluntary exchange possible. Capital flows toward you when you can enforce a contract without paying a gang for permission first.
Bukele is no libertarian. His consolidation of institutional power deserves criticism from anyone serious about checks on state authority. But the mainstream's specific, quantified predictions failed categorically. Stability didn't collapse. Investors didn't flee permanently. Citizens didn't starve.
The lesson is simple: crack down on criminals and enforce property rights, but, incredibly, the mainstream still refuses to learn it.

Top 5 Socialist sociopaths:
Socialism destroys wealth systematically, and the leaders who implement it deserve to be judged not merely by their body counts but by the full scope of their economic vandalism and the machinery they build to sustain it.
1. Mao Zedong earns the top position without argument. His Great Leap Forward collectivized 500 million farmers, abolished private farming by 1958, and replaced price signals with production quotas set by party cadres who had never grown a crop. Steel output targets sent peasants melting their own tools in backyard furnaces while grain rotted unharvested. The economy contracted by 30 percent between 1959 and 1961. Mao knew the numbers and continued the policy anyway.
2. Fidel Castro ran Cuba for 49 years and handed his brother a country that still rations cooking oil. Before 1959, Cuba had a higher per capita income than much of Southern Europe. Castro nationalized 166 American businesses in 1960, then dismantled the domestic private sector entirely by 1968 during his "Revolutionary Offensive." Sugar, the one export Cuba could sell, averaged production below 1950 levels through the 1990s. Central planners cannot replicate what price signals do for free.
3. Hugo Chavez inherited a functional oil-exporting economy in Venezuela in 1999 and used oil revenue to paper over nationalization after nationalization, seizing more than 1,200 companies between 2002 and 2012. When oil prices fell after 2014, Venezuelan grocery store shelves were empty because Chavez and then Maduro had already killed domestic food production with price controls and land seizures. The people started eating zoo animals. Inflation hit 1,000,000 percent by 2018. Three million Venezuelans fled by 2019.
4. Nicolae Ceaușescu ran Romania with a particular brand of cruelty that deserves more attention than it gets. He repaid foreign debt by exporting virtually all Romanian food production through the 1980s, leaving Romanians with 1,500 calories per day while the Securitate secret police maintained one informant for every 43 citizens. The Danube-Black Sea Canal, built on political prisoner labor and costing billions, moved almost no commercially significant cargo.
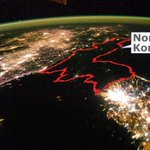
4. Kim Il-sung built the definitive socialist laboratory in North Korea after 1948, and the results are legible from space. The Korean peninsula is one country split by an ideology, and the satellite image of darkness above the 38th parallel is the most damning economic graphic socialism has ever produced. Agricultural collectivization through the 1950s and 1960s created famine conditions that recur because the system has no mechanism to respond to scarcity except political denial.
Each of these leaders shared one commitment: they all destroyed the price system. Prices tell you what people actually value, and that information was politically inconvenient.

This comes to show that even in South Africa, the man on the street still sometimes has influence.
Well done to everyone who made themselves heard about this insane and draconian proposal.
Hat tip to @PRDG_ZA for doing excellent work on this topic.
We live to fight them another day.

BREAKING | Treasury backs down on crypto rules after ‘thousands’ of comments techcentral.co.za/treasury-c…

The US presidency is the most dangerous office in the world.
Here are the top 3 best and worst presidents ever:
Let's start with the best:
1. Grover Cleveland vetoed 414 bills in his first term alone, including congressional handouts to drought-stricken Texas farmers in 1887, on the grounds that the Constitution authorized no such charity. He was right.
2. Warren Harding inherited the sharp 1920-21 depression and did almost nothing, cutting federal spending from $6.4 billion to $3.3 billion and slashing tax rates. The economy recovered within eighteen months, precisely because Washington stepped aside.
3. John Tyler, largely forgotten today, vetoed a national bank bill twice, endured expulsion from the Whig Party, and refused to let Henry Clay transform the Treasury into a political instrument.
These three men share a rare quality: they treated the federal government as a cage, not a tool.
Now the worst.
3. Abraham Lincoln suspended habeas corpus, imprisoned 14,000 political opponents without trial, shut down opposition newspapers, and conscripted men at gunpoint. The war's financing required the Legal Tender Acts of 1862, which forced irredeemable paper greenbacks on US citizens regardless of what contracts previously specified. Centralization of federal power over the states never fully reversed after 1865. The constitutional republic that emerged was a different animal from the one that entered.
2. Woodrow Wilson delivered the Federal Reserve in 1913, the income tax through the Sixteenth Amendment, the military draft, and the Espionage Act, which could imprison anyone for criticizing the war. He segregated the federal civil service. He took the country into a European slaughter with a propaganda apparatus, the Committee on Public Information, designed to manufacture consent. Every major expansion of state power in the twentieth century traces a direct line back to Wilson's two terms.
1. Franklin Roosevelt gets the top prize for catastrophe. He criminalized gold ownership via Executive Order 6102 in 1933, forcing Americans to surrender their gold at $20.67 per ounce, then immediately revalued it to $35, confiscating roughly 41 percent of savings held in the hardest monetary form available. He extended a cyclical recession into a decade-long depression through the National Industrial Recovery Act, agricultural price controls, and relentless uncertainty about property rights. Businesses do not invest when the rules change by executive whim every quarter. Real unemployment never fell below 14 percent throughout the 1930s. He packed the Supreme Court when it resisted. The regulatory state you live inside today, with its 188,000 pages of federal rules, grew from seeds Roosevelt planted between 1933 and 1945.
Power corrupts budgets, currencies, and constitutions with equal efficiency. The best presidents understood their job was to leave you alone.

In September 2008, the Federal Reserve and Treasury ran a rescue operation. AIG, Goldman Sachs, Deutsche Bank, and Société Générale were the beneficiaries. You were the source of funds.
Here is how the mechanism worked. AIG had written credit default swaps guaranteeing hundreds of billions in mortgage-backed securities. When those securities collapsed, AIG owed its counterparties full par value. The government injected $182 billion across multiple tranches, and AIG's counterparties collected 100 cents on the dollar. Goldman alone received $12.9 billion. No haircuts. No negotiations. Full payment, funded by you.
Treasury Secretary Hank Paulson, a former Goldman CEO, made this call. The conflict of interest practically announces itself.
Free market economists recognize that bankruptcy exists precisely for this moment. AIG's assets, subsidiaries, and insurance policies would have survived Chapter 11 reorganization. Policyholders carry legal protections under state insurance law regardless of the parent company's solvency. The "systemic collapse" narrative was a performance, staged to justify socializing losses that sophisticated institutional investors should have absorbed themselves.
When counterparties realize the government will guarantee their riskiest bets at full value, they price that guarantee into every future transaction. Risk calculation collapses. Banks take larger positions than the underlying economics justify because the downside belongs to you.
You did not write those credit default swap contracts, you did not collect the premiums, you did not sit on AIG's board approving the exposure.
You simply received the invoice, laundered through Treasury debt and Federal Reserve money creation, inflating away purchasing power you will never recover.

Central planning doesn't fail because planners are stupid, but because planners are blind.
Soviet factory managers faced a simple incentive structure: hit your quota, keep your job, possibly keep your life. The State Planning Committee (Gosplan) measured shoe production in units. One shoe equals one unit. So managers at factories across the USSR produced left shoes, warehoused them, reported their numbers, and collected their bonuses. Right shoes were, technically, someone else's problem.
This actually happened. Soviet citizens lined up for goods that existed in abundance on paper and in warehouses, completely unwearable without their missing counterpart. The absurdity is funny until you realize millions of people walked around in poorly fitted footwear because no price signal existed to tell any producer what consumers actually needed.
The Soviet shoe problem repeats itself wherever governments replace price signals with targets: hospital bed counts, agricultural tonnage, student graduation rates, housing units permitted. The metric gets optimized, but the underlying human need gets ignored.
Bureaucrats optimize for what gets measured. Markets optimize for what gets bought. Only one of those methods requires the person selling to actually satisfy you.

Exactly. It's completely shit to live under as well.
Those shoes you like? They won't exist. Shoes are shoes, and you will get what your bureaucrat decides you get, all size 8.
That little coffee place you are a regular at? Gone. Replaced by standing in line at your local grocer for 12 hours to see if the truck brought coffee this month.
You want to buy a car? Put your name on a list and wait 10 years.


Handre retweeted
The decline of the middle class seen in the US and Europe is happening in South Africa, perhaps a bit slower.
Up north, the story started in 1971 with the abandonment of the gold standard, from which point the thievery of central banking was properly unleashed. It was a more or less steady decline from there—though difficult to read because of the manipulation of inflation statistics—until the advent of the covid scam, when there was a sharp acceleration. It seems to have accelerated again this year and I’d expect it to accelerate again next year.
Meanwhile, in South Africa, the middle class swelled slowly and unevenly through to 2010, but it absorbed much of the hit from declining GDP per capita therafter. The covid scam of 2020 was a sharp and deliberate assault.
What’s happening now? Well, the SA Revenue Service lost 1m taxpayers over the last 20 years—about 50k per year. This year it expects to lose 100k. Rising energy costs from the deliberate Hormuz pseudoconflict and prodigious squandering of resources on “renewables” will wash through more next year, and I predict that tax base erosion will leap up again.
Little of this has to do with domestic policy or politics. All the major parties are instruments of the establishment banksters. So welcome to the K-economy and technofeudalism.
@biznews
@DailyFriendSA
@Sakeliga
@NeasaNews
Murray Rothbard took Mises's price theory and drove it to a destination Mises never reached.
Mises built the case that central planning fails because socialist planners cannot perform rational economic calculation without real market prices. Prices carry information that no committee can replicate. Rothbard accepted every word of this and asked the obvious follow-up: if state intervention distorts prices and destroys coordination, why stop your critique at the water's edge? Why exempt the state itself from the logic?
The answer required property rights. Rothbard grounded everything in self-ownership. You own your body. By extension, you own what you mix your labor with, provided you homestead it from a prior unowned state. Every other right flows from this. Taxation is the seizure of your property under threat of imprisonment.
From that foundation, Rothbard constructed anarcho-capitalism systematically, not as a utopian dream but as the logical terminus of taking rights seriously. Defense, arbitration, contract enforcement: private firms supply all of it in a competitive market. His 1973 book "For a New Liberty" laid this out with unflinching precision. His 1982 "The Ethics of Liberty" supplied the philosophical scaffolding.
What Rothbard accomplished was a fusion, not a compromise. Mises gave him the economic engine. Locke and Lysander Spooner supplied the moral chassis. The result was a system where aggression has no legitimate institutional home, including Congress, including the Federal Reserve, including every bureaucrat drawing a salary your paycheck funded involuntarily.

The establishment gave @JMilei months. In 2023, 170 Argentine economists signed a letter calling his dollarization plan an illusion, and Ian Bremmer wrote that he expected the economy to collapse in short order—typical Keynesian bullshit, always exactly wrong.
Then monthly inflation fell from 25% in December to nearly 10% by March, and after fifteen straight years of deficits, Argentina ran a primary surplus of 1.4% of GDP in 2025. His party more than doubled its congressional seats in the midterms.
The scoreboard has red ink too. Poverty fell to an eight-year low of 28% in late 2025, then jumped to 32.3% in the first half of 2026. Inflation ran at 33.4% a year, the second-highest in Latin America behind Venezuela, and the IMF cut its 2026 growth forecast from 3.5% to 2.1%.
@saifedean Ammous says the central bank explains the red ink. Milei campaigned on closing it and treated that as an absolute condition, then kept it. Ammous argues that a central bank monopoly on currency and banking licenses guarantees continued peso inflation, and that Ecuador, without its own national currency, cannot inflate even if it wants to.
He says Hoppe was right: Milei should have shut the bank and defaulted. Milei replies that the bank's debts and liabilities need to be cleaned up before it closes, and his proposed charter reform bans the bank from financing the Treasury.
The scorecard splits along the line Ammous draws. Milei cut the deficit and the apocalypse never came. He left the state's money monopoly standing, so the state still decides how many pesos exist.
But hey, Libertarians can cheer the first half and demand the second.
All eyes are on Javi to see how this plays out.

The Inflation King:
Everything you need to know about modern investing can be summed up in the story of one man: Hugo Stinnes, a German industrialist who built the largest private empire in Weimar-era Germany by doing something most people thought was reckless.
He borrowed. Constantly. Aggressively. In marks.
Stinnes came from a coal family in the Ruhr Valley and already ran a solid industrial operation before World War One. When the war ended and Germany began printing marks to pay its reparations debts under the Treaty of Versailles, most citizens watched their savings dissolve in real time. Stinnes drew the opposite conclusion than his neighbors. While German citizens hoarded paper marks in mattresses and savings accounts, Stinnes borrowed enormous quantities of those same marks from German banks, then immediately converted them into real assets: coal mines, steel plants, newspapers, shipping lines, hotels, forests, paper mills. By 1923 his conglomerate, the Stinnes-Konzern, controlled over 1,500 enterprises across Germany, Austria, and beyond. He employed roughly 600,000 people. The inflation that ruined an entire generation of German savers made Hugo Stinnes almost incomprehensibly wealthy.
How did he do it? When a government or central bank expands the money supply, the purchasing power of each existing unit of currency falls. Prices across the economy do not adjust simultaneously. The new money flows into specific assets first, before it filters through to wages and consumer goods, which means whoever holds those assets during the transition captures a windfall. Stinnes borrowed in a currency he correctly identified as dying, bought hard assets whose value was tied to physical reality rather than government decree, and then repaid his loans in marks worth a fraction of what he had borrowed. After the Weimar hyperinflation, the real value of what he owed was virtually nothing. He got the hard assets he bought with loaned marks for free.
Your house today runs the same play, just in slow motion. You take out a mortgage denominated in dollars, a currency the Federal Reserve has expanded by over 40 percent since early 2020. You hold a fixed-rate liability in a debasing currency while the asset itself reprices upward. The bank receives dollars of diminished purchasing power over thirty years. You hold the land and the structure.
The reason property specifically has captured so much of the post-2020 inflation is that new money always travels along the path of least resistance toward collateral-eligible, financeable assets. Residential real estate sits at the center of the credit system. Banks lend against it readily. Institutional buyers treat it as a store of value. When the Fed slashed rates to near zero, and Congress distributed trillions in fiscal transfers, that purchasing power flowed directly into housing markets with predictable results: U.S. median home prices rose from $329,000 in early 2020 to over $420,000 by 2026.
Stinnes died in 1924, before his empire unraveled under poor succession and deflation, but the strategy outlived him. Borrow in the currency they are destroying; hold the asset they cannot print.

France keeps electing governments that promise order while building the exact machinery that produces chaos.
The pattern is old. The 1968 uprising paralyzed Paris because de Gaulle had spent a decade expanding state payrolls, suppressing price signals, and convincing the French that prosperity required a bureaucrat's signature.
By 2005, the banlieues around Paris burned for three weeks. Clichy-sous-Bois, Aulnay-sous-Bois, hundreds of torched cars every night. The state had warehoused North African immigrants in subsidized housing blocks, disconnected from labor markets by minimum wage laws priced above their marginal productivity, and handed them welfare checks just generous enough to eliminate the urgency of assimilation.
That combination guarantees a poverty trap.
Today, with immigration remaining a central tension and pension expenditures consuming 14% of GDP, France runs the same experiment expecting different results.
You pay into a system your entire working life and receive benefits calibrated to political survival rather than actuarial reality. Meanwhile, each new transfer payment handed to recent arrivals without reciprocal labor market access breeds exactly the resentment politicians then exploit.
Open borders and a welfare state cannot coexist. Either migrants enter a free labor market and compete on merit, building genuine stakes in French civil society, or the state subsidizes parallel communities that have no economic reason to integrate. France consistently chooses the latter, then acts surprised at the friction.
Bastiat diagnosed this in 1850. The French state still hasn't read him.

Gresham's Law states that bad money drives out good, and every government that has ever debased its currency has proven this true the hard way.
The mechanism is straightforward. When a sovereign declares that two coins carry equal legal value despite one containing more silver, citizens spend the inferior coin and hoard the superior one. The overvalued bad money circulates. The undervalued good money disappears into mattresses and private vaults. The state creates this distortion through legal tender laws, forcing you to accept both coins at the same face value regardless of actual metal content. Without that legal compulsion, Gresham's Law doesn't operate. Markets simply price the better money higher.
Rome did this with systematic ferocity. The silver denarius, roughly 90% pure under Augustus, fell to under 5% silver by the reign of Gallienus in the 260s AD. Citizens watched the debasement happen and responded rationally: they spent the garbage and saved whatever genuine silver remained.
Gresham's Law is a symptom, not a disease. State monopoly over money is the disease. Remove the legal tender mandate, allow competing currencies, and good money wins on merit. Thomas Gresham identified the phenomenon in 1558 through observation. The cure has been available just as long.

LASIK eye surgery costs roughly $2,100 per eye today. In 1998, it cost $2,200 per eye. Adjusted for inflation, you are paying about 60% less for a procedure that has simultaneously become faster, safer, and more precise. That is what markets do when left alone.
Now compare that to a hearing aid. The FDA classified hearing aids as prescription medical devices for decades, locking you into audiologist appointments before you could buy a $3,000 device that a manufacturer could produce for $300. Or, look at insulin. Heavily regulated, patent-extended, and politically manipulated, a vial of Humalog ran over $330 in 2024 versus roughly $21 in Canada for a biosimilar. Same molecule. Different regulatory environment.
LASIK sits in a peculiar gap. Insurers rarely cover it, which means third-party payment schemes never severed the price signal between provider and patient. You shop, clinics compete, manufacturers race to improve technology. The feedback loop that markets depend on functions exactly as it should.
Regulated medical markets break that loop deliberately. The FDA's approval process costs pharmaceutical companies over $2.6 billion per new drug on average, erecting barriers that protect incumbents and punish smaller competitors who cannot absorb a decade of compliance costs. Patients then pay the premium on the back end.
LASIK is the control in the experiment. The market won.
