KCR Cap (@KcrCap) profile picture

Recovering buysider. Permabull, natural skeptic, opportunistically short. Not investment advice.

Joined November 2019
Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)Photo by KCR Cap (@KcrCap)
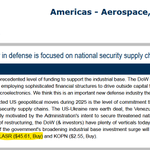
This one of the worst sell side reports I have ever read. Nothing of value, honestly wasn't sure why it was published. But they wanted to highlight $LASR. Next day... equity raise led by Stifel. Shameless
1
269
This was actually published: "Following the success of PLTR & Anduril using names from JR Tolkien, imagine the multiple this newly listed business might garner if it were named something like Thorondor or Ancalagon the largest & most powerful dragon in the history of Middle-earth
131
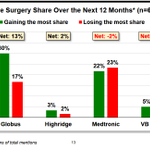
$GMED Structural share gainer thanks to innovation (robotics) and comprehensive product portfolio. Growing HSD, 30-35% EBITDA margins depending on assumptions for timing of synergies. Net cash position. Printing cash. HOLD rating at 8x EBITDA. Thanks sell side.
1
1
8
790
$GMED Aaand here come the upgrades. Yesterday: spine is terrible, structural loser. 8x EBITDA. Hold. Today: HSD rev grower, high teens EPS compounder. $91 PT (+50% from yesterday's price) Not expensive at 12x EBITDA. BUY.
1
178
Cyclical industrials getting tech valuations. Applaud this management team for taking advantage by raising capital, but what does this imply for future equity returns? And if they deploy this capital into similar high multiple businesses that are over-earning?
1
261
$GNRC You can buy $FSV at its lowest multiple in 8 years on trough earnings. I don't think AI will disintermediate restoration work.
6
1,426
One of the more interesting set-ups that I think will play out over the next 6 mos is $ICFI. Market is laser focused on the company's Fed Civ business, which has been torpedoed by DOGE. But market is missing growth in their commercial energy consulting biz. It's a sneaky AI play
1
2
6
1,027
While the market has correctly focused on the risk to Fed Civ revs, it has missed the success $ICFI is having in energy consulting. As Fed Civ rev concentration declines, this headwind to top-line growth should abate, leading to investor focus on commercial energy growth
1
1
280
With leverage <1.5x, $ICFI also has capacity for M&A to continue re-shaping the portfolio toward higher growth commercial energy markets
232
Does anyone have this chart/data from pre-Trump (maybe summer of 2024)? Would love to see how it has changed to see if we have actually stimulated manufacturing activity. @Borlaug_ post earlier today got me thinking more about this
2
229
$ORCL Isn't Larry stating the bear case for AI here? It's hard to monetize? But comes with a significantly higher cost and capital intensity? For reference, ORCL's applications biz is only growing +12%.
1
1
248
I want to believe, but today it seems like the only beneficiaries are the infrastructure providers. Everyone is paying to access models and cloud infrastructure, but where is the revenue supporting $400B+ of annual CAPEX if even $ORCL can't monetize their applications?
175
Every time I look at $PRM I think it's probably a great business, but I just can't get over the EverArc advisory fees. At some point does "shareholder alignment" go too far? Fees amount to 15% of current market cap
1
1
10
4,458
Paradox was just acquired by $WDAY for $1B, or a 30% discount to 2021 Series C round. Product looks incredible, one of the better use cases for AI. But valuations matter. I wonder how was this was marked in the private markets over the last few years? prnewswire.com/news-releases…
1
230
The slowdown in IT services spend may be more cyclical than secular as AI is currently distracting corporates from legacy spend, but should rebound when companies decide how (if) they want to implement AI?
310
$SES.TO experts... congrats, it's been a home run! Does anyone know how much of the waste processing EBITDA comes from produced water? Because I don't really see any biz in here that is worth > 8x EBITDA other than industrial landfills. $ARIS currently trading at 7x
4
1,752