

Latest venture: https://xitter.cf/t.co/cTbM6dKyH7 • Sold DepositAccounts to LendingTree • Former LendingTree Senior Analyst • Interests: banks, saving, investing & walking pup
Orlando, FL
Joined January 2019
- Tweets12.5K
- Following3.8K
- Followers4.5K
- Likes70.5K







Pinned Tweet
Top 5 online savings accounts by APY as of 10/19/2026
& thread on online savings account (OSA) yields and how OSA & money market fund (MMF) yields have changed since the first Fed rate cut (9/18/2024):
Top 5 Status: No change from last week.
Big 5 Status: AMEX APY up 10 bps to 3.20%

Brokerage Firms Want to Yank Away Your Investor Protections | @jasonzweigwsj
“as Warren Buffett has warned, “It’s only when the tide goes out that you learn who’s been swimming naked.” A long bull market breeds complacency, helping to provide cover for incompetence or fraud.”

My latest @WSJ column:
It could get even harder for investors to prevail when they try to recover losses from bad financial advice:
wsj.com/finance/investing/br…

25 years ago, on Oct 23, 2001, Steve Jobs introduced the iPod, the precursor to the iPad and the iPhone.
This 5-year old @CNET piece by @techledes about this iPod intro is a great read:
cnet.com/tech/mobile/what-it…
#OnThisDay


25 years ago today, Steve Jobs introduced Apple’s first iPod—a pocket-sized player that could hold up to 1,000 songs. Which 2001 hit would you have loaded first?
———
#OnThisDay #iPod #SteveJobs #MusicHistory #VARShares

“While passkey optionality is becoming more widespread, Killingsworth says there are several reasons passwords aren’t going away anytime soon.”

The Banking Industry Warms to Passkeys finxtech.com/the-banking-ind…

Ken Tumin retweeted

Why diversify internationally? These illustrations answer that question best.

Always funny to me to hear people say "International investing hasn't worked".
What they really mean is "international investing hasn't worked for American investors during this cycle".
It's worked splendidly for most investors in nearly all countries around the globe....
My favorite table on this concept is from Bridgewater (link broken)
"This decade, the US has been the best performer so far, but it was one of the weaker performers in the previous decade following the dotcom bust; it was one of the best performers in the 1990s...but before that you have to look back to the 1920s to find a decade in which US equity performance was better than middling."
mebfaber.com/2020/01/10/the-…


Ally Bank increased the rate of its savings account and money market account today by 10 bps to 3.20% APY. This is Ally’s second 10-bp rate hike since the September Fed rate hike.
Ally savings account rate reached its peak of 4.35% APY in early 2024. The rate started to fall in April 2024, about five months before the first Fed rate cut. It reached its recent bottom of 3.00% APY last June.
Below are the recent savings account APY hikes from major online banks since the Sep 16th Fed rate hike:
Ally: 3.00% → 3.10% (Sep 25) → 3.20% (Oct 23)
CapOne: 3.00% → 3.10% (Sep 25) → 3.20% (Oct 21)
AMEX: 3.00% → 3.10% (Sep 23) → 3.20% (Oct 15)
Synchrony: 3.30% → 3.55% (Sep 30)
Marcus: 3.40% → 3.50% (Sep 18)
Ally also raised APYs on several of its CDs:
5-year: 4.25% → 4.50%
3-year: 4.10% → 4.25%
18-mo: 4.40% → 4.50%
14-mo: 4.30% → 4.50%
12-mo 4.30% → 4.50%
11-mo: 2.80% → 2.90%
9-mo: 4.00% → 4.15%
7-mo: 3.85% → 4.00%
6-mo: 3.85% → 4.00%
3-mo: 2.80% → 2.90%
It’s noteworthy that Ally still hasn’t increased the rate of its Raise Your Rate CDs (2- and 4-year remain at 3.00% APY). Customers who have these CDs will have to keep waiting to take advantage of the option to increase their rate to a higher rate.

Ken Tumin retweeted

Sallie Mae Cuts Full-Year View After Logging Higher Charge-Offs on.wsj.com/4emex56

Ken Tumin retweeted

Today's 5-year TIPS auction got a real yield of 2.367%, good but not awe-inspiring. Auction investors got caught in a down-draft of Treasury yields ... tipswatch.com/2026/10/22/5-y…

Ken Tumin retweeted

Thursday's 10-year Treasury yield decline of 0.193 percentage point (to 4.952%) is the largest single day yield decline since March 10, 2023, which is the day Silicon Valley Bank failed.
119 years ago, on October 22, 1907, a massive bank run forced the Knickerbocker Trust Company—then the third-largest trust in NYC—to suspend its operations, triggering the Panic of 1907.
The Panic of 1907 spurred greater oversight of the financial markets and would lead to the 1913 Federal Reserve Act, which established the Federal Reserve system as we know it.
#OnThisDay
Sources:
federalreserve.gov/pubs/IFDP…
researchgate.net/publication…
thestreet.com/dictionary/pan…

📜 #OnThisDay in 1907: a run hit Knickerbocker Trust, one of NYC's biggest. It paid out $8M in 3 hours, then shut its doors.
J.P. Morgan ($JPM's namesake) led the rescue, and the panic led to the Fed in 1913.
Could a run like that happen today? 👇
#StockMarket #Investing

Blindsided by AI Agents, Big Banks Scramble to Beef Up Security | @_webbwright for @Gizmodo
“Believe it or not, some people appear to be granting agents access to their bank accounts.”
gizmodo.com/blindsided-by-ai…

Ken Tumin retweeted

We're seeing a HUGE pullback in long-term Treasury yields today:
• 10-year: 5.006%, down 11.2 basis points
• 20-year: 5.375%, down 9.2 basis points
• 30-year: 5.326%, down 8.6 basis points
Investors are seeking safety as tech stocks sell off and concerns over France’s government debt intensify.

One of the rate leaders in today’s DQ CD leaderboard is the 24-month CD from Merrick Bank that’s on the Raisin platform (5.00% APY).
More online-only banks, like Merrick, are utilizing the Raisin platform for deposits. Two examples of large online banks include EverBank and Live Oak Bank. Raisin makes it easy for banks and credit unions to offer online HYSAs, MMAs and CDs. But what does an online-only bank have to benefit from Raisin? Perhaps they see it as brokered deposits that allow them to quickly raise deposits without impacting their regular customers. But, unlike brokered deposits at brokerage firms, Raisin deposits aren’t officially brokered deposits.
Raisin CDs are more like direct CDs than brokered CDs. Unlike brokered CDs, Raisin CDs have early withdrawal penalties. If you want the funds from a brokered CD before maturity, you have to sell it on the secondary market. Raisin lists product terms for each CD. Most terms are the same ($1 minimum, no partial early withdrawals, interest can’t be paid out), but early withdrawal penalties often vary. This Merrick CD has an EWP of 180 days’ interest. So if you close the CD after one year, you’ll lose half the accrued interest (effective APY falls to about 2.5%).
One similarity to brokered CDs is that Raisin CDs can be callable CDs. This allows the bank to end the CD early before maturity. The vast majority of Raisin CDs are standard non-callable CDs. Those that are callable are clearly labeled.
One benefit this Raisin 24-month CD has over Merrick Bank’s direct 24-month CD is a higher yield (5.00% vs 4.91%). Also, the minimum deposit is much lower ($1 vs $25,000). A benefit with Merrick’s direct CDs is that interest payments are allowed.
For rate-shopping deposit consumers, Raisin has several benefits, but Raisin is a non-bank fintech. The Synapse-Evolve debacle illustrates the risks of banking at fintechs.


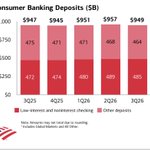
Bank of America Q3 earnings provide a good example of how much deposits are earning essentially zero interest. BofA’s Consumer Banking reported $485 billion sitting in checking accounts with essentially zero interest rates.


“For banks and credit unions, the risk is not just your own website. It is every loan application, account-opening flow, rate widget, chat tool and marketing platform you have embedded or linked from it.”

PHP2Shell: The Internet’s Biggest Security Scare in Years Just Hit. Here’s What Banks and Credit Unions Need to Do NOW
marketingbanks.com/php2shell…

Another credit union offers a 5% APY CD.
As mentioned in today’s CD leaderboard by @DepositQuestKCJ, California-based Kinecta Federal Credit Union is offering 5% APY on a 30-month promo certificate.
Kinecta is a large credit union with $6.8 billion in assets. My first review of Kinecta was 20 years ago in 2006 when it was offering a 5% CD. During the last 20 years, it has offered online account opening and nationwide membership via an association membership.
depositquest.substack.com/p/…

18 years ago, on Oct 22, 2008 during the financial crisis, Wachovia posted a $23.7 billion net quarterly loss, the largest ever reported by a U.S. bank. Much of the loss was the result of write-downs tied to the mortgage lender Golden West Financial which Wachovia had purchased in 2006.
Before the report of this loss, Wells Fargo had already agreed to acquire Wachovia, and this news did not change Wells Fargo’s plans. The acquisition officially completed on December 31, 2008.
#OnThisDay
Sources:
washingtonpost.com/wp-dyn/co…
web.archive.org/web/20201109…
latimes.com/archives/la-xpm-…
federalreserve.gov/newsevent…

Although technically Wachovia didn't fail, it essentially ended on Sep 29th:
xitter.cf/KenTumin/status/210485…

18 years ago, on Sep 29, 2008, marked the end of Wachovia. At the time, Wachovia was the fourth largest bank in the nation with assets of $812 billion. The FDIC announced that Citigroup would acquire the banking operations of Wachovia. In its press release, the FDIC stated that “Wachovia did not fail; rather, it is to be acquired by Citigroup Inc. on an open bank basis with assistance from the FDIC.”
On October 3, 2008, the FDIC announced a change. Wells Fargo would acquire Wachovia instead of Citigroup. The Wells Fargo acquisition did not require FDIC assistance. Citigroup filed suit.
#OnThisDay, #OTD
Sources:
archive.fdic.gov/view/fdic/3…
archive.fdic.gov/view/fdic/3…
federalreserve.gov/newsevent…
2-year non-callable brokered CD rates reached 5.00% today at Fidelity, Vanguard and Schwab.
Higher rates were available on longer terms (5.10% for 3-years, 5.15% for 4-years and 5.20% for 5-years).
A month ago, the highest 5-, 4-, 3- and 2-year rates were 4.85%, 4.80%, 4.70% and 4.60%.
Coincidentally, Capital One, which just reported its earnings yesterday, was one of the banks that had issued these 5% rates for the 2- to 5-year terms.
Brokered CD rates have been following Treasury yields, but they generally lag. So we may soon see declines of brokered CD rates if Treasury yields continue to fall. At yesterday’s close, 5-, 3- and 2-year Treasury yields were estimated to be 4.94%, 4.86% and 4.79% (per Daily Treasury Par Yield Curve Rates).

A wave of new banks is about to shake up a normally staid industry | @AmerBanker
"New regulatory attitudes seem to have coincided with the maturation of many nonbanks to the point where the benefits of controlling a bank outweigh the costs and burdens."
A wave of new banks is about to shake up a normally staid industry americanbanker.com/opinion/a…

Pibank has retaken the top spot as the highest-rate savings account (non-promo rate, directly from an FDIC-insured bank and a low min balance.) Pibank increased its savings account rate by 15 bps to 4.40% APY. This is its second rate increase since the Fed’s Sep 16th rate hike (On Sep 30th, it increased its rate by 15 bps.)
For much of 2025 and 2026, the Pibank savings account was a rate leader with a 4.60% APY. Its peak APY was 5.50% APY when it launched in Aug 2024.
I reviewed Pibank savings and the parent bank, Intercredit Bank, in this February thread:
xitter.cf/KenTumin/status/202134…

