- Analyst & CEO at @milkroaddaily @milkroadai - Helping everyday investors catch technological trends early - Check out my real-time portfolio below
See my Portfolio →
Joined September 2020
- Tweets12.9K
- Following2K
- Followers23.1K
- Likes22.8K
Pinned Tweet
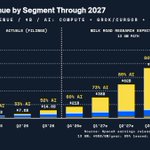
SpaceX capex in the next 5 quarters needs to hit ~$470 BILLION to reach 13 GW by EOY '27 (Elon's new guide)
The BIGGEST WINNER of this capex is NVIDIA, taking 83-89% of the entire expense!
If Elon builds all 13 GW, that's $414B of $NVDA revenue from ONE customer. That's $310B of gross profit and $200B of net income for NVIDIA!
Let me put that number in context:
- Nvidia's ENTIRE revenue last year was $216B. One customer is about to pay them nearly double that in 5 quarters
But here's the part that is important to understand from a trend perspective: Nvidia's cut of every dollar is going UP
- Blackwell era: ~$25B of every $30B per GW goes to Nvidia (83%)
- Vera Rubin era (ships at scale from Q2'27): ~$40B of every $45B per GW (89%)
SpaceX is famous for vertical integration. They build their own power, their own buildings, their own everything to cut costs...
But you can't vertically integrate Nvidia GPUs, they are too good of a product to try and replicate
This is the pattern I keep coming back to: whoever wins the AI race, Nvidia gets paid. Every GW announcement, every "new hyperscaler," every compute arms race headline is just an Nvidia purchase order in disguise
I own both $NVDA and $SPCX, as I believe these two companies will be the clear AI winners in the coming years
Myself and the 4 other analysts at Milk Road PRO share our full portfolios, every trade with live notifications, and the research behind it all. Try it for $1 (insane price just to check it out). See link in bio to join
Kyle Reidhead | Milk Road retweeted
Piper Sandler just put a $475 price target on $TSLA, the highest of 7 new price targets after Q3.
That's about 27% upside from ~$373, where the stock trades right now.
5 more firms held, and Cantor Fitzgerald still has the top target at $485 (unchanged).
The biggest moves:
CLSA: $400 (from $310), upgraded to Hold
UBS: $425 (from $391)
Canaccord Genuity: $442 (from $410)
Piper Sandler: $475 (from $450)
Goldman Sachs held at $360, the only target below the current price.
Most of the raises lean on things already in the numbers, like FSD adoption and energy margins. CLSA is the outlier: it upgraded on SpaceX merger sentiment.
This looks structural. FSD is now showing up in Wall Street's targets, while Optimus and Robotaxi revenue still sit further out.
Is Cantor's $485 too high, or is Goldman's $360 too low?

ALT Table of Tesla price targets after Q3, old vs new, with upside from $372.80 premarket: Cantor Fitzgerald $485 to $485 (+30%); Piper Sandler $450 to $475 (+27%); Mizuho $450 to $460 (+23%); Bank of America $460 to $460 (+23%); TD Cowen $460 to $460 (+23%); Canaccord Genuity $410 to $442 (+19%); JPMorgan $415 to $430 (+15%); UBS $391 to $425 (+14%); Morgan Stanley $400 to $410 (+10%); CLSA $310 to $400 (+7%); Jefferies $400 to $400 (+7%); Goldman Sachs $360 to $360 (-3%)
Piper Sandler raises its price target on $TSLA to $475
Piper says Q3 beat consensus and most of Tesla's P&L drivers are improving
As for the after-hours dip, Piper thinks the SpaceX call set a HIGH bar with big AI upside and open merger talk. That made Tesla's call look tame by comparison
Barclays raises its price target on $META by $100 to $880
Core ad revenue grew 26% vs the 24% the Street expected
Muse had 10M sign-ups in 6 weeks, with about 25% using it DAILY
And management is targeting a 10x cost-efficiency gain for Muse in 2027
$META reports its Q3 earnings tonight
Here's what the Street expects:
1. Revenue: $63.34B, up ~24% y/y and at the TOP of its $61B to $64B guide
2. EPS: ~$6.53-$6.64 (some estimates sit near $3.56 because they include a ~$10B legal charge)
3. Q3 capex: ~$41.7B and 2027 capex: ~$193B
The real swing factors are the Q4 revenue guide and 2027 capex, plus how many people are actually using Muse
Meta is becoming a beast of an AI company across its new models, Muse and its impact on its advertising business
Bank of America raises its price target on $SPCX to $275 from $235
Bank of America says Q3 beat the Street on every metric and SpaceX "raised the ante on what's coming in 2027"
The $100B run-rate by the end of 2026 is "not only on track, it's approaching rapidly"
And Q1'27 revenue guidance of $33B to $37B came in WAY above the ~$22B consensus
WOW! We just got guidance for Q1 2027 from the SpaceX CFO
They are expecting $33B-$37B in total revenue in Q1 27', a 150% increase in the next 6 months!
The bulk of this comes from reaching 3 GW of compute by EOY and least 2.5 GWs/quarter in 2027
The big advantage SpaceX has is their ability to energize GPUs. The bottleneck right now is the blades for turbines which take 12-18 months to deliver
But Elon says SpaceX is doing advanced casting to build their own blades at scale much faster, which can get them to at least 13GW total by EOY 2027, but potentially upwards of 20GW
And because SpaceX can deliver these GWs so fast, they payback period takes just months (rather than years). Giving them the ability to fund the Capex required to build this amount of compute through revenues, rather than only relying on debt
Piper Sandler raises its price target on $TSLA to $475
Piper says Q3 beat consensus and most of Tesla's P&L drivers are improving
As for the after-hours dip, Piper thinks the SpaceX call set a HIGH bar with big AI upside and open merger talk. That made Tesla's call look tame by comparison
WOW, this is the number that matters for Tesla earnings!
FSD subscriptions hits 1.74 MILLION, up 260k from last quarter…its biggest jump in FSD subs ever!
Tesla says they achieved record FSD attach rates in North America in Q3 2026, with 75% of all new deliveries including FSD subscriptions, up from 55% in Q2 2026
FSD is driving demand for Tesla vehicles
I own a Tesla myself and I can tell you first hand it’s a game changer. I use it 99.9% of the time and it’s changed what it means to drive for me
I get work done while my car drives me and I never have to think about traffic or directions. Once you try it you will see why this is revolutionary technology
This is what keeps me bullish on the stock even though its growth is not as strong as its valuation premium is. Tesla is ready for a truely breakout year in 2027 imo because of this technology, from car delivered to the robotaxi networK
$BE reports its Q3 earnings tonight
Here's what the Street expects:
- Revenue of $1.07B vs $519M a year ago
- EPS of ~$0.70 vs $0.15 a year ago
- Gross margin near Bloom's own ~34% full-year guide vs 30.4% a year ago
- FY26 revenue guide of $3.9B to $4.2B held or raised
A $1.07B Q3 keeps Bloom on pace for that range, so a raise is what the bulls WANT to see
Goldman Sachs reiterates its Buy rating and $300 price target on $NVDA after Jensen's GTC Berlin keynote
Goldman says Nvidia's message reinforced that AI deployments remain on track "for the foreseeable future"
Customers, including hyperscalers and neoclouds, are seeing STRONG unit economics on the datacenters they're running today. And Nvidia is helping partners cut deployment timelines while driving operating efficiencies
Nvidia is also taking steps to make sure its supply chain is ready, and it's rolling out hardware and software tools to lock down unauthorized use of AI agents, especially in the enterprise
As for catalysts, Goldman sees more visibility into AI datacenter deployments as Nvidia closes the gap between supply and demand, plus strong capital returns with ~$235B of buybacks authorized
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
Kyle Reidhead | Milk Road retweeted
Goldman Sachs reiterates its Buy rating and $300 price target on $NVDA after Jensen's GTC Berlin keynote
Goldman says Nvidia's message reinforced that AI deployments remain on track "for the foreseeable future"
Customers, including hyperscalers and neoclouds, are seeing STRONG unit economics on the datacenters they're running today. And Nvidia is helping partners cut deployment timelines while driving operating efficiencies
Nvidia is also taking steps to make sure its supply chain is ready, and it's rolling out hardware and software tools to lock down unauthorized use of AI agents, especially in the enterprise
As for catalysts, Goldman sees more visibility into AI datacenter deployments as Nvidia closes the gap between supply and demand, plus strong capital returns with ~$235B of buybacks authorized
Kyle Reidhead | Milk Road retweeted
WOW, this is the number that matters for Tesla earnings!
FSD subscriptions hits 1.74 MILLION, up 260k from last quarter…its biggest jump in FSD subs ever!
Tesla says they achieved record FSD attach rates in North America in Q3 2026, with 75% of all new deliveries including FSD subscriptions, up from 55% in Q2 2026
FSD is driving demand for Tesla vehicles
I own a Tesla myself and I can tell you first hand it’s a game changer. I use it 99.9% of the time and it’s changed what it means to drive for me
I get work done while my car drives me and I never have to think about traffic or directions. Once you try it you will see why this is revolutionary technology
This is what keeps me bullish on the stock even though its growth is not as strong as its valuation premium is. Tesla is ready for a truely breakout year in 2027 imo because of this technology, from car delivered to the robotaxi networK
$TSLA just reported its Q3 earnings and the stock is moving higher after hours
Here's how it stacked up:
1. Revenue of $28.05B vs $28.3B est
2. EPS of $0.48 vs $0.45 est
3. Gross margin of 19.6% vs 17.9% est
4. Operating income of $718M vs $721M est
5. Free cash flow of +$1.53B vs -$4.5B est
Capex came in at $4.73B vs ~$7.8B est, and Tesla ended the quarter with $45.4B of cash
Overall a solid quarter that is setting Tesla up for scale in 2027 with robotaxis, more car/semi deliveries, energy deployment and FSD subs
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
Kyle Reidhead | Milk Road retweeted
$TSLA just reported its Q3 earnings and the stock is moving higher after hours
Here's how it stacked up:
1. Revenue of $28.05B vs $28.3B est
2. EPS of $0.48 vs $0.45 est
3. Gross margin of 19.6% vs 17.9% est
4. Operating income of $718M vs $721M est
5. Free cash flow of +$1.53B vs -$4.5B est
Capex came in at $4.73B vs ~$7.8B est, and Tesla ended the quarter with $45.4B of cash
Overall a solid quarter that is setting Tesla up for scale in 2027 with robotaxis, more car/semi deliveries, energy deployment and FSD subs
$TSLA reports its Q3 earnings tonight
Here's what the Street expects:
- Revenue: $28.3B vs $28.1B a year ago
- EPS: $0.45 vs. $0.33 in Q2
- Gross margin: 17.9% vs 16.8% in Q2
- Operating income: $721M vs $398M in Q2
- Free cash flow: -$4.5B on ~$7.8B of capex
The key things to look for are:
- how many new FSD subs vs. new vehicles
- guidance around robotaxi/cybercab scale + margins
- launch date for humanoids
I dont expect any crazy fireworks tonight from Tesla earnings like the SpaceX earnings from last night
Cursor is currently driving $4.9 BILLION in ARR to SpaceX
$SPCX shared that from August 14 - Sept 30, Cursor drove $608 Million in revenue. Assuming this is subscription revenue, if we annualize that 1.5 months we get just under $5 BILLION
And this doesn't count revenues from Grok, so the combination of the two is very likely to be close to $10 Billion in ARR
This is the first time we've seen any numbers from Cursor since the announcement of the acquisition
After a first pass, these numbers from SpaceX are actually wild!
All 3 business lines (Space, AI & Connectivity) beat expectations and profitable, with AI beating by more than $1 Billion in the quarter
By Sept 30, they hit 1.7 GW of compute, 113 launches YTD and 13.6m Starlink Consumer subs with 100s of thousands of enterprise subs
Importantly, they also improved the Stalink ARPU by 5%, up to $69
They have not broken down the revenue separation across the AI labs vs AI Compute but hopefully on the earnings call we'll get more details here, in addition to the amount of compute coming online in Q4, which I expect to be another 1GW
Will update more from the earnings call but this is an absolutely incredible earnings report so far
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
$TSLA reports its Q3 earnings tonight
Here's what the Street expects:
- Revenue: $28.3B vs $28.1B a year ago
- EPS: $0.45 vs. $0.33 in Q2
- Gross margin: 17.9% vs 16.8% in Q2
- Operating income: $721M vs $398M in Q2
- Free cash flow: -$4.5B on ~$7.8B of capex
The key things to look for are:
- how many new FSD subs vs. new vehicles
- guidance around robotaxi/cybercab scale + margins
- launch date for humanoids
I dont expect any crazy fireworks tonight from Tesla earnings like the SpaceX earnings from last night
$TSLA is on pace for one of its best years of car deliveries ever!
Q3 deliveries crushed: 486,532 vs Est. 463,761
That’s 2 huge beats in a row. It will be interesting to hear if this is again because of the demand for FSD, like Elon mentioned last quarter
Tesla also deployed 13.7 GWh of energy storage in Q3, the 2nd best quarter ever
Tesla products are in serious demand and this is all before robotaxi scale and Optimus launch
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
$TSLA just reported its Q3 earnings and the stock is moving higher after hours
Here's how it stacked up:
1. Revenue of $28.05B vs $28.3B est
2. EPS of $0.48 vs $0.45 est
3. Gross margin of 19.6% vs 17.9% est
4. Operating income of $718M vs $721M est
5. Free cash flow of +$1.53B vs -$4.5B est
Capex came in at $4.73B vs ~$7.8B est, and Tesla ended the quarter with $45.4B of cash
Overall a solid quarter that is setting Tesla up for scale in 2027 with robotaxis, more car/semi deliveries, energy deployment and FSD subs
$TSLA reports its Q3 earnings tonight
Here's what the Street expects:
- Revenue: $28.3B vs $28.1B a year ago
- EPS: $0.45 vs. $0.33 in Q2
- Gross margin: 17.9% vs 16.8% in Q2
- Operating income: $721M vs $398M in Q2
- Free cash flow: -$4.5B on ~$7.8B of capex
The key things to look for are:
- how many new FSD subs vs. new vehicles
- guidance around robotaxi/cybercab scale + margins
- launch date for humanoids
I dont expect any crazy fireworks tonight from Tesla earnings like the SpaceX earnings from last night
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
Kyle Reidhead | Milk Road retweeted
Tesla FSD subscriptions were up 67% YoY in Q3 2026 to 1.74 million, an increase of 260,000 from Q2 2026.
Tesla added more FSD subscribers in Q3 than in any quarter in its history.
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
I'm 1 of 5 analysts at Milk Road. Our job is to find hidden gems for our members before the market catches on.
We were early to $MU, $NBIS, $BE and many more
Check out our real-time portfolios here before you miss the next big runner we call:
link.milkroad.com/t5837z
Wow! Elon is not messing around with this goal of 3GW by EOY and 13 by 2027!
$SPCX is paying employees 20% MORE to volunteer to go build AI data centers in Memphis right now
The email to all employees said: “We now need leaders, current and emerging, to guide teams and remove blockers as we bring more supercomputers online"
Elon also said on the Q3 call that he's been spending "often four days a week" in Memphis working on this problem
There is so much demand that SpaceX just needs to unlock the supply of compute and they will dominate. SpaceX is going ALL IN
$SPCX isn't just the fastest to build AI compute, it's also the most cost-effective!
And after the week neoclouds just had, that really matters
SpaceX installed 1.4 GW of compute at $29.6B/GW, with the latest build at $32.6B/GW
Most estimates put a GW of compute at $40-50B
That cost edge is why SpaceX's CFO said on the Q2 call that new compute deployments are paying back in LESS than 1 year (insane for infrastructure)
SpaceX expects to end this year with over 2 GW and is guiding to "closer to 10 GW than 5 GW" by the end of 2027 (and Elon's hinted it could be even more)
Adding ~8 GW in 2027 at their current $32.6B per GW is roughly $260B of capex
That's a massive number, but I think they can fund it no problem
SpaceX ended Q2 with $100B in cash
They're reportedly raising another $40B in debt specifically to buy NVIDIA GPUs
And they're guiding to a $100B annualized revenue run rate by December (I think they end the year closer to $125B)
But here's the part most people miss
With a sub-1-year payback, the GWs they turn on in early 2027 help pay for the GWs they build in late 2027. The buildout partially funds itself, and they can stay profitable while doing it
My estimate is $350-450B of ARR by the end of 2027
There's also a second path to 10 GW (or more): buying distressed neoclouds
CoreWeave's bonds are yielding over 15% (distressed territory) and the whole sector got hammered this week. If any of these smaller neoclouds mismanage their capital (or execution), they may soon be looking for a buyer... and no one is better positioned to step in than SpaceX
Whether they build or buy, I think SpaceX will hit 10GW of compute by EOY 2027
for that reason, $SPCX is a core asset I hold in my Milk Road PRO portfolio. You can track my entire real-time portfolio here: link.milkroad.com/t5837z