

President, Murray Wealth Group. Tweets are not investment advice. MWG may or may not have positions in securities mentioned in tweets.
Toronto, Canada
Joined September 2019
- Tweets3.3K
- Following719
- Followers3.2K
- Likes4.8K




Newest holding in our Global Equity Growth Fund. $BCO
murraywealthgroup.com/2026/1…

1
8
851
Jamie Murray retweeted

$UBER CFO @_balaji_km presented at Morgan Stanley's European TMT conference this morning. Here's what I took away from it.
1) Huge penetration opportunity still lays ahead of Uber in its densest markets. Only 50% of consumers in those markets have used Uber at least once in the last 12 months.
2) Uber's advantage in AV deployments is multi-fold. One aspect, which I hadn't appreciated, is the advantage they have in placing charging infrastructure in critical locations based on their demand heat maps. A large proportion of future costs of AVs will be in fleet management and minimising this on a per mile basis will materially alter the economics of future AV fleets.
3) Platform costs are real and represent a substantial burden for 1P AV deployments. Uber has existing economies of scale relating to customer support, insurance, marketing, etc. already serving 16bn trips per year. Incremental AV trips on Uber will be more profitable despite their take rate.
4) Mgmt. is leveraging Uber's balance sheet to support the AV ecosystem, much the same way NVIDIA has done with AI. Notably, their equity investments aren't blank checks, but rather contingent on partners achieving specific milestones.
5) Gating factor to growth is supply not demand. Monthly active consumers to monthly active drivers is 20:1. High gas prices keep drivers at bay but the company is shifting incentives to encourage more supply. Longer-term, rising EV penetration is a net benefit for the company.
6) Delivery continues to be deeply underappreciated. It is growing fast and profitably on its own, yet its benefits to the broader system cannot be overstated. Along with announced partnerships (Costco, Amazon, McDonalds) it is helping penetration in sparse markets. It is also likely contributing to Uber One membership growth, now at 55m globally and these members drive 70% of delivery gross bookings.

Jamie Murray retweeted

Scoop: Another massive AI data-centre project could be coming to Alberta—right next to Meta's $13B campus. Land records and regulatory filings reveal plans for a data centre of up to 3.6 GW on property recently acquired by a company linked to Pembina Pipeline and Morgan Stanley Infrastructure Partners. $PPL.TO

$DBM.TO love to see it.
CEO Commitment to Shareholder Alignment
Amar Doman, the Company’s Chairman and Chief Executive Officer has established an automatic securities purchase plan (“ASPP”) pursuant to which 100% of his net after-tax base salary will be used to purchase common shares of the Company in the open market. Purchases under the ASPP are expected to commence in December 2026 and will be administered independently by a third party broker at approximately 90 day intervals, without discretion or involvement by the CEO in determining the timing, price or number of shares purchased. The arrangement underscores the CEO’s long-term commitment to the Company and his confidence in the Company’s future, while further aligning his personal financial interests with those of the Company’s shareholders.
Nice results from $PPL.TO last night. $GEI.TO too. We own both - but have to wonder if Gibson is envious of Pembina's growth pipeline. I wrote about it here.
murraywealthgroup.com/2026/1…

Revamped twitter/X account is live. Old account will be de-activated. Please follow along to read our weekly thoughts and notes.
You can also subscribe to our email distribution list on our website.

From a Canadian retail success story to a potential global powerhouse, Aritzia is entering an ambitious new phase of growth. With plans to double its U.S. store footprint by 2032 and establish a meaningful presence overseas, how far could they go?
bit.ly/4iH41a4

Jamie Murray retweeted

Congrats to the Uber team…. I just opened the Amazon app and ordered donuts to the ranch
Worked flawlessly… authenticated my Uber account with Amazon and got free delivery since I ordered over $25 in donuts and I’m a Prime member!
Exceptional value to Amazon Prime subscribers @ajassy @dkhos 👏
Long $UBER & $AMZN


💥 @UberEats is now on @Amazon.
We’ve always believed in meeting customers where they are. Amazon takes that to a whole new scale.
U.S. Prime members now get a $0 Delivery Fee on restaurant orders over $25. No new app. No Uber account needed.
investor.uber.com/news-event…
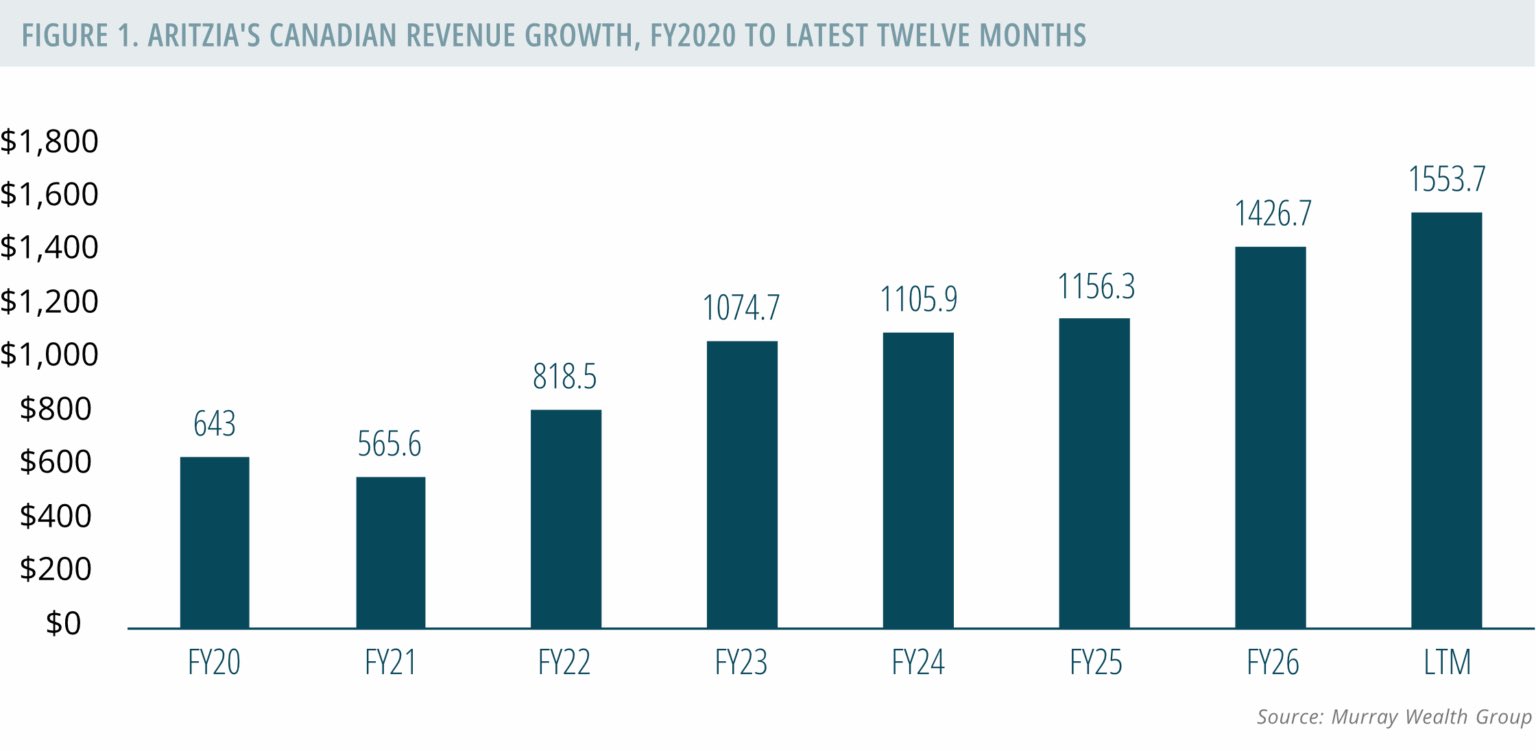
$ATZ.TO Canada revenue has more than doubled since the pandemic on a flat store count (about 12 repositions have increased square footage ~20%). The division grew 20% last quarter.
Jamie Murray retweeted

Microsoft says 90% of Copilot queries are "auto" mode i.e. the user doesn't care about the model.
A glimmer of hope for software.
Full report here $ATZ.TO
murraywealthgroup.com/2026/1…


FInal thoughts on Aritzia $ATZ.TO Investor event: Even more bullish than I expected.
I believed international would be the focus with stores now in the major metros in the US and brand penetration reaching 20% of Canada in terms of per capital spending. However, management expressed confidence in the larger US opportunity which comes with less execution risk, higher margins and better returns.
Management outlined a path to $7.5B in US, ~2.5x higher than FY27. Green space remains with $10B LT in sight. It's clear management thinks e-Commerce opp is much bigger than success to date implies.
As well, Canada is guided with modest growth (~$250M added revenue 5 year plan). That's the same absolute growth that Aritzia achieved off a smaller base in 2026. Room to grow with product expansion, and understandably conservative but historical track record of outperformance.
International awareness is very high at 40% of social and given Groupe Dynamite success in UK, implies success should be achievable. I think $2B long term is within reach.
Finally margin guide is very reasonable and probably conservative but leaves room for additional investment opportunities should that arise.
FInal thoughts on Aritzia $ATZ.TO Investor event: Even more bullish than I expected.
I believed international would be the focus with stores now in the major metros in the US and brand penetration reaching 20% of Canada in terms of per capital spending. However, management expressed confidence in the larger US opportunity which comes with less execution risk, higher margins and better returns.
Management outlined a path to $7.5B in US, ~2.5x higher than FY27. Green space remains with $10B LT in sight. It's clear management thinks e-Commerce opp is much bigger than success to date implies.
As well, Canada is guided with modest growth (~$250M added revenue 5 year plan). That's the same absolute growth that Aritzia achieved off a smaller base in 2026. Room to grow with product expansion, and understandably conservative but historical track record of outperformance.
International awareness is very high at 40% of social and given Groupe Dynamite success in UK, implies success should be achievable. I think $2B long term is within reach.
Finally margin guide is very reasonable and probably conservative but leaves room for additional investment opportunities should that arise.
$NOW saw seat counts grow dd, acceleration vs LY in quarter, according to Bernstein callback
8
1,447
Jamie Murray retweeted

#BREAKING: 3 people shot inside Bridle Path home, 4 taken to hospital: Toronto police. toronto.citynews.ca/2026/10/…


$AON top line results beat across the board. Stocks has moved off bottom and USI integration is key. I laid out the case with BNN earlier this month (written notes in articles).
bnnbloomberg.ca/markets/2026…

1
6
963
Aritzia didn't commit to any specific int'l markets but they did guide to $500M in int'l sales and half of that being physical stores. We estimate the NYC flagships can do $50-60 M sales so you're looking at large 2-3 cities - UK, Mexico, Brazil called out - Mexico and UK most likely IMO
Aritzia 5 year plan - 15-17% sales CAGR, EPS growth above sales, international expansion - webcast starts at 1015am
investors.aritzia.com/invest…

1
26
1,605
Aritzia 5 year plan - 15-17% sales CAGR, EPS growth above sales, international expansion - webcast starts at 1015am
investors.aritzia.com/invest…