

DeFi Researcher | Dune Wizard 🧙
Singapore
Joined November 2022
- Tweets4K
- Following569
- Followers2.2K
- Likes3.5K





Pinned Tweet
1.61% Bitcoin yield could be worth more than a 10% headline APY.
A recent report from Pareto highlights a good example of this.
One Bitcoin yield strategy reached around 10% APY, largely driven by temporary token incentives. Once those incentives end, the headline yield can drop sharply.
That's the problem with strategies that rely heavily on incentives. APYs can look attractive in the short term, but those returns can change quickly once the subsidies run out.
Now look at @paretocredit x @Two_Prime Axiom WBTC Vault, it currently offers around 1.61% net APY, paid directly in WBTC.
The key difference is where the yield comes from.
Institutions borrow Bitcoin for trading, financing, and liquidity management. They pay interest on those loans, and part of that revenue flows back to lenders through the vault.
There's also a credit structure behind that yield.
Two Prime puts up 150 WBTC of its own capital as first-loss protection, alongside monthly lending cycles and a Credit Agreement covering lender rights and recovery procedures.
Of course, credit yield still comes with default risk, and the 1.61% APY isn't guaranteed.
But for long-term Bitcoin holders, I think this is a different way to look at yield.
If your goal is to accumulate more Bitcoin over the years, how sustainable that yield is matters just as much as the headline APY.
Rather than chasing the highest number, I'd pay more attention to three things:
Who's actually paying the yield?
How long can that borrowing demand last?
What protects lenders' capital when losses occur?
That's why I think the Axiom WBTC Vault is worth a closer look.


One @FalconXGlobal credit facility, three ways to deposit: USDC, cbBTC, and WETH through @paretocredit.
New deposit classes use the existing M11-underwritten FalconX facility. Bitcoin and ETH holders can earn yield in the asset they deposit.
APY is lower than the USDC vault due to basis-risk hedging costs. Monthly cycles and the offchain first-loss layer stay unchanged.
APY, first cycle → current:
cbBTC: 2.22% → 2.32%
WETH: 3.46% → 3.61%
To me, it’s a practical way to attract capital from Bitcoin and ETH holders through an existing facility.

.@FalconXGlobal doubles down on onchain credit by expanding its Structured Credit Facility on Pareto to accept two new deposit assets: cbBTC and WETH.
The flagship USDC vault, curated by @M11Credit, crossed $180m in deposits this year - becoming one of the largest single-borrower credit vaults in DeFi.
The addition of support for cbBTC and WETH builds on that track record.
🧵⬇️
Mahone Defi retweeted

Aave V4 lets external partners run their own lending instances and distribute credit products to their users.
@ether_fi Cash and @SentoraHQ are two early examples, serving different lending needs while sharing revenue with @aave DAO.
🧵,

Mahone Defi retweeted
Ethena Pay launched Earn+, bringing an ~11x leveraged defi strategy into a consumer finance app.
Users can move USD into Earn+ to access a target yield of up to 12% APY, compared to up to 6% on the regular USD Account.
Behind the one-tap experience is a vault running on @aave V4 on @avax.
🧵,

Mahone Defi retweeted
RWA is gaining traction across @aave's lending markets.
$1B+ in RWA-related deposits now sit across V3, V4, and Horizon.
🧵,

Mahone Defi retweeted

.@FalconXGlobal Credit Vault on Pareto is expanding to @base
The move builds on the $180m+ in deposits the vault has attracted on Ethereum and follows the institutional capital that continues to flow onto Base.
Curated by @M11Credit
→ app.pareto.credit/vault/0xC2…
🧵⬇️

Mahone Defi retweeted
RedStone turns 6 today, and it's building the infrastructure to power the RWA decade and the next era of onchain finance.
Six years ago, @redstone_defi started as an oracle focused on solving asset pricing challenges that traditional oracles had yet to address.
From liquid restaking and synthetic dollars to staked Bitcoin and tokenized funds, RedStone has continuously expanded its infrastructure to meet the market's increasingly complex pricing needs.
Today, RedStone secures over $9B in assets across 110+ chains, serving 200+ clients and partners, including @BlackRock BUIDL, @Securitize, @CantonNetwork, and even pre-IPO markets on @HyperliquidX.
But imo, the biggest milestone lies in RedStone's evolution from a price oracle into a broader financial infrastructure stack:
Price: Reliable asset pricing data
Settle: Near-instant liquidity, exits, and liquidations
Risk: Credit risk assessments through @CredoraNetwork ratings
Compliance: Onchain sanctions screening through Sanctions Oracle
Together, these layers lay the foundation for RedStone's next chapter: making tokenized assets liquid, productive, and ready to scale across onchain finance.


Mahone Defi retweeted
ngl, this report gave me a much deeper understanding of tokenized stocks onchain.
There are plenty of valuable findings, but a few insights from @redstone_defi really stood out to me:
1. Perps are still where stocks actually trade
One of the biggest takeaways from RedStone's report is how much equity perp trading dominates the market.
Equity perp volume is roughly 9.9x higher than tokenized stock spot volume.
Even with tokenized stocks surpassing $3B, most onchain trading activity still happens through derivatives rather than spot tokens.
For now, traders seem to value the leverage and liquidity of perps more than holding tokenized shares.
2. After-hours trading is a clear advantage
Around 55% of tokenized stock trading volume happens outside traditional market hours.
Even more impressive, Sunday evening perp prices correctly predicted the direction of Monday's market open around 65% of the time in RedStone's sample.
This is one of the clearest examples of the real utility crypto infrastructure brings to tokenized equities.
3. The defi gap remains huge
Only 2.6% of tokenized stocks are actually being used in DeFi, despite 42% of the supply being technically eligible as collateral.
Most of the collateral usage comes from a handful of smaller markets, while assets from larger issuers barely see meaningful borrowing activity.
This suggests there's still a massive gap between making tokenized stocks available in DeFi and generating real demand for them as collateral.
4. Liquidity and actual ownership are highly fragmented
There are roughly 4.04M holders, but the average balance is only around $780.
Most positions are small, retail-sized holdings concentrated across a limited number of venues.
Meanwhile, many large balances sit in issuer wallets and exchange hot wallets rather than individual investor wallets.
Another detail worth noting: the three largest issuers, accounting for roughly 70% of the market, don't provide direct equity ownership.
Instead, holders typically receive indirect economic exposure or claims backed by underlying shares.
---
The full report goes much deeper into market structure, trading behavior, liquidity fragmentation, and the DeFi adoption gap that RedStone has identified.
If you want to explore the full data and analysis, I'd recommend checking out the report below.

Tokenized stocks total $3.17B+ in onchain value.
Only 2.6% of that is used in DeFi.
Read our latest report with @FourPillarsFP and @AleaResearch, revealed at @TokenizeThisNYC Singapore edition, to learn why.
Features insights from: @Securitize, @DinariGlobal, @SuperstateInc, @extendedapp, @lista_dao, @JupiterExchange, @CredoraNetwork.
Mahone Defi retweeted
imo, one of the most valuable insights from @paretocredit's article is that most real Bitcoin borrowing demand sits in the OTC market, where hedge funds, prime brokers, and financial institutions borrow Bitcoin to support their operations.
Onchain, Bitcoin is mostly used as collateral, leaving lending rates close to zero.
This gap is exactly what credit products like Pareto x Two Prime aim to address, bringing offchain institutional borrowing demand onchain through a more structured credit model.
So what makes this Bitcoin Credit product different from traditional OTC lending and existing onchain markets?
1. Yield backed by institutional credit demand
The vault currently offers around 1.61% net APY, paid in $WBTC.
That's significantly higher than most onchain Bitcoin lending pools, where limited borrowing demand keeps rates near zero.
More importantly, the yield comes from interest paid by institutional borrowers rather than relying on token incentives.
2. Credit structure designed for institutional lending
Rather than operating as a typical lending pool, Pareto structures the vault as a credit facility with defined risk controls.
@Two_Prime puts up 150 WBTC of its own capital as first-loss protection, absorbing credit losses before they reach lenders.
The vault also has monthly redemption cycles and a Credit Agreement outlining lender rights and recovery procedures.
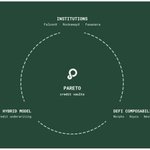
This follows the hybrid onchain + offchain model that Pareto has already demonstrated across its previous Credit Vaults.
3. A new access channel for institutional Bitcoin credit
The product opens institutional Bitcoin credit exposure to eligible lenders holding capital onchain.
Previously, accessing OTC lending opportunities often required direct institutional relationships, with limited flexibility around participation.
By bringing this exposure onchain, Pareto creates another channel for capital allocation beyond traditional OTC relationships.
4. The composability potential of $pAXIOMBTC
For me, this is the strongest advantage of bringing Bitcoin credit onchain.
Unlike traditional OTC positions, the vault's receipt token can potentially be integrated into secondary markets, money markets, or more complex structured DeFi products.
That opens the door for the same Bitcoin credit exposure to gain additional liquidity, distribution, and utility across DeFi.

Mahone Defi retweeted
11 Aave markets ended Q3 with $1.3B+ in deposits and $417M borrowed.
Across V3 and V4, @aave expanded into new chains, consumer credit, and different lending structures.
A few things stood out to me 🧵


Mahone Defi retweeted
My take on the partnership between @redstone_defi and @Brickken:
1. T+0 settlements via Settle could bring the most value to Brickken's ecosystem.
Price feeds and credit ratings are offered by multiple providers, but turning T+N settlement into T+0 liquidity addresses one of RWA's biggest pain points.
Brickken has supported over $660M in tokenized assets, spanning equity, real estate, and energy. Many of these asset classes are traditionally illiquid, with lengthy redemption cycles.
RedStone Settle uses solvers to provide immediate liquidity, while solvers take over the positions and handle redemption.
If executed well, this could unlock more Brickken assets as collateral in defi lending markets.
2. Expanding agent-ready RWAs on Brickken
Brickken already offers APIs, an MCP server, and SDKs that allow AI agents to interact with tokenized assets.
RedStone adds three key infrastructure components:
- Pricing to determine asset valuations.
- @CredoraNetwork to assess credit risk.
- Settle to support exits and liquidations.
Together, these components could help AI agents move beyond executing transactions toward managing RWA positions autonomously.
3. An institutional moat is taking shape
RedStone is expanding vertically across pricing, risk, and settlement rather than competing solely as an oracle provider.
Through Brickken, RedStone gains an opportunity to integrate all three layers with asset issuers from the tokenization stage.
As issuers and lending markets adopt the full stack, switching costs could rise, making the infrastructure harder to replace.
imo, that's where RedStone's long-term institutional moat could emerge, with Settle as its strongest differentiator.

NEW: @Brickken, a tokenization platform with 150+ clients and $660M in tokenized assets, has selected RedStone as its data infrastructure partner.
Brickken-issued assets can now access the full RedStone stack: feeds, T+0 settlement via Settle, and @CredoraNetwork risk ratings, the data layer to enable work in DeFi for RWA's.

Mahone Defi retweeted
Tokenized stocks on @base are finding more use cases in DeFi.
3% USDC incentives to boost tokenized stock deposits on @aave V4
$1.2M in collateral from @superformxyz, bringing automated carry trade strategies to retail users.
🧵,


Aave DAO has approved incentives for the Coinbase Tokenized Stocks market on @base.
Tokenized stocks are only available in eligible jurisdictions outside of the U.S.

Mahone Defi retweeted
By March 2026, tokenized RWAs had grown more than 5x in a year, with private credit alone at ~$4.6B.
Yet only ~$2.8B of the ~$28.6B market was deployed in DeFi.
New research from @LaserDigital_ points to four structural risks behind that gap.
🧵⬇️

Only around $2.8bn of a roughly $28.6bn tokenised RWA market is deployed in DeFi. Our new research on what institutional fixed income needs on-chain: laserdigital.com/latest-insi…
Professional and institutional investors only. Capital at risk. laserdigital.com/marketing-d…


Mahone Defi retweeted

Pretty comprehensive report dropped by @redstone_defi x @FourPillarsFP x @AleaResearch at @TokenizeThisNYC SG around the current state of tokenised stocks.
Beyond the headline figures, the report dives into the evolving market structures, issuer dynamics + the growing role of DeFi in shaping onchain equity markets.
Here are some key takeaways I found particularly interesting 🧵

Tokenized stocks total $3.17B+ in onchain value.
Only 2.6% of that is used in DeFi.
Read our latest report with @FourPillarsFP and @AleaResearch, revealed at @TokenizeThisNYC Singapore edition, to learn why.
Features insights from: @Securitize, @DinariGlobal, @SuperstateInc, @extendedapp, @lista_dao, @JupiterExchange, @CredoraNetwork.

Mahone Defi retweeted
ngl, keeping up with hundreds of sanctions lists is a headache for defi teams.
so @redstone_defi built a Sanctions Oracle that lets protocols screen wallet addresses against 463 sources covering OFAC, UN, EU, and other sanctions lists through a single onchain check.
protocols can query the oracle during a transaction and revert if an address is flagged, embedding sanctions screening directly into the execution flow.
updates are pushed onchain weekly with a timestamp, so protocols can set limits on how old the screening data can be.
the contract also uses the same interface as Chainalysis’ sanctions oracle, simplifying integration for protocols already using that interface.
potential use cases include:
- stablecoin issuers
- tokenized funds
- lending protocols
- permissioned pools
imo, the key shift is making sanctions screening part of how a protocol operates.
for institutional, that means access rules can be enforced directly by smart contracts at execution time.


Mahone Defi retweeted
Downside protection matters, especially when institutional bitcoin is earning yield.
In the Two Prime Credit Vault on Pareto, 150 WBTC of @Two_Prime's own capital sits in first loss.
Backed by a clean record across 3,000+ BTC lent.
app.pareto.credit/vault/0xD1…

