

Father of 4. Owner of Meredith Wealth Planning, a flat fee financial planning firm that manages over $550 million for 200+ clients.
Maryville, IL
Joined March 2012
- Tweets3.3K
- Following244
- Followers2.9K
- Likes15K
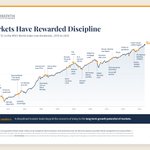




From 1980-2025 the S&P 500 averaged a 14.2% decline at least once per year.
Despite that, every time it happens there are tens of millions of people who have been investing in equities for decades that are quite surprised by it.

The first $609,814,032 is the hardest.


Today we crossed the half a billion milestone. Taking @wimms5987 out for a $4 cheeseburger to celebrate.

12
87
9,526
1/Why do some "expensive" stocks land a spot in Avantis' value focused portfolios like $AVLV?
5/Look at both together and the distortions are largely canceled out. The company may look expensive on one measure but highly profitable on the other.
That's why many factor-based strategies use profitability and value instead of relying on either one by itself.
2
6
798
So many old friendships are rekindled on days like this:
"Hey man I know we haven't talked since Douglas Hall at EIU but you work in finance right? Can you tell me what is happening to TQQQ?"
The AI tool, Iris, built inside @RightCapitalHQ is really good and keeps improving.
2
16
3,667
It always amuses me when local banks heavily advertise “CD specials” that are substantially below equivalent US Treasury rates, even before accounting for state income tax savings.
My entire “for you” feed is filled with “everyone will lose their job to AI”, “nothing is secure anymore”, and “SPCX will do $1 trillion in 2027 revenue”.
Time to walk outside barefoot for a while.
1
23
1,575
In the past we have brought on clients with very large American Fund portfolios in taxable accounts.
Simply doing a tax-free share class conversion from their "A" share class to the "F-3" share class more than paid for our entire annual advisory fee.
The cap gain distribution tax nightmare from legacy American Funds never ends.
The Growth Fund of America is estimating 10% - 12% in LT gain distributions while American Balanced is estimating 12% - 15%.
The New Economy Fund takes the cake at a 20% - 25% estimate.
When prospective clients upload documents to us we are starting to see a lot of “AI generated financial plans” included.
These plans of course have brought no confidence or clarity to them, which is why they are reaching out to a real financial planner.
Mark Meredith, CFP®️ retweeted

Here’s what many miss:
During peak family years demands on your time are insane and give rise to fantasizing about optionality.
Then the kids grow up, begin lives of their own, and suddenly things get very quiet. That’s when things flip. Friends who retired early are bored and often end up doing dopey things trying to occupy their time. Those who stayed in the game wake up with purpose, stay engaged and avoid dopey destructive behaviors. It’s all about moving gracefully through the stages of life. To my friends in peak insane family years, take a moment to soak it all in. It will pass quickly and someday you’ll give anything to experience it one last time. 👊
Mark Meredith, CFP®️ retweeted
You’re right. That’s why the larger the “safe” allocation one has in their portfolio, the less sustainable higher withdrawal rates are over time (historically).

Sharing an example of the investment policy statement we use for clients.
meredithwealth.com/sample-in…