

A decade lost in the stock market. Quantitative developer at BNY, ex-CRISIL, ex-Edelweiss
Pune, Maharashtra
Joined March 2014
- Tweets2.2K
- Following105
- Followers2.2K
- Likes714






Amanta Healthcare is now in unexplored territory. 🚀🚀
16% Up.


Why Amanta Healthcare?? My investment thesis
Amanta Healthcare is a sterile pharma company specializing in IV fluids, injectables, respiratory and ophthalmic products. Its key differentiator is SteriPort, a premium two-port IV bottle platform that contributes ~42% of revenue.
1️⃣ SteriPort is the real story
Amanta pioneered ISBM-based polypropylene IV bottles in India.
Today, SteriPort contributes ~42% of revenue and is preferred in oncology, ICU, pediatrics and critical care due to lower contamination risk.
Current utilization is at 96%; that itself means the product is in demand.
2️⃣ Capacity expansion is about to go live
SteriPort capacity is increasing from:
📈 6.6 Cr bottles ➝ 11.6 Cr bottles
Management expects commercial production to start by June 2026.
3️⃣ This single expansion can be transformative
Management expects:
💰 Additional revenue: ₹110-120 Cr annually
Production is starting in June; that means it will add 80-90 Cr in revenue.
Against FY26 revenue of ₹288 Cr, that's nearly 30% incremental revenue potential from one project alone.
4️⃣ Margins should improve
Current EBITDA Margin: 22%
New SteriPort line EBITDA Margin: 26-27% (New line in same place results in efficiency.)
Management is guiding for 25%+ company-level EBITDA margins over the next few years. Current is 22%.
5️⃣ Solar project adds another tailwind
A 10.8 MW captive solar plant is being commissioned.
Expected annual savings:
⚡ ~₹9 Cr
Direct boost to profitability without requiring additional sales.
6️⃣ Balance sheet has improved significantly
Debt/Equity:
FY23: 3.43x ➡️ FY26: 1.06x
Finance costs are falling and management expects further refinancing benefits.
➡️ Finance costs likely to fall further as debt reduced from ₹234 Cr to ₹204 Cr, ~90% of borrowings are now at single-digit rates, and management plans to refinance another ₹30-40 Cr of debt at lower costs.
7️⃣ PAT is growing much faster than revenue
FY26:
Revenue growth: +5%
PAT growth: +42%
A sign that operating leverage and lower interest costs are starting to kick in.
8️⃣ Next growth engine already under development
The company has:
✅ 20 products in pipeline
Focus areas:
👁️ Ophthalmics
🌬️ Inhalation therapies
💊 Specialty sterile formulations
These are typically higher-margin categories.
9️⃣ The investment thesis
This isn't a bet on IV fluids.
It's a bet that Amanta can transform from a commodity IV-fluid manufacturer into a higher-margin sterile pharma company through:
• SteriPort expansion
• Product mix improvement
• Solar-led cost savings
• Export growth
• Deleveraging
The next 12-24 months could be the most important phase in the company's history.
#AmantaHealthcare
#Pharma #Healthcare #Oncology
DYOR!!

Ramayana – First Day Review 🎬
The Good 👍
• The scale is massive. Production quality is phenomenal, and the VFX are top-notch. Not once does the movie feel visually underwhelming.
• All actors have done justice to their roles.
• Loved the execution of Ravana’s transformation into the Ravana we know. Every Ravana scene just works.
• They’ve given time to important events, allowing the audience to absorb the essence of the story.
The Bad 👎
• Despite all the grandeur, several scenes lack soul. Especially the emotional moments involving Ram, which could have been much more powerful.
• The Ram–Kaikeyi sequence needed better build-up. Kaikeyi’s emotional shift and the reasons behind her decision to send Ram into Vanvas weren’t articulated well enough. A few other important events also lacked proper context.
• The storytelling is good, but the delivery could have been much better. Some moments that should have hit hard end up feeling just okay.
Overall Verdict 🎬
The last sequence is simply breathtaking. You will want to applaud it! And the way the movie ends will leave you eagerly waiting for the next part.
It makes you feel that the entire journey was worth your time.
Could it have been better? Absolutely. But considering the scale of the project and the director’s first attempt at something this massive, I appreciate the effort and conviction.
Not brilliantly executed, but a good effort overall.
A thumbs up from me! 👍
550

Allways super exciting to hear @Amit_Jeswani1 ❤️

Had a fantastic conversation with @Nigel__DSouza on @CNBCTV18News . Thank you for having me on your show! 🙏
India’s biggest wealth creation story is still ahead of us! 🇮🇳
The next decade will create extraordinary opportunities for investors just remember the formula - SD WH TB (You will know about it in the Video)
The future belongs to the optimists! 🚀
PS: Ofcourse Stocks are not recommendations!
2
524
Balu forge - Capacity and capability!
Lets see how long market will ignore it.👀

Shree Pushkar firing all cylinders in all front.
Though i sold it to buy Shera.

Which stock do you have the highest conviction in - one that you think most people are unaware of?
I will start with mine - Shree pushkar chemical.
Reason - Because of high Phosphate prices farmers demand will shift from DAP(high phosphate content) to NPK(low phosphate content) and additional capacity to go live in near future.
#smallcap
1
352


Krishna Defence and Shree Refrigerations 🎯

🚨 𝗠𝗘𝗚𝗔 ₹𝟱𝟯,𝟴𝟲𝟲.𝟱𝟬 𝗖𝗥𝗢𝗥𝗘 𝗪𝗔𝗥𝗦𝗛𝗜𝗣 𝗖𝗢𝗡𝗧𝗥𝗔𝗖𝗧 𝗙𝗜𝗡𝗔𝗟𝗟𝗬 𝗦𝗜𝗚𝗡𝗘𝗗 𝗙𝗢𝗥 𝗞𝗢𝗟𝗞𝗔𝗧𝗔’𝗦 𝗚𝗥𝗦𝗘! ⚓🇮🇳
The 𝗠𝗶𝗻𝗶𝘀𝘁𝗿𝘆 𝗼𝗳 𝗗𝗲𝗳𝗲𝗻𝗰𝗲 has formally signed contracts worth ₹𝟱𝟯,𝟴𝟲𝟲.𝟱𝟬 𝗰𝗿𝗼𝗿𝗲 with 𝗚𝗮𝗿𝗱𝗲𝗻 𝗥𝗲𝗮𝗰𝗵 𝗦𝗵𝗶𝗽𝗯𝘂𝗶𝗹𝗱𝗲𝗿𝘀 & 𝗘𝗻𝗴𝗶𝗻𝗲𝗲𝗿𝘀 (𝗚𝗥𝗦𝗘), 𝗞𝗼𝗹𝗸𝗮𝘁𝗮, and 𝗚𝗼𝗮 𝗦𝗵𝗶𝗽𝘆𝗮𝗿𝗱 𝗟𝗶𝗺𝗶𝘁𝗲𝗱 (𝗚𝗦𝗟) for the construction of 𝟴 𝗡𝗲𝘅𝘁 𝗚𝗲𝗻𝗲𝗿𝗮𝘁𝗶𝗼𝗻 𝗖𝗼𝗿𝘃𝗲𝘁𝘁𝗲𝘀 for the Indian Navy. Under the project, 𝗚𝗥𝗦𝗘 𝘄𝗶𝗹𝗹 𝗯𝘂𝗶𝗹𝗱 𝟱 𝘄𝗮𝗿𝘀𝗵𝗶𝗽𝘀, while GSL will construct the remaining three.
A massive milestone for Kolkata’s shipbuilding industry and India's indigenous defence manufacturing ecosystem. The project is expected to generate 𝟱𝟯𝟮 𝗹𝗮𝗸𝗵 𝗽𝗲𝗿𝘀𝗼𝗻-𝗱𝗮𝘆𝘀 𝗼𝗳 𝗲𝗺𝗽𝗹𝗼𝘆𝗺𝗲𝗻𝘁 over the next decade, strengthening domestic shipbuilding capabilities and creating a significant industrial opportunity for the country. 🇮🇳
#GRSE #Kolkata #WestBengal #IndianNavy #GSL #DefenceManufacturing #Warships #MakeInIndia #Shipbuilding #Infrastructure


Blockbuster results by Shera Energy.
PAT 100% up in H1 at 30 Cr.
Q2 PAT is 17 Cr in comparison with 8Cr last year.
Margins is going to improve further.
Atleast 60 Cr PAT loading for the full year.

I am back.
Portfolio update:
1. Bought Shera Energy
-Copper, Aluminium and Brass recycling
- Zambia Copper cathode plant is about to commission ( Major margin expansion trigger)
- Entry into CTC (continuously transposed conductor) for EHV/765kV transformers - import substitute (only handfull of companies make it in india)
- Nickel Iron Alloy - will be very interesting if they able to make aerospace level grade alloy
I can see lot of triggers for re-rating.
Most important: Company is very much focused on cash generation from business.
Where i am bit cautious: Debt to equity ratio is high and company will increase the ratio to expand the copper cathode plant once the first phase is successful.
Keeping an eye if margins are increasing to accommodate interest and depreciation cost.
2. Trimmed/Sold
BHEL - Sold
Skygold - Trimmed 25%
Fedfina - Trimmed 40%
Frontier spring - Exited remaining quantities
Websolar - Exited remaining quantities
Shree pushkar - Sold
V2 Retail - Sold
I had to sell these to buy Shera not because i dont like these business.
Do your own analysis. Not a recommendation!!

2
3
649
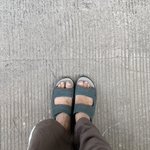
Tried my first product from @frido_official, and honestly, already regretting the purchase.
The product keeps slipping off my feet while walking. I have to tighten the straps excessively just to keep them in place, which makes it extremely uncomfortable to use.
Kya bawasir bana diya hai bhai @ganeshsonawane? 😖

376
Ganesha Ecoshere Q2 out - Great results.

Portfolio Update:
♻️ Added Ganesh Ecosphere - Recycling play
FY27 Management Targets:
Consolidated EBITDA guided at 225 Cr – 250 Cr.
FY27 PAT should be at least 3x of FY26
Caught your attention? Let's read the thesis.
India’s PET recycling industry is seeing a shift towards higher-value, food-grade rPET granules, driven by rising demand and stricter recycled-content regulations.
🏭 A major business transformation [capacity and capability]
• VAP revenue share targeted to rise from ~40% to ~65%
• Totak capacity: 218,940 MTPA
• Warangal capacity: 100,140 MTPA [Margin accertive]
• Utilisation guided to increase from 72% in Q1 FY27 to ~85% by year-end
🛡️ Competitive advantage
300+ suppliers collecting ~450 tonnes of PET bottles daily, backed by a 49:51 JV with Race Eco Chain.
USFDA, EFSA and FSSAI approvals strengthen its position in food-contact packaging.
🚀 Regulatory tailwinds
Mandatory recycled content in rigid plastic packaging is moving from 30% in FY26 to 40% in FY27.
Meanwhile, India’s PET bottle production is projected to grow from 1.3M MT in CY24 to 2.3M MT by CY29.
This story is going to be interesting to unfold.
Not an investment advisor, DYOR!!
1
343
RamKrishna Forging posted a great Q2 result. The story is playing out well.

Portfolio Update:
1) Added Ramkrishna Forgings - worst is behind. Bottom line should grow faster than the top line going forward. Bullish on the concall.
2) Shilpa Medicare - Investment is done. The future looks optimistic. Bullish on the concall.
Still learning about biologics, molecules, peptides, CDMO, APIs, etc. from some of the best in the field:
@unseenvalue @AdityaKhemka5
Buying in tranches.
DYOR!!!
352
Patels Airtemp Q2 results look good.

Portfolio Update:
Added Patels Airtemp
What's interesting:
“Small company, outsized order” market story
1. A 200 Cr market-cap company booked a 226 Cr order (execution in the next 12 months) from Dangote’s Nigeria refinery, on top of a 295 Cr book.
2. Expansion going on: Target capacity for vessels and heat exchangers: 200 MT → 350 MT
Products:
✨Air-cooled heat exchangers / Air-fin coolers
✨Shell & tube heat exchangers
✨Shell & fin-tube heat exchangers
✨Pressure vessels and columns
✨Ambient air heaters (LNG / cryogen heating)
✨Air-cooled condensers
✨AC & refrigeration equipment; some turnkey HVAC
Industry serving: Oil & gas, refineries, pharma, and thermal & nuclear power.
Deepak Nitrite showing evidence.
Banger result in all front.
Revenue +61.7% YOY
PAT +234.9% YOY

Portfolio update:
Sold half of Aimtron holding at 3X
Reason: man ki shanti, i think valuations is streched and it is out of comfort for me to hold a large position here.
But who knows how much valuations can be stretched given the company is doing really great. Let the other half ride if there is more in the pocket.
Most of the good companies are now trading at higher valuations.
Reading companies which are out of favour but management is still kicking behind the numbers.
In radar:
1. Deepak Nitrite
2. S&S switchgear
3. Samaan capital
4. Praj industry
2
810
Read the comments on this post. What kind of PR campaign is being run against India that is making Americans think of India as an enemy?

Great meeting with Indian Minister of Defence Singh.
We celebrated the one-year anniversary of the Framework for our Major Defense Partnership and explored ways to strengthen cooperation.

1
711
Portfolio Update:
♻️ Added Ganesh Ecosphere - Recycling play
FY27 Management Targets:
Consolidated EBITDA guided at 225 Cr – 250 Cr.
FY27 PAT should be at least 3x of FY26
Caught your attention? Let's read the thesis.
India’s PET recycling industry is seeing a shift towards higher-value, food-grade rPET granules, driven by rising demand and stricter recycled-content regulations.
🏭 A major business transformation [capacity and capability]
• VAP revenue share targeted to rise from ~40% to ~65%
• Totak capacity: 218,940 MTPA
• Warangal capacity: 100,140 MTPA [Margin accertive]
• Utilisation guided to increase from 72% in Q1 FY27 to ~85% by year-end
🛡️ Competitive advantage
300+ suppliers collecting ~450 tonnes of PET bottles daily, backed by a 49:51 JV with Race Eco Chain.
USFDA, EFSA and FSSAI approvals strengthen its position in food-contact packaging.
🚀 Regulatory tailwinds
Mandatory recycled content in rigid plastic packaging is moving from 30% in FY26 to 40% in FY27.
Meanwhile, India’s PET bottle production is projected to grow from 1.3M MT in CY24 to 2.3M MT by CY29.
This story is going to be interesting to unfold.
Not an investment advisor, DYOR!!
Shera Energy - Best ever H1, Crossed 1000 Cr Revenue
Margin expansion will be key to watch.
DYOR!!

I am back.
Portfolio update:
1. Bought Shera Energy
-Copper, Aluminium and Brass recycling
- Zambia Copper cathode plant is about to commission ( Major margin expansion trigger)
- Entry into CTC (continuously transposed conductor) for EHV/765kV transformers - import substitute (only handfull of companies make it in india)
- Nickel Iron Alloy - will be very interesting if they able to make aerospace level grade alloy
I can see lot of triggers for re-rating.
Most important: Company is very much focused on cash generation from business.
Where i am bit cautious: Debt to equity ratio is high and company will increase the ratio to expand the copper cathode plant once the first phase is successful.
Keeping an eye if margins are increasing to accommodate interest and depreciation cost.
2. Trimmed/Sold
BHEL - Sold
Skygold - Trimmed 25%
Fedfina - Trimmed 40%
Frontier spring - Exited remaining quantities
Websolar - Exited remaining quantities
Shree pushkar - Sold
V2 Retail - Sold
I had to sell these to buy Shera not because i dont like these business.
Do your own analysis. Not a recommendation!!
3
10
1,738