Helping bond investors find what's rich or cheap, and why. Macro, rates & MBS today. Munis, ABS & corporates next.
San Francisco Bay Area
Joined September 2026
- Tweets99
- Following90
- Followers62
- Likes260
Pinned Tweet
We're live!

Today, I'm excited to bring @OasiveAI out of stealth and announce that we're backed by @ycombinator!
Oasive helps bond investors find better bonds to buy.
Uncover opportunities you might otherwise miss, compare investments and test the risks before putting on a trade.
Which Treasury maturities look cheap? Is there a curve trade worth putting on? Macro and Rates Research helps you explore both. In mortgage-backed securities (MBS), compare pools and see how changes in rates and prepayments affect your portfolio.
Our AI analysts bring the research and proprietary models together, so you can go from idea to decision in minutes.
Thank you to @kul and @garrytan for taking a chance on me and believing in @OasiveAI!
Start your Macro and Rates Research free trial or request an MBS demo: oasive.ai/join
Here's what you can do 👇
Oasive (YC F26) retweeted

US factories are hiring at the fastest pace since March 2012!
October's flash PMI showed backlogs of unfinished work growing the most since May 2022 in both manufacturing and services.
Selling prices also rose at the fastest pace since August 2022 (no surprises there...)
We continue to see more demand and inflation pressure going into the Fed meeting next week.
From @OasiveAI 👇

Oasive (YC F26) retweeted
Americans are pulling back on big purchases.
In October, the University of Michigan survey measure of whether it's a good time to buy big house items like furniture and appliances fell 18% which pretty much drove the whole drop in expectations.
The reasons? higher interest rates & affordability!
Overall sentiment barely moved at 48. 1y inflation expectations rose to 4.7%, the highest since May.
From @OasiveAI 👇

Oasive (YC F26) retweeted
Yesterday's market moves in a summary:
📈 Up: government bonds, consumer staples, homebuilders and oil
📉 Down: tech, gold, silver and riskier corporate bonds
Oil hit its highest price since May on attacks in the Gulf. Higher oil -> higher inflation. The Fed meets next week so the minutes will give good indication if the market is pricing December hike right.
Full breakdown in today's @OasiveAI

Oasive (YC F26) retweeted
Thursday's rally was a classic risk-off move: the 5y led the move (-20.4bp) and the 30y lagged a bit (-15.2bp).
Real yields did the work: 5y TIPS -22bp to 2.33% while breakevens rose 5bp. Investors were looking for safety, inflation expectations stayed unchanged.

Big day for US Treasuries yesterday! The 10-year yield fell back below 5%, its biggest one-day drop in more than 2 years.
The trigger was AI spending. Meta raised its 2026 spending plan to $135-145B and its stock fell 7% while the Nasdaq lost 2.6% though the Dow and Russell 2000 held up.
Markets still expect the Fed to raise rates in December, just a little less than before. Futures cut the odds of a December hike from 89% to 77%.
More in today's @OasiveAI market wrap

Oasive (YC F26) retweeted
Big day for US Treasuries yesterday! The 10-year yield fell back below 5%, its biggest one-day drop in more than 2 years.
The trigger was AI spending. Meta raised its 2026 spending plan to $135-145B and its stock fell 7% while the Nasdaq lost 2.6% though the Dow and Russell 2000 held up.
Markets still expect the Fed to raise rates in December, just a little less than before. Futures cut the odds of a December hike from 89% to 77%.
More in today's @OasiveAI market wrap
Check out our report on the economic situation in France!
Since I'm French, everyone keeps asking me what's going on in France. So I asked @OasiveAI to lay out the facts.
> The OAT-Bund 10y spread closed at 171bp today, the widest since 2011. France now yields about 45bp more than Italy!
> The protests and the bond selloff have the same cause: a deficit near 5% of GDP that a minority government can't cut.
> The stress is mostly contained to France. The OAT 10y is up 157bp YTD vs 53bp for the Bund. But it's reaching the front end. The 2y spread over Germany went from 47bp to 78bp in one week.

Oasive (YC F26) retweeted
Since I'm French, everyone keeps asking me what's going on in France. So I asked @OasiveAI to lay out the facts.
> The OAT-Bund 10y spread closed at 171bp today, the widest since 2011. France now yields about 45bp more than Italy!
> The protests and the bond selloff have the same cause: a deficit near 5% of GDP that a minority government can't cut.
> The stress is mostly contained to France. The OAT 10y is up 157bp YTD vs 53bp for the Bund. But it's reaching the front end. The 2y spread over Germany went from 47bp to 78bp in one week.
Oasive (YC F26) retweeted
Layoffs are low, but hiring has almost stalled.
Initial claims fell to 194K last week. The 4w average is 198K, its lowest in a year and down from 227K last Nov.
Payrolls rose just 29K in Sep. They're up 496K over the past year, about 41K a month.
Employers aren't cutting, but they're barely adding. That keeps unemployment steady, but it makes finding a new job harder.
Charts from @OasiveAI

Oasive (YC F26) retweeted
> Yesterday, a narrow AI rally lifted stocks. The S&P 500 rose 0.58% and the Nasdaq 1.05%, led by SpaceX and Nvidia.
> Treasuries sold off, led by the belly. The 10y closed at 5.146%, up 2.9bp. The 20y auction cleared at 5.469%, the highest since 2020.
> Rates vol still dropped! MOVE fell 5.8 points, mostly in the first hour.
> Credit split: HY tightened 6bp, while IG widened 1bp to 88bp.
Today the mood has flipped. Meta's comments on AI funding and reports of strikes on Iran are pushing money into Treasuries. The 10y is near 5.02%.
More in today's @OasiveAI daily macro update.

Oasive (YC F26) retweeted
Yesterday's 20y auction cleared at 5.469%. That's the highest 20y auction yield since they resumed in 2020, and up about 27bp in two months.
Demand still showed up. Bid-to-cover rose to 2.73 from 2.57 in Sep. Directs took 31.6%, their biggest share since 2020. Dealers were left with just 10.3%.
Higher yields are pulling buyers in.
Trend analysis by Oasive 👇

Oasive (YC F26) retweeted
The long end got some relief yesterday. The 30y yield fell 4.7 bp to 5.425%, about 2σ more than @OasiveAI’s cross-asset model would expect given moves in the rest of the curve and equities.
The 2y rose 2 bp, flattening the curve.
At 10y, the rally came entirely from real yields. The TIPS yield fell 3 bp to 2.77%, while market inflation expectations were unchanged, with the breakeven holding at 2.35%. The 10y SOFR swap rate was unchanged too, so Treasuries outperformed swaps.
The concern seems to be weaker growth, while inflation expectations haven’t budged.

Oasive (YC F26) retweeted
Stocks had a better day outside tech yesterday: Dow +1%, Russell 2000 +1.7% while Nasdaq flat. Earnings and cheaper oil helped, even as housing data weakened.
Long bonds rallied too, but the 2y yield still rose. A Fed pause next week is likely with a hike priced in at the Dec meeting.
From @OasiveAI's daily market update

Oasive can break down anything for research!
September housing starts had a big miss, with both single- and multi-family construction falling. I asked @OasiveAI to break down the print:
> single-family starts -4.6% m/m, a 1y low, and permits -4% m/m (lowest since March 2023), a worrying signal for future construction
> multi-family starts (5+ units) -7.2% m/m, lowest since May
> regionally: total starts in the South are up +11% y/y, whereas the West (-25%) and Northeast (-31%) are the weakest
Fewer homes are being started, and completions are already down 14% y/y. Less new supply could help support prices, but only if buyers are still there. It also points to less spending on homebuilding.
Oasive (YC F26) retweeted
@OasiveAI’s daily market update for yesterday:
> Chips led a narrow relief rally: Nasdaq +1.11%, S&P 500 +0.41%, while the Dow slipped.
> Treasuries gave back about a quarter of last week’s rally. The 10y rose 3.8 bp to 5.136%, with breakevens flat. Real yields drove the move.
> The Fed is in blackout, with a hold priced for Oct 28.
> This morning’s sharp housing-starts miss has the 10y back below 5.10%.

🔥
You can now ask @OasiveAI questions about your MBS portfolio in natural language, rank your holdings by specific characteristics, and build portfolios through the same chat.
Here’s a quick demo of me using it to identify the pools with the most extension risk and see their P&L alongside the risk analysis 👇
Oasive (YC F26) retweeted
Builder sentiment hit a 14y low... and more builders are cutting prices as buyer traffic falls.
@OasiveAI’s breakdown of October’s NAHB data shows > 43% of builders cutting prices, up from 38%
> 65% offering incentives
> confidence fell to 29, lowest since June 2012
> buyer traffic down 5 points to 18
The outlook is getting worse too: sales expectations fell to 32 from 54 just a year ago.
Mortgage rates rose from 6.65% in August to 7.40% so even even listing prices are lower, buyers still have to pay the monthly payment

Oasive (YC F26) retweeted
Bonds were a useful hedge to stocks this past week. A reliable hedge though? Still too soon to say.
Stock-bond correlation is still +0.34 over 60 days, almost identical to its 1y norm of +0.33 (they still tend to move together)
Last week’s biggest surprises vs the @OasiveAI cross-asset performance model:
> Oil: 10 ppts stronger than expected
> Rate vol: 10 points higher than expected
> Nasdaq: 0.9 ppt weaker than expected

Oasive (YC F26) retweeted
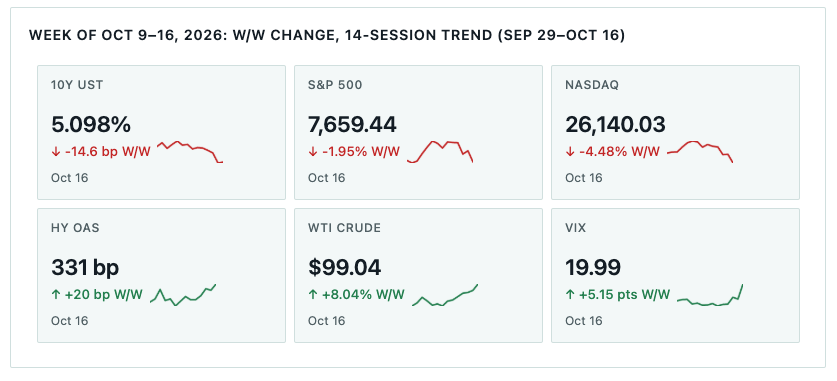
What happened last week in the market?
AI debt fears hit tech. Oil kept climbing. A rough week for markets!
> Nasdaq -4.5% (worst drop since June), S&P 500 -2%, VIX hit 20
> WTI oil +8% on middle east tensions
> Treasury yields fell: 10y -15bp, 30y -16bp and HY spreads widened +20bp
> Energy pushed inflation higher. Markets still pricing 85% chance of a Fed hike by December with no pushback from Warsh before the blackout
Get your market update in your mailbox daily with @OasiveAI!