

A global search for value investment opportunities. https://nitter.gq/t.co/j1UIABgRE1
Joined August 2010
- Tweets3.6K
- Following1.3K
- Followers4.8K
- Likes10.6K




Pinned Tweet
Following up on this, I posted an in-depth cover of why BTG's ROE went up, which businesses have received the most capital, and whether the company can keep earning the same returns going forward. Interesting read if you follow Brazil but also as an exercise in bank dissection.


Some thoughts on multiples, growth, and capital allocation from an exploratory analysis of BTG Pactual.

10
2,395
Not saying it's fishy, but the level of disclosure at Nu has to be one of the lowest in any bank I have seen. By Brazilian disclosure standards, it's basically a black box. I understand sharing info can harm them competitively, but they are a public company.
1
16
1,449
This is basically true for every Latin American country. The problem is people think when right-wing wins it means the country is on its way to Singapore, and when the left wins, it's on its way to Weimar. None are true, neither in degree nor length.


The famous Nolan interview with a Chinese reporter, on TV at 10pm on a Thursday in a convenience store in Beijing

2
4
917
Quipus Capital retweeted

As someone who plans to be investing for the next 50 years, I prefer physical moats over intangible moats.
Intangible moats are unbelievably lucrative, but also prone to overpricing and catastrophe risk.
"Search" was the best business model ever created... until it wasn't. Could conceivably be worth zero in 30 years.
Compare this to something like a rock quarry, purchased at 70% of book value and a normalized, long-term 12% ROE.
The rock quarry is near certain to provide a long term return greater than 12%, as the buyer at 70% of BV is likely paying less than intrinsic value.
Physical moats will occasionally trade at these kinds of prices while still intact. And their runway is more easily understandable.
My limited, and anecdotal experience has been that intangible moats rarely get priced in the single digits as their qualitative metrics are so strong.
Some Latam is getting ridiculously cheap (not Brazil in this case):
- Bank with the highest ROA I have seen. It can earn a 25% ROE at LSD leverage
- Very niche lending market with high process moat
- Growing at 15% clips
- 45% payout ratio
- 6x NTM earnings
Our company promotes its services using several marketing methods, including: (i) putting a speaker on top of a car and going around blasting our services on the clients' neighborhoods.

1
11
1,312
Another such example is $CCU. Volumes in Argentina -7.5% YoY, and the company cannot pass pricing above inflation, but revenues in Chilean Peso (CLP) are up 16% because the ARS appreciated versus the CLP.
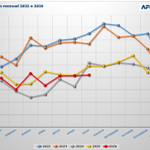
$LOMA is always a good illustration of what's wrong with Argentina's economy. They sell less and less cement (volumes never recover), margins contract, and yet they post higher USD earnings because of the effective appreciation of the Peso.
Pic: Arg monthly cement dispatches


$LOMA is always a good illustration of what's wrong with Argentina's economy. They sell less and less cement (volumes never recover), margins contract, and yet they post higher USD earnings because of the effective appreciation of the Peso.
Pic: Arg monthly cement dispatches
Anyone following $DIBS, not saying it's cheap at all (I recommended it back at $2.7 when it literally traded for cash) but it is an interesting improvement story, and an interesting exposure to the K-shaped economy.
2
5
766
In Brazil, letting your money grow in a time deposit has beaten the S&P500 (I guess ex dividends), even considering the BRL depreciation of the past 30 years.


1
10
1,509
$PPC results last week were pretty horrible. The company is already priced below 10 times cycle average earnings (adjusted for current capital).
2
598
$ULH jumped 35% after earnings. The business is not improving, but they recorded a huge non-recurring gain from the sale of property to a related party. Just skimming through the earnings release can confirm this. Is the market only made of algos?
1
574
Very interesting. The LTCM blowup led the FED to lower rates despite a very strong economy in 1998. This was probably a contributing factor to the mania phase of the dotcom bubble in 1999.


Finquirk of the day: Under Mexican GAAP, a company can still recognize AuM on its balance sheet even if it's not a deposit. This leads to some Mexican brokers reaching 50x Assets/Equity. Biutiful
3
541
Same company. Reports 1Q26, fails to update years to 2026/25, tab name is 'Fourth Quarter 2012'.
Noice!


1
797