

Trusted M&A advisor helping SMB owners sell—and buyers acquire. Exit planning, maximize value, acquisitions, deal execution. BC + Canada.
Vancouver, British Columbia
Joined January 2012
- Tweets346
- Following132
- Followers155
- Likes129



Pinned Tweet
SMB Seller Readiness Checklist (BC/Canada)
Thinking about selling your business in BC/Canada (now or in the next 1–3 years)?
You’ve likely poured years into building something that supports your family, your team, and your customers. A strong exit isn’t just about getting a good price — it’s about selling with confidence, protecting what you’ve built, and setting up your next chapter.
The difference between a smooth, respectful process and a stressful one is rarely luck. Most deals don’t break on price — they break on surprises: unclear add-backs, owner-dependence, customer concentration, and undocumented operations.
A great exit is built 12–36 months before you go to market.
Here’s a quick Seller Readiness Checklist to help you assess where you stand in 7 key areas and focus on the highest‑impact improvements before a sale:
1) Financials and reporting
• Clean financial statements (at least the last 3 years) and up-to-date YTD results
• Normalized earnings: clear, supportable add-backs (owner perks, one-time, and non-operational items)
• Simple KPI dashboard: revenue, gross margin, EBITDA, customer concentration, backlog/pipeline (where relevant)
2) Owner dependence and management bench
• Can the business run without you day-to-day?
• Key roles documented (GM/ops, sales, finance/admin)
• Incentives / retention plan for key people (especially post-close)
3) Customer and revenue quality
• Customer concentration understood and managed
• Recurring/contracted revenue is clear (terms, renewal risk)
• Clean A/R aging, low disputes, consistent collections
4) Operations and “transferability”
• Documented processes (sales, delivery/ops, hiring, finance)
• Systems are stable (accounting, CRM, job/project tracking)
• Vendor/supplier dependencies identified (and mitigations in place)
5) Legal and risk items
• Proper contracts in place (customers, employees/contractors, leases)
• Clean corporate records + IP/brand ownership where applicable
• Known risks surfaced early (regulatory, pending disputes, warranty/claims)
6) Story and positioning
• Clear “why buy this business?” narrative
• Credible growth opportunities (not just hope)
• Buyer profile fit: strategic, financial, operator/buyer — and what each will value
7) Timing and structure
• Your ideal timeline (sell now vs. 1–3 years)
• Tax + structure considerations (asset vs share, working capital expectations, etc.)
• Plan for what you want after the sale (role, transition period, earn-out tolerance)
The above checklist is a good starting point for your planning, but it's just a beginning.
If you’re an owner thinking “maybe in the next 1–3 years”, my DMs are open. Happy to compare notes on what typically builds confidence, improves value, and helps protect your legacy — no pressure.
— Ross
#BusinessExit #ExitPlanning #SuccessionPlanning #BusinessSale #MAndA

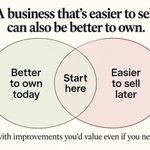
Some of the work that makes a business easier to sell is worth doing even if you keep it.
Profitability by customer or job is a good example.
You may know which customers send the most work, but have less visibility into what it costs to serve them. Looking at the labour, materials and other costs involved can help you decide which work to pursue, how to price it, and where something needs to change.
A future buyer can use the same records to assess how much of the profit is likely to continue under new ownership.
@CFIBNews' October report "Passing the Torch: How Canada's Small Business Owners Are Planning Their Exit and Why the Next Generation of Ownership Matters," written by Marvin Cruz and Laure-Anna Bomal, found that 47% of owners cited finding a buyer or suitable successor as a challenge. Finding someone to take over deserves attention well before you’re ready to leave.
Before committing time or money to a preparation project, ask:
• What operating decision or problem would this help me with now?
• What would it make easier for someone taking over later?
Other steps may depend on whether you eventually sell, transfer to family or employees, or keep the business. You can decide on those when the path is clearer.
I’d start with an improvement you’d be glad you made even if a sale never happened.
What have you changed that made your business easier to run and would also help someone taking it over?
Source: cfib-fcei.ca/en/research-eco…

2
1
61
A buyer can be comfortable with your earnings and still hesitate over your lease.
Think of a workshop with specialist equipment, an established layout and a location that works for its customers.
Moving could mean dismantling equipment, building out another space and losing production time. A buyer needs to know whether the business can stay where it is, and what a move might do to future earnings. That may change the price or conditions they’re prepared to offer.
In @bdc_ca's guide to negotiating commercial leases, Business Centre Manager Brett Prikker recommends involving a commercial lawyer. Before a sale process, pull together your signed lease, amendments and renewal documents and work through three questions with that advisor:
• How much time remains, and what renewal options are available?
• When must notice be given to exercise those options?
• What does the lease say about a sale of the business and any landlord consent required?
Rent increases, additional charges and early termination clauses can alter the economics too. Their effect will depend on the lease and proposed transaction.
A longer renewal isn’t automatically the right answer. Weigh the cost and flexibility against the security it provides and what a likely buyer would need.
If you need to discuss this with the landlord, agree on the timing and approach with your advisors so you can manage confidentiality during a potential sale.
Put the notice deadlines in your calendar so you have time to address any concerns.
Further reading: BDC’s guide to negotiating a commercial lease.
bdc.ca/en/articles-tools/mon…

16
You hired a manager to free up your time. Why are you still making the same day-to-day decisions?
Staff come to you for approval. You step in because it’s quicker, or because you would handle the situation differently.
If that keeps happening, the manager carries the responsibility while you’re still running their part of the business.
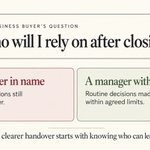
In a smaller business, management depth can start with one capable person who has the authority to lead. Agree on:
• The decisions they own, such as scheduling work or resolving routine customer complaints.
• The limits that apply, including pricing, spending or customer credits.
• The situations where they should involve you.
Your team needs to know where that authority sits. Routine questions should go to the manager, with you involved when something falls outside the agreed limits.
That includes backing reasonable calls you might have handled differently. You can review the judgment together afterwards without routinely taking control.
From a business buyer’s perspective, this makes it clearer who can handle day-to-day operations and how much support they’ll need from the departing owner. The new owner may still take an active role, but they have an experienced manager to work with.
If you already have a capable person on your team, consider which decisions you could give them responsibility for now, along with the information and support to handle them well.
For owners who’ve made that change, what helped you get comfortable giving someone else the final call?

12
A buyer asks for your financial statements, monthly reports, and sales by customer.
Each report looks reasonable on its own, but the totals don't line up.
There may be a straightforward explanation: a year-end adjustment, different reporting periods, or revenue grouped differently in each report.
But someone still has to explain it. Until they do, a buyer will try to decide which numbers to rely on.
That means more questions and more work. If the differences remain unresolved, they can affect a buyer's confidence in the earnings and the terms they're willing to offer.
For an owner thinking about a sale, this is work it’s best to do early.
Take the most recent year-end financial statements and compare them with the reports you use to run the business.
• Can you explain the differences in revenue and profit?
• Can your sales-by-customer report be tied back to the same period?
• Are you using the final version of the accounts?
If something doesn't reconcile, work through it with your accountant and keep a short explanation with the supporting records.
You may find a reporting issue, an outdated file, or something that needs correcting. It's easier to deal with while you have time to understand it.
Good records give a buyer a clear path from the figures presented to the evidence behind them, creating more confidence and reducing potential issues and friction in the due diligence process.
That path is worth building well before a buyer asks for it.

1
33
A great customer can still be a real risk when you sell your business.
They pay on time and send steady work. You've earned their trust over years.
They’re a customer you want to keep. The question is what happens to the business if that work slows down, or the relationship changes after a sale.
Business owners need to start by looking at more than their share of revenue:
• How much gross profit comes from that customer?
• Which costs would remain if the work stopped?
• How long would it take to replace the work?
• What evidence supports the relationship continuing under a new owner?
A customer who fills your schedule may also leave you with staff, equipment or space you still have to pay for if they leave.
That's the exposure a buyer needs to understand.
Long tenure, a well-documented relationship and several points of contact can help. A contract may help too, depending on its terms.
But “they've always been loyal” leaves a buyer with a lot to work out.
If you have a major customer, make sure to pull together the revenue and margin history, key terms, and an honest view of what losing the account would mean.
Then choose one practical step to reduce the exposure. That might be building other accounts, sharing responsibility for the relationship, or getting clearer about future work.
You don't need to give up a good customer to improve the business.

49
A business can still be profitable and sellable, yet be worth considerably less than it was three years ago.
A recent article from @IBBA_canada describes a pattern I see quite often, though many owners only recognize it once it’s too late.
An owner may begin thinking about retirement and gradually slow down, or their capacity may be affected by health issues or other life changes. As attention shifts, key hires get delayed, necessary systems work is deferred, and more customer and employee relationships remain concentrated with the owner than is healthy for the business. As a result, the business can also begin to lose key customers or employees, further weakening stability and long-term value.
The financial statements may still look respectable, but buyers can see that the business has lost momentum.
Consider a simplified example:
Three years ago, the business was generating $1 million in EBITDA, growing steadily and supported by a capable management team. A buyer might have valued it at 5x EBITDA, or $5 million.
Today, EBITDA has slipped to $900,000. Revenue is flat, a key manager has left and the owner has become more central to the business. A buyer may now value it at 4x EBITDA, or $3.6 million.
That relatively modest $100,000 decline in earnings has contributed to a $1.4 million decline in value because lower earnings and a lower multiple compound the impact.
A business can still be profitable and sellable, yet be worth considerably less than it was three years ago. While every business is different and valuation multiples vary widely across industries, the direction of travel here is what matters most.
The numbers are illustrative, and actual multiples can vary considerably by business and sector. The underlying point is what's most important.
Having been an owner myself, I understand that the loss of focus, effort, and investment in a business you expect to sell in the near future is often gradual and sometimes unintentional, driven by competing priorities, fatigue, or the assumption that there won't be an obvious impact.
At the same time, it’s important to recognize that not all value erosion is within the owner’s control. Increasing costs, unexpected shifts in customer demand, new competitors entering the market, regulatory changes, and even unexpected health or personal/family circumstances affecting the owner or key team members can all negatively impact performance and, in turn, valuation.
The challenge is that when these external pressures are combined with even a subtle internal pullback, the effect can be amplified, reducing both the price buyers will pay and the number of credible buyers willing to pursue the business.
This is why planning several years in advance can be so valuable. It creates time to understand what the business may be worth today, identify the risks buyers will focus on, and make changes while they can still affect the outcome.
What early signs, if any, are you noticing in your own business that might suggest this is starting to happen, and what do you think is driving them?
Source: [“The Business Was Worth More Three Years Ago,” IBBA Canada](ibbacanada.org/the-business-…)
#BusinessSale #ExitPlanning #BusinessValuation #BCBusiness

1
25
Some growth improves business value. Some growth creates more questions.
A business buyer usually cares less about growth in the abstract and more about the quality and predictability of that growth.
A few examples:
• Revenue from repeat customers is usually easier to trust than a one-time spike.
• Higher-margin growth is usually more valuable than growth that keeps people busy but does not improve profit.
• Growth that does not rely on the owner personally is easier to transfer.
• A signed contract is stronger than a loose conversation.
• A pipeline with names, timing, probability, and margin is stronger than a general statement that “there is lots of demand.”
This is where owners sometimes get frustrated. They see the opportunity clearly because they know the market, the customers, and the history.
A buyer sees what can be proven.
That doesn't mean the buyer is right about everything. Buyers can be overly cautious and can miss the story.
But if the goal is to support value, the growth story needs evidence.
Where is the revenue coming from? Will margins hold? Who will execute the work? Is there enough team capacity? Can the growth continue without the owner pushing every relationship forward?
A smaller business with stable repeat revenue and clean margins may be more attractive than a larger business with volatile sales and thin profitability.
Growth helps most when it gives the buyer confidence in future earnings.
If you were looking at your own business through a buyer’s lens, what part of your growth story would you feel most confident defending, and what part might need stronger support?
#BusinessGrowth #BusinessValuation #MergersAndAcquisitions #Entrepreneurship #ExitPlanning

24
A few weeks ago, I shared a simple test for business owners:
Could your business continue operating properly if you stepped away for 60 days?
I have now expanded on the idea in a new article I wrote for @NewX54812.
The article looks at why owner dependence matters well before a sale or succession is being considered, and some practical ways to move knowledge, relationships and decision-making more deeply into the business over time.
For many owners, the goal is simply to build a company that is easier to manage and better prepared when something unexpected happens.
You can read the full article here:
deltacity.news/the-60-day-te…
#BusinessOwners #BusinessContinuity #SuccessionPlanning #DeltaBC

6
Business buyers don't automatically reject earnings adjustments (also known as add-backs in the M&A world).
They reject the ones that feel vague, aggressive, or poorly supported.
This matters a lot because in many privately held businesses, reported profit for tax purposes does not tell the full story. There may be legitimate adjustments/add-backs for owner compensation, one-time expenses, non-operating items, or discretionary costs that would not continue under new ownership.
This is completely normal and even expected, but the support for these add-backs matters a lot. A buyer is much more likely to accept an add-back when it is clearly explained and backed up.
For example:
• A one-time legal bill tied to a specific issue.
• A vehicle expense that is partly personal, with a reasonable adjustment.
• A family member on payroll who does not work in the business.
• A one-time repair that is not part of normal operations.
These types of add-backs can be discussed.
What gets harder is a long list of “personal expenses” with no detail, no invoices, no explanation, and no clear logic. At that point, the buyer starts wondering whether the earnings are real.
The practical takeaway for owners is simple:
If you think something should be added back, document it before a buyer asks.
Keep the invoice. Write down the reason. Separate recurring from one-time. Be realistic about what would actually continue after closing.
Strong add-backs can help tell the true earnings story.
Weak add-backs usually create doubt and can undermine trust and even potentially derail a deal.
When in doubt, put yourself in the buyer's shoes. If you were reviewing a set of add-backs as a buyer, what would make you comfortable accepting them, and what would raise a red flag?
#AddBacks #BusinessValuation #DueDiligence #MergersAndAcquisitions #SmallBusiness

22
The best offer for your business isn't always the highest price.
That can be hard for owners to hear, especially when they have spent years building the business, and the headline number feels like the scorecard.
But when selling a business, price is only one part of the outcome.
A $5.0M offer with 60% cash at close, a large vendor note, an earn-out, heavy conditions, and a long transition period may carry more risk than a $4.6M offer with 90% cash at close and a cleaner path to closing.
The higher number may still be the better deal, but it needs to be compared properly.
Some of the questions I would want an owner to ask:
• How much cash is actually paid at closing?
• What has to happen for the deferred amount to be paid?
• Who controls the earn-out conditions?
• How conditional is the offer?
• What transition role is expected from the seller?
• Is the structure workable from a tax, legal, and financing perspective?
Sometimes the best offer is the one with the strongest buyer, the cleanest structure, and the lowest risk of retrading later.
That doesn't mean owners should accept a low price. It means the offer needs to be understood as a whole.
If you're selling your business and receive multiple offers, it’s important to look beyond the headline number and understand what each offer truly represents.
Owners should also always review deal structure with their M&A advisor, accountant, lawyer, and tax advisor before making any decisions.
If you were comparing two offers today, what would matter more to you: the highest headline price, or the certainty of getting paid?
#BusinessSale #MergersAndAcquisitions #DealStructure #Entrepreneurship #ExitPlanning

14
The simple way for business owners to sanity check owner dependence:
If you stepped away from the business for 60 days, what would slow down?
Not a long vacation where you are still checking email every night. A real absence.
Think about the decisions and responsibilities that currently run through you.
• Who handles pricing and customer negotiations?
• Who owns the key customer relationships?
• Who approves unusual decisions or resolves problems when they arise?
• Who manages supplier relationships and keeps staff aligned?
• Who notices when margins start slipping before it becomes a bigger issue?
This test is not meant to make owners feel bad.
In many privately held businesses, the owner is the person who built the relationships, solved the hard problems, and carried the business through difficult periods.
That is admirable.
But from a buyer’s point of view, the question is different: “What am I buying if the owner is no longer there?”
The more value sits in the team, systems, customer base, and repeatable process, the easier the business is to transfer. The more value sits with the owner personally, the more a buyer will worry about transition risk.
For many owners, the first step is not hiring a full management team.
It can be much simpler than that:
• Document one process.
• Move one customer relationship deeper into the company.
• Train one person to handle pricing.
• Write down something only you know.
Small changes can start shifting value from personal goodwill to transferable business value.
#BusinessValuation #ExitPlanning #OwnerDependence #MergersAndAcquisitions

17
Trying to keep everyone happy can make a business harder to transition.
And that’s exactly where many succession plans start to unravel.
@bdc_ca published an insightful article recently on choosing a successor in a family business. While the article focuses on family succession, @deveshd, Lead Advisor, emphasizes a point that extends well beyond family-owned companies.
A business needs clear leadership.
When authority gets spread across multiple people for the sake of fairness, the company can end up with no real decision-maker.
Everyone has a voice. No one has the final call. Employees get mixed direction. Decisions slow down. Strategy gets watered down.
For a third-party buyer, this is management risk.
Buyers are already asking hard questions:
Who actually runs the business? What happens when the owner leaves? Can the team make decisions without the founder? Is there one accountable leader, or a group of people trying to share control?
A fractured leadership structure makes the business harder to diligence and harder to trust.
This does not mean fairness is irrelevant. It means fairness and operating control need to be handled separately.
You can address economic fairness through share structure, estate planning, insurance, real estate, or other assets. That is where legal, tax, and estate planning advisors matter.
But day-to-day leadership has to be based on competence, credibility, and accountability.
A business may have multiple shareholders, but it should still have a clear operator.
That distinction matters long before a sale process starts.
Because buyers do not only buy financial results. They buy confidence that those results can continue after the owner exits.
For owners thinking about succession or a future third-party sale, this is a hard but important question:
Are you building a company with clear operational leadership, or a structure designed mainly to avoid difficult conversations?
Source: Business Development Bank of Canada (BDC), “Choosing a successor: Why making the right choice matters more than fairness” (April 28, 2026): bdc.ca/en/articles-tools/cha…
#SuccessionPlanning #BusinessTransition #FamilyBusiness #BusinessValue

One of the most common things owners say is: “There is so much potential in this business.”
Sometimes they are right.
Growth potential. Margin potential. New markets. Better marketing. More capacity. A buyer who could “take it to the next level.”
The issue is that buyers rarely pay full value for potential that has not been tested.
They will usually ask:
• Why has this not already been done?
• Who would execute it?
• What would it cost?
• Would margins hold?
• Is there proof customers actually want it?
Potential can attract buyers. Proof changes what they are willing to pay.
A signed contract, a qualified pipeline, a tested marketing channel, a product line with early traction, or a manager who can execute without the owner are all examples of proof that reduce uncertainty and make future performance easier to believe.
Those things change the conversation because they move the discussion from theory to evidence.
Trust traction. Prove potential.
A buyer may still share future upside through deal structure, an earnout, vendor financing, or a stronger price if the evidence is convincing enough.
But “there is lots of potential” by itself is usually not a valuation argument.
It's a starting point for a better question:
“What proof can we build before a buyer asks?”
#BusinessAcquisition #BusinessValuation #SellYourBusiness #MergersAndAcquisitions

11
Owners of privately held businesses can start losing value in a business sale after the LOI is signed.
There’s a memorable phrase that I really like for this: The Maui Effect.
The phrase was coined by Mike McIsaac at @bakertillycan, who wrote about it recently. The idea is simple: once an owner starts mentally shifting their attention to life after the sale, like dreaming about being on a beach in Maui, their focus can drift before the transaction is actually complete.
That drift can be expensive.
Buyers are watching the business right through due diligence. If revenue declines, margins slip, customer follow-up slows, or the team senses the owner has checked out, the buyer usually does not treat it as a harmless wobble.
They start asking harder questions.
Was the original story too optimistic? Is the business more dependent on the owner than we thought?
Do we need a holdback, earnout, price reduction, or longer diligence period?
That’s where value starts leaking out.
A private business sale can often take 9 to 18 months, Mike notes in his article. By the time an LOI is signed, many owners feel like the finish line is close. In reality, the hardest part of the process is still ahead: keeping the business performing while also responding to diligence, advisors, buyer questions, employees, landlords, lenders, and lawyers.
The owner’s job is not finished when a buyer is found.
The owner’s job is finished when the deal closes, the transition risk is under control, and the business is set up to succeed without them.
Only then is it time to start thinking about Maui.
For anyone who has gone through an exit: how did you manage the pressure of running the business while also carrying the weight of the transaction process?
Source: “The Maui Effect: Why Business Owners Lose Focus Before the Finish Line” by Mike McIsaac, Baker Tilly (May 25, 2026): bakertilly.ca/insights/the-m…

13
I had an article published yesterday in the Delta City News on what business owners should understand about business value.
It was written for Delta owners, but the concepts apply to small and midsized businesses almost anywhere.
Buyers and lenders look at more than revenue and profit.
They look at clean financial records, customer concentration, lease terms, owner dependence, recurring revenue, team depth, and whether the business can keep performing after a transition.
That is why two businesses with similar earnings can sell for very different prices.
For owners, value is usually built long before the decision to sell.
Article link below:
deltacity.news/what-delta-bu…
#BusinessValue #ExitPlanning

8
Most business owners do not get to choose the perfect time to sell.
Sometimes they do. Sometimes life gets in the way.
Health, family, a buyer approach, partner issue, burnout, or a market window can force the timing.
That is why it helps to think about exit planning in stages, not as a fixed calendar.
For an established business, the ideal planning window is often 12 to 24 months before market launch.
That does not mean being “for sale” for two years. It means understanding value, risks, structure, and buyer fit early enough to improve your options.
These stages are not exact for every deal, but they can help owners spot issues earlier and avoid treating the sale process as something that starts only when urgency hits.
12–24 MONTHS BEFORE MARKET
Understand value, saleability, and structure.
Get a grounded view of what the business may be worth, who the likely buyers are, and what could make them hesitate.
Involve tax, legal, accounting, and wealth advisors where needed. Share sale vs. asset sale, LCGE / QSBC status, excess cash, passive investments, shareholder loans, real estate, and family trusts can affect net proceeds and timing.
Some issues are hard to fix at the last minute.
6–12 MONTHS BEFORE MARKET
Make the business easier to explain and review.
Strengthen reporting where it will build buyer confidence. That may mean review engagements, a sell-side QoE, or better support for earnings adjustments.
Review concentration risks, key contracts, leases, owner dependence, and diligence gaps before buyers do.
3–6 MONTHS BEFORE MARKET
Build the buyer strategy, story, and supporting materials.
Who are the best-fit buyers?
What will they care about?
What should they see before and after confidentiality?
Decide what to share first, what to hold back, and how to organize what buyers will review.
MARKET LAUNCH TO BUYER MEETINGS
Run a controlled, confidential buyer process.
Outreach, buyer screening, Q&A, meetings, and feedback need to be managed carefully.
The aim is not every possible buyer. It is the right buyers, with the business protected.
OFFER TO CLOSE
Manage diligence, structure, and closing.
An accepted offer is not the finish line.
Next comes diligence, structure discussions, working capital, financing, legal agreements, transition planning, and closing mechanics.
Weak preparation often shows up here.
Buyers slow down.
They ask for price changes.
They add conditions.
Or they walk.
POST-CLOSE
Support the handover.
Depending on the deal, transition support, true-ups, training, customer introductions, or integration planning may still need attention.
The timeline can compress, but the stages still matter.
If you have time, use it to improve the business before buyers judge it.
Better preparation can mean better outcomes: more credible buyers, more confidence in the numbers, fewer diligence surprises, and a stronger chance of holding value through closing.
#ExitPlanning #MergersAndAcquisitions #BCBusiness

28
If you own an established lower mid-market manufacturing or industrial business , buyer appetite may be stronger than you think.
The latest @MNP_LLP Canadian middle-market update showed transactions increased 10% quarter over quarter in Q1 2026, from 251 to 276 deals.
Industrials led the quarter with 76 transactions, representing 27.5% of deal activity.
MNP’s manufacturing update adds another useful signal: North American manufacturing transaction volume increased for the seventh consecutive quarter and reached its highest level in more than eight years. Strategic buyers accounted for 85% of Q1 2026 manufacturing volume.
For owners of established manufacturing, fabrication, distribution, equipment services, and other industrial B2B businesses, that is a market signal worth paying attention to.
But I would be careful about reading this as a simple “market is hot” story.
Buyer appetite helps. Buyer selectivity still matters.
In lower mid-market industrial and manufacturing deals, buyers get practical quickly. They want to know whether earnings are supported by the operation, not only the headline profit or EBITDA.
That means questions like:
• How much deferred maintenance is hiding in the equipment base?
• Is growth coming from real capacity, or from running the team and assets harder than is sustainable?
• Are gross margins stable by product line, job type, contract, or customer group?
• How exposed is the business to tariffs, freight costs, foreign exchange, supplier concentration, or material price swings?
• Are there environmental, safety, WorkSafeBC, quality-control, or certification issues that could surface in diligence?
• Is the facility fit for a buyer’s plans: zoning, power, yard space, lease terms, and room to expand?
• Are inventory, WIP, backlog, quoting, and job-costing systems good enough for a buyer to trust the numbers?
The usual buyer concerns still matter: owner dependence, customer concentration, financial reporting quality, earnings adjustments, and management depth.
But industrial and manufacturing buyers often go a level deeper.
They are trying to figure out whether earnings are durable, assets are supported, and the business can continue to perform and grow after a transaction.
That is where preparation creates leverage.
A stronger M&A market can create more conversations and bring strategic buyers back to the table. For the right business, it can also increase the odds of a competitive process.
But market momentum does not fix operational or diligence gaps.
If a sale is possible in the next few years, the useful question is not only:
“Is buyer activity improving?”
It is:
“Would my business hold up when an experienced industrial or manufacturing buyer starts asking detailed questions?”
Source: MNP Corporate Finance, Canada’s Middle Market M&A Update – Q1 2026 - mnp.ca/en/services/corporate…
#MergersAndAcquisitions #Manufacturing #IndustrialBusinesses #BCBusiness

1
9
Not every owner’s real choice is “sell” or “don’t sell.”
Sometimes the better question is:
Do you want a full exit, or do you want to take some chips off the table and keep building?
That distinction matters.
A recent article by Patrick Carpentier, Principal, Growth Equity at @bdc_ca, lays out growth equity as a minority-capital option for owners who want liquidity, succession support, or growth capital while staying in control of the business.
That is not the right fit for every company.
BDC notes that growth equity typically fits businesses with a proven model, experienced management, stable positive cash flow, and meaningful scale. In BDC’s case, the article references companies roughly in the $10M to $500M revenue range with at least $3M of EBITDA.
Most owner-operated businesses will not fit that profile today.
But in my experience, the underlying lesson applies much more broadly:
Businesses with management depth and operating discipline tend to have more options.
They may be able to:
• sell outright
• bring in a minority partner
• recapitalize the business
• transition to management or family over time
• keep owning while reducing personal risk
The point is not that every owner should raise growth equity.
The point is that optionality is usually created before a transaction, not during one.
By the time an owner says, “I’m ready to sell,” buyers and investors are already looking at the same things:
• Is the business dependent on the owner?
• Are the financials clean and decision-ready?
• Is there a real leadership team below the owner?
• Are systems and reporting strong enough to support growth?
• Is there a credible plan for what happens next?
Those questions matter whether the outcome is a full sale, partial liquidity, or no transaction at all.
This is why exit planning should not be treated as a last-minute event.
A business that is more sellable later is often the same business that can attract better capital options today.
For owners who are not ready to fully exit, that can be a useful reframing.
You may not need to decide between selling and doing nothing.
You may need to understand which options your business is actually ready for.
Question for owners and advisors:
If you had the choice, would you rather sell outright or take some chips off the table and keep upside?
Source: BDC, “Growth equity: A partner for what comes next” by Patrick Carpentier
bdc.ca/en/articles-tools/blo…
#BusinessOwners #ExitPlanning #GrowthEquity #CanadianBusiness

5
Here’s the uncomfortable truth of family business succession and exit planning: the advisors who know the family best may not be the right people to lead a third-party sale.
That is not a criticism of accountants or lawyers. Good ones are essential.
But knowing the family history is different from managing a competitive sale process.
Your accountant understands the numbers. Your lawyer understands the legal history.
A third-party buyer is looking at something else.
A family may be thinking about:
• preserving the legacy
• protecting employees
• keeping family relationships intact
• making sure the “right” buyer gets the business
A buyer is usually thinking about:
• normalized earnings
• customer concentration
• management depth
• owner dependence
• working capital
• risk after closing
• whether the deal can actually get financed
That gap matters.
A recent @IBBA_canada article cited studies showing that only about 30–35% of family businesses have a documented succession strategy. That lines up with what I see in conversations with family business owners.
In many family businesses, succession and sale planning carries years of history, expectations, and relationships.
There may be adult children with different levels of interest.
There may be family members working in the business who are not natural successors.
There may be a founder who wants to step back, but still cares deeply about what happens to the people, culture, and reputation they spent decades building.
That emotional layer can lead to good decisions. It can also lead to delayed decisions, unclear expectations, or accepting a weaker deal because the buyer says the right things early.
This is where a dedicated sell-side advisor becomes important.
A good M&A advisor or business broker does not replace the accountant or lawyer.
The better model is usually to build the right deal team, then have someone quarterback the transaction process.
The accountant can help with financial history, tax considerations, and accounting questions.
The lawyer can help with legal structure, agreements, and risk protection.
The sell-side advisor’s role is different: prepare the business for market, position it properly, manage buyer interest, create competitive tension where possible, and keep the process moving toward a real closing.
The sale of a family business is rarely only a financial event.
But the market will still treat it like one.
That’s the tension owners need to prepare for.
Question for family business owners and advisors:
When a family business is preparing for a third-party sale, who should quarterback the process: the long-time accountant or lawyer, or a dedicated sell-side advisor working alongside them?
Source: IBBA Canada, “The Evolving Realities Around Succession in Family Businesses”
ibbacanada.org/the-evolving-…
#FamilyBusiness #SuccessionPlanning #BusinessSale #CanadianBusiness

7
What happens to business values if Canada makes entrepreneurship easier again?
That’s the more optimistic question coming out of Part 2 of the @CFIBNews April 2026 “entrepreneurial drought” report.
Part 1 focused on the problem: Canada has had more businesses exiting than entering since early 2024. Part 2 looks at what could help reverse it.
CFIB points to some very practical priorities: reduce the cost of doing business, improve access to financing, cut unnecessary red tape, address labour shortages, and make business succession easier.
For owners thinking about selling in the next few years, implementing some or all of these measures could have a big impact.
A better small business environment does not automatically make every business more valuable, but it can change the buyer’s view of the risk:
• If costs ease, margins become easier to defend.
• If financing improves, more buyers can actually complete transactions.
• If red tape is reduced, growth plans become more credible.
• If labour availability improves, buyers have more confidence that the business can keep operating and growing after a transition.
• If succession pathways improve, fewer good businesses have to close simply because the owner ran out of time or options.
That is where the optimism comes in: good businesses become easier to believe in when the environment around them becomes more supportive.
The caution is that policy reform (if and when it happens) still will not do the seller’s job for them. Buyers still pay for proof. They want clean financials, durable earnings, transferable operations, manageable owner dependence, and a believable plan for what happens after closing.
So yes, I hope Canada becomes a better place to buy, own, and grow a business, and the sooner it happens, the better.
But for owners thinking about a transition, the practical takeaway is still the same. Make it easy for a buyer to understand why your business is worth owning.
A better environment may improve the market. A better-prepared business will be in the strongest position to benefit from it.
Which change do you think would do the most to improve buyer confidence: lower costs, better financing, less red tape, labour access, or stronger succession pathways?
Source: CFIB, “Canada’s Entrepreneurial Drought, Part 2: Fixing Canada’s Shrinking Business Landscape” - cfib-fcei.ca/en/research-eco…
#BusinessSuccession #EntrepreneurshipCanada #SmallBusinessPolicy

1
13