




ResearchPulse retweeted

Need a primer on amylin? 🤔
📣 Happy to share our new American Association of Clinical Endocrinology (AACE) Module:
Preparing for Change: Amylin Science and Emerging Hormone-Based Obesity Therapies 🔬
In this module series we discuss:
🔹Physiologic role of amylin in energy balance, appetite regulation, and metabolic control, and how it complements other hormonal pathways involved in obesity.
🔹 Emerging clinical evidence on amylin-based therapies and their potential role in the future management of obesity.
🔹 Evolving amylin science into a broader, mechanism-based framework for individualized obesity treatment
🔗 Module Link: pro.aace.com/education-and-e…

ResearchPulse retweeted

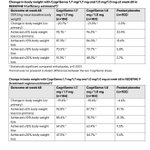
Treatment with once per week #CagriSema at doses of 1·7 mg each and 1·0 mg each led to clinically significant bodyweight reduction, with a safety & tolerability profile similar to that observed in previous trials with #CagriSema thelancet.com/journals/landi…
#obesity #weightloss

ResearchPulse retweeted

December 20, 2024. A date that changed the story for $NVO. Make coffee and read this!
That was the day Novo Nordisk released the first results from REDEFINE 1. CagriSema delivered 22.7% weight loss after 68 weeks (efficacy estimand) — below the market’s expectations, after Novo had previously communicated a potential 25%.
The market’s reaction was brutal. Novo lost 688B DKK (101B USD) in marketcap that day.
The share price fell from DKK 692 to an intraday low of DKK 484, before closing at DKK 546 — a decline of almost 21% on the day. Trading volume reached approximately 26 million shares on the Copenhagen exchange.
And the decline did not stop there.
But fast-forward to #ObesityWeek 2026, and the picture is becoming more nuanced.
Novo has now presented additional data from REDEFINE 1 showing that 67.8% of CagriSema patients were early responders, achieving at least 5% weight loss within just eight weeks. These early responders had an observed mean weight loss of 25.4% at week 68. That's more then 25%!
Another important finding: 73.1% reported a meaningful improvement in physical function, compared with 49.1% on placebo. Meaningful improvements in psychosocial function were also reported by 69.0%, versus 42.1% on placebo.
And then there is REDEFINE 9.
CagriSema delivered approximately 21% weight loss at 68 weeks even at the lower 1.0/1.0 mg and 1.7/1.7 mg doses. Importantly, the treatment-regimen results — which account for treatment discontinuation — were still 18.6% and 19.4%, respectively.
These are not just numbers on a scale.
The market is increasingly recognising that obesity treatment is about much more than the percentage of weight lost. The broader clinical value matters too.
#Semaglutide, one of CagriSema’s two components, already has substantial evidence beyond weight reduction:
• Cardiovascular: The SELECT trial demonstrated a 20% reduction in major adverse cardiovascular events in people with overweight or obesity and established cardiovascular disease.
• Kidney protection: The FLOW trial demonstrated a 24% reduction in the risk of major kidney outcomes in people with type 2 diabetes and chronic kidney disease.
• Liver disease: The ESSENCE trial showed significant improvements in MASH resolution and liver fibrosis with semaglutide 2.4 mg.
These are semaglutide data — not yet outcomes demonstrated specifically for CagriSema. But they illustrate the broader therapeutic value of the molecule that is already part of the combination in CagriSema.
Following the ObesityWeek developments, $NVO is trading at DKK 287.50, up 3.24% today.
The stock has been through an extraordinary repricing. The question is whether the market has become so focused on the initial disappointment that it is underestimating the longer-term potential of CagriSema.
Perhaps the market is slowly beginning to look at the whole picture again. They new journey just started!
$NVO $LLY

ResearchPulse retweeted
🇨🇳 Novo Nordisk has secured national reimbursement for IcoSema (insulin icodec + semaglutide), making China the first country to provide reimbursement for this innovative once-weekly combination.
At the same time, Awiqli (insulin icodec) has secured renewed reimbursement with an expanded coverage scope for patients with type 2 diabetes.
A few key points:
🔹 IcoSema enters China's national reimbursement list from January 1, 2027.
🔹 Novo is already lowering regional list prices to bring the benefits to patients ahead of implementation.
🔹 Awiqli's reimbursement coverage is expanded to type 2 diabetes patients.
More access, stronger commercial positioning — although pricing and margins will be important to watch.
Source:
baby.ifeng.com/c/8y2uw4xykK0
$NVO #NovoNordisk #Diabetes


ResearchPulse retweeted
GLP-1 tracker updated! TRx for week ending October 30, 2026. Foundayo at week 31 of launch.
Wegovy pill at week 44 of launch.
- Wegovy pill = 185,366 TRx
- Foundayo = 69,323 TRx
Wegovy pill to Foundayo = 2,67x TRx
Same launch periods, Wegovy pill to Foundayo:
1. 2.21x
2. 4.97x
3. 4.65x
4. 3.89x
5. 3.73x
6. 3.41x
7. 4.17x
8. 4.33x
9. 4.08x
10. 4.12x
11. 4.61x
12. 5.12x
13. 5.39x
14. 4.67x
15. 4.65x
16. 4.59x
17. 4.18x
18. 3.52x
19. 3.88x
20. 3.57x
21. 3.03x
22. 3.36x
23. 3.44x
24. 2.85x
25. 2.33x
26. 2.64x
27. 2.45x
28. 2.93x
29. 2.72x
30. 2.66x
31. 2.35x
$NVO
$LLY

ResearchPulse retweeted

30,000+ participants. Three landmark cardiometabolic trials. One commitment to advancing CV care. Explore Novo’s leading research in CV disease: novonordiskmedical.com/thera…

ResearchPulse retweeted

“Novo's Next Weight Loss Pill Isn't a GLP-1, And That's HUGE”
Interesting podcast.
LX9851 is the new agent’s current name and it’s an ACSL5 inhibitor.
It’s a small molecule, not a peptide.
I’d never heard of ACSL5 before, but it stands for “Acyl‑CoA Synthetase long‑chain family member 5”.
That’s a mouthful!
It seems that the enzyme helps the gut digest dietary fatty acids. Inhibition leads more fatty acids in the small intestines, slowing gastrointestinal motility… so possibly leading to more fullness signals.
It may also increase GLP-1 and PYY, further promoting fullness.
These are exciting times for obesity medicine!
podcasts.apple.com/us/podcas…

ResearchPulse retweeted
BIG BEAT $NVO
Q3 2026 is the best quarter in two years. And the most important thing is that 80% of US Wegovy pill patients are new to GLP-1 obesity drugs. So the oral launch is expanding the market, not eating the injectable.
The beat:
- Sales DKK 79.2bn vs 73.2bn (+8%), +4% CER
- Adj. EBIT DKK 31.7bn vs 28.4bn (+12%), despite ~DKK 3.5bn of one-offs sitting inside the adjusted line
- Adj. EPS DKK 5.79 vs 5.10 (+13%)
- Wegovy pill DKK 5.39bn vs 4.62bn, +53% QoQ
Third guidance raise this year. Adj. sales and EBIT now -2% to +2% CER. In February it was -5% to -13%, so that is +9pp at the midpoint in nine months (but we knew they would be conservative). FCF guide now DKK 60–70bn (Feb: 35-45bn).
Important for the company:
1) Oral is market expansion, not cannibalisation. 80% of US Wegovy pill patients are GLP-1-naïve. Pill volume +20% QoQ AND injectable volume +10% QoQ. Combined US Wegovy sales +21% CER.
2) Novo is winning the oral fight. Around 80% of US oral obesity NBRx vs Foundayo. Around 90% in the UK, 80% in the UAE. The clean label (no DDI restrictions, no contraception caveat, MACE in label) is also an important factor here.
3) International is the engine. IO delivered app. 93% of Q3 growth, EUCAN obesity +47%. Germany: around 100k pill packs in six weeks. >20 pill markets by H1'27.
4) Ozempic pill relaunch: NBRx doubled vs Rybelsus, >60% GLP-1-naïve, 25 mg FDA decision this quarter. (US TRx is now around 67,000).
5) 2027 is a launch year: CagriSema (FDA decision Q4), Frehemgo (EU at turn of year, US H1'27), etavopivat filing Q4.
Also important to have in mind:
- Volume is not value. US injectable Wegovy -13% CER and pill revenue per script is roughly 40% of the injectable’s.
- Reported EPS -16% on DKK 8.7bn of impairments (ziltivekimab + manufacturing).
- Adj. EBIT +27% flatters: Q3'25 carried ~DKK 9bn of restructuring costs.
- 1 Jan list-price cuts (app. 50% Wegovy and 35% Ozempic) hit 2027 cash flow.
- The guidance midpoint still implies a soft Q4. Sandbag or headwind? I think they are going for another raise so sandbagging for now.
- Foundayo’s share of US oral NBRx is going toward 20%.
The GLP-1 engine has stabilised, and Novo is executing very well on oral. This pushes sentiment another small step in the right direction.

ResearchPulse retweeted
💰 $NVO: The Free Cash Flow story is becoming increasingly difficult to ignore.
One of the most interesting developments in Novo Nordisk's Q3 results may not be revenue growth or market share. It may be cash generation.
I've previously written about this in my September article, "Novo Nordisk: The Cash Flow Story the Market May Be Overlooking." nitter.gq/Aktieland/status/21024…
Now we have another important data point.
Novo has raised its 2026 free cash flow outlook significantly:
📈 Free cash flow:
DKK 60–70 billion, up from the previous guidance of DKK 45–55 billion.
🏭 CAPEX:
Now expected to be approximately DKK 50 billion, down from the previous estimate of DKK 55 billion.
This is an important combination.
Novo has spent enormous amounts expanding manufacturing capacity over recent years. CAPEX increased dramatically as the company invested ahead of demand.
But the investment cycle is changing.
The company is increasingly moving from:
Massive capacity investments → bringing existing capacity online → lower capital intensity → stronger free cash flow.
And this matters enormously for shareholders.
Consider what sustained cash generation could mean:
• Continued investment in R&D and the next generation of obesity treatments.
• Strategic acquisitions and licensing opportunities.
• Growing dividends.
• Share buybacks, particularly attractive at depressed valuations.
Novo generated approximately DKK 61 billion in free cash flow in 2025. The new 2026 guidance suggests that this level of cash generation can be maintained or improved despite the current growth challenges.
The market is understandably focused on the competitive pressure from Eli Lilly and the need to restore revenue growth.
But perhaps investors are overlooking another part of the equation:
Novo does not need extraordinary revenue growth to remain an extraordinary cash-generating business.
Of course, cash flow is not guaranteed, and the company still faces significant competitive, pricing and pipeline risks.
But if Novo can combine substantial existing cash generation with lower capital intensity and a successful next generation of products, the shareholder-return potential could be considerably more interesting than the current market narrative suggests.
The market is pricing the uncertainty of tomorrow.
I'm paying close attention to the cash Novo can generate today.
$NVO
Source: Novo Nordisk Q3 2026 Investor Presentation, November 4, 2026. See also my September 22 article: "The Cash Flow Story the Market May Be Overlooking."
#NovoNordisk #NVO #FreeCashFlow #CashFlow #Investing #Pharma


The Free Cash Flow Story Behind $NVO
One challenge for Novo Nordisk has been free cash flow. Massive investments in production capacity have absorbed billions in recent years as Novo raced to meet demand.
But that investment cycle is now changing.

ResearchPulse retweeted

Korea's own GLP-1 shot is finally in clinics (first scripts Oct 29), and now we know what it actually costs.
EPPE (efpeglenatide, by Hanmi) is a once-a-week peptide shot that works like Ozempic: it hits the GLP-1 receptor so you feel full and eat less.
Price per weekly shot (supply price, Korean reports Nov 1):
> 2 mg: ~$18
> 4 mg: ~$30
> 6 mg: ~$43
> 8 mg: ~$52
> 10 mg: ~$56
What people actually pay:
> first 4 weeks: ~$130 incl. doctor fees (varies by clinic)
> that's ~60% of Mounjaro's starting cost and ~75% of Wegovy's
> not covered by Korea's national insurance
> only some hospitals have it so far, no pharmacies yet
Who qualifies: adults without diabetes with a BMI of 30+, or 27+ plus something like high blood pressure, high cholesterol or sleep apnea.
Its trial weight loss came in lower than Mounjaro's, but at that price a lot of people won't care.

ALT Bytes Europe / BigGo Finance, Nov 1, 2026: South Korea's Hanmi launches obesity drug EPPE (efpeglenatide) at about $130 for the first 4 weeks, up to 40% cheaper than Mounjaro. Supply price per dose: 2 mg about $18, 4 mg $30, 6 mg $43, 8 mg $52, 10 mg $56.
ResearchPulse retweeted

A new USC preprint projects Medicare's $50 GLP-1 program could save $21 to $27 billion over 10 years.
Here's the catch: those savings rest on a $31.9 billion price cut the program doesn't include. Without it, Medicare spends more than it saves.
Here's why I'd cover these drugs anyway. 🧵

ResearchPulse retweeted
🧬 $NVO is expanding its MASH story.
At #AASLD 2026, Novo Nordisk will present 12 new abstracts spanning real-world evidence, Phase 3 semaglutide data and investigational therapies.
Three highlights stand out:
🔬 Semaglutide vs. resmetirom: a real-world comparison of liver enzymes and cardiometabolic markers in patients with MASH. Selected as a Poster of Distinction.
📊 Beyond obesity: new ESSENCE analyses examine semaglutide 2.4 mg in MASH patients with BMI below 27 — an interesting question for treatment beyond weight loss alone.
🧪 Pipeline potential: new efruxifermin data from the SYMMETRY programme explore fibrosis improvement in compensated MASH cirrhosis, including an AI-based histology analysis.
Important caveat: the real-world comparisons are observational, so they can show associations but cannot establish causality. The ESSENCE subgroup findings are post hoc, while efruxifermin remains investigational.
Novo is building evidence for semaglutide beyond obesity and diabetes, while exploring additional approaches to serious liver disease.
MASH could become another important part of the long-term metabolic disease opportunity.
📍 AASLD The Liver Meeting | Nov 5–9, 2026
Source: ml-eu.globenewswire.com/Reso…, October 28, 2026
#NovoNordisk #NVO #MASH #LiverDisease #Biotech #Investing $LLY
ResearchPulse retweeted

I think the key GLP-1 longevity question is whether it is more than weight loss. In UC Berkeley mice started at 20 months, semaglutide extended average lifespan to 834 vs 742 days and beat calorie restriction on maze and glucose. Via @CNN cnn.com/2026/10/13/health/gl…

ResearchPulse retweeted
The Wegovy pill may be doing something more important than taking market share from injectable GLP-1s: expanding the obesity treatment market.
A new study published in Annals of Internal Medicine examined the early uptake of oral semaglutide following its January 2026 launch.
The numbers are pretty remarkable:
🔹100,000 new monthly prescriptions by month 2**, compared with month 4 for Zepbound and month 20 for injectable Wegovy.
🔹4.4x faster early adoption** than Zepbound and 7.4x faster than injectable Wegovy, based on launch-aligned prescription growth.
🔹Injectable Wegovy prescriptions did NOT decline following the pill's introduction.
🔹Total Wegovy prescriptions (oral + injectable) increased substantially, although Zepbound continued to lead in overall prescription volume.
Here's what I find most interesting:
The introduction of an oral GLP-1 appears to be expanding the market rather than simply cannibalizing injectable therapies. This makes intuitive sense. Some patients don't want injections. Others may find a pill more approachable, even with the inconvenience of daily fasting administration. Of course, these are aggregate prescription data, so we can't definitively establish how many new patients entered treatment versus switched therapies.
But the broader implication is exciting.
We may have substantially underestimated the number of people willing to pursue pharmacotherapy for obesity once we offer them more choices.
And with additional oral obesity medications in development, this market could look very different in a few years.
Source: acpjournals.org/doi/10.7326/…


ResearchPulse retweeted
$NVO CEO Mike Doustdar was asked by Jim Cramer why Novo’s stock continues to struggle despite positive developments.
“The stock market is always right, but with a bit of a time difference,” Mike Doustdar replied.
He explained that Novo’s decision to significantly lower prices for Ozempic and Wegovy is having an immediate impact on revenue, while the benefits of higher prescription volumes take longer to materialize.
“You know this from math: if you halve the price, you have to double the volume to make it even, but you can halve the price on day one. You cannot double the volume on day one.”
Mike Doustdar also acknowledged that the previous pricing was unsustainable.
“It is not conceivable that people can pick up a box of Ozempic or Wegovy for $1,000, frankly speaking.”
With injectable treatments still accounting for the majority of Novo’s sales, the price reductions are weighing on overall growth despite the strong launch of Oral Wegovy.
Mike Doustdar believes Novo now needs to deliver consistent results over several quarters to rebuild investor confidence.
“What I think we need to do is again, continue the results, like we have shown in the last two quarters over a period of time. And then this moment turns into a trend. And hopefully the stock market will also follow.”
The article notes that pricing is not Novo’s only challenge, with competition from $LLY and pipeline setbacks also contributing to investor concerns.
Link: barchart.com/story/news/5091…

ResearchPulse retweeted
During a visit to @EliLillyandCo in Indianapolis this week, we saw LillyPod, the most advanced supercomputer in drug development.