
Ex Global Consumer Fund Manager: 16 years at Citi, Alliance Capital in NYC, London, Singapore. Founder, Neev Capital. Strictly personal musings & not advice...
Joined March 2009
- Tweets25.4K
- Following208
- Followers13.6K
- Likes49.7K
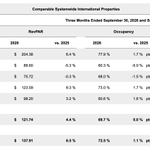


US travel strength remarkable, but strength is evident everywhere bar China & understandably, Middle East, with both occupancy and rates up. Consumers everywhere hot on travel. As rates soar, franchise fees but especially incentive fees are spiking. $MAR $HLT $ABNB $BKNG


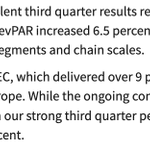
Marriott US revpar +7.4%, 250bp faster than Q2 as travel remains robust. As at $HLT, high end led charge, revpar striking +12% but even economy chains +6%. $MAR global revpar +6.5% vs guide 3.5-4% & sees strong Q4, lifting guide. 💪 $HLT $ABNB $BKNG $AXP $XY $XLF $DAL $UAL


If there's anything to give folks pause, it's that Estee beat Q by 21¢, yet lifted guide by 10¢. Cynics will say that's because stuffing China duty free drove upside. But strength across category & geography suggests this is past low balling $EL was once famous for. $LRLCY


Two things stand out on Estee margin - how geared portfolio is to skin & how sensitive that division is to sales growth. Second, after long being inferior to peers, fragrance gaining traction: 20% sales growth but also a very meaningful profit center. $EL $LRLCY $ULTA $LVMUY


On heels of L'Oreal, excellent Estee Q = premium beauty back in sweetspot. Growth across categories, led by high end. High-margin skincare growing both at top & lower end plus $EL finally(!) catches some of fragrance fairy dust 🔥🔥🔥 $LRLCY $ULTA $PG $UL $LVMUY $HESAY


$AMZN free cash flow awful at -$35 billion due to lumpy capex, despite operating cash flow +20%. Will spend more next year but Q4 '26 capex will fall to $45 billion & should generate free cash. Also note transformation of balance sheet as payables dramatically outpace inventory.


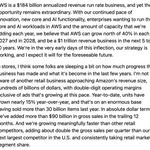
While Jassy is sticking to his capex plans, he gives unusually long defence of what $AMZN is doing as feeling some heat. He's spot on about retail. Still growing 11% in very cash generative US retail even with $110 billion in sales every quarter, with new, high margin streams.

Adjust for 500bp Prime Day shift = $AMZN Retail Q3 strong: US still double digit +11% & International +13%. Subscriptions steady +12% & 3P best in 2 years 13%+. Ads +12% with higher shift impact. Margin at new Q3 high. Fret about AI capex but core isn't problem here unlike $GOOGL
This Services revenue number is disappointing. But saying it raises questions about future of Search is extreme. +12% is in line with the strong uptrend $GOOGL began to post from 2024. It's a step-down from the mid-teens growth it stepped up to exactly a year ago & now has to lap
$GOOGL paid clicks decelerated to +8% from +13% in H1, with cost per click steady at +4%. While 500bp is substantial, barring the last two quarters, it is still the best growth number on paid clicks since Q2 2023.

This Services revenue number is disappointing. But saying it raises questions about future of Search is extreme. +12% is in line with the strong uptrend $GOOGL began to post from 2024. It's a step-down from the mid-teens growth it stepped up to exactly a year ago & now has to lap
Mastercard in line with Visa; US accelerated 100bp to +7% with international steady +11%. Cross-border ex travel also picked up but web very robust +15%, despite Prime Day shift into Q2. $MA $V $AXP $AMZN $WMT $XLY $XLF

This Services revenue number is disappointing. But saying it raises questions about future of Search is extreme. +12% is in line with the strong uptrend $GOOGL began to post from 2024. It's a step-down from the mid-teens growth it stepped up to exactly a year ago & now has to lap
Solid $GOOGL topline in Search with advertising +11%. Some loss of momentum from H1 at both Youtube & Search, but still decent on 2-year stack. But despite TAC still growing slower than revenue, Services margin down hefty 180bp y/y, lowest in 7 quarters to 40.7%, underwhelming.
$GOOGL total revenues accelerated 200bp y/y on Cloud. That was focused in US, which accelerated 700bp from Q2 to +39%. All other regions slowed 200-400bp, reflecting that slowing in Search & Youtube, although still up double digit.


Solid $GOOGL topline in Search with advertising +11%. Some loss of momentum from H1 at both Youtube & Search, but still decent on 2-year stack. But despite TAC still growing slower than revenue, Services margin down hefty 180bp y/y, lowest in 7 quarters to 40.7%, underwhelming.
$GOOGL free cash flow was negative $8.9 billion, $3 billion worse than in Q2, though magnified by working capital movements. Still, it retains best cash generation profiles among hyperscalers, coming closest to funding itself.

Culprits for margin downside? $GOOGL is stepping up pace of hiring - headcount hit 204,757 up 3% QoQ & +8% YoY, fastest since Q4 2023, before it slammed brakes. Plus pressure on margin from surging capex & 50% higher depreciation.


Culprits for margin downside? $GOOGL is stepping up pace of hiring - headcount hit 204,757 up 3% QoQ & +8% YoY, fastest since Q4 2023, before it slammed brakes. Plus pressure on margin from surging capex & 50% higher depreciation.
Solid $GOOGL topline in Search with advertising +11%. Some loss of momentum from H1 at both Youtube & Search, but still decent on 2-year stack. But despite TAC still growing slower than revenue, Services margin down hefty 180bp y/y, lowest in 7 quarters to 40.7%, underwhelming.
Cloud revenue accelerated further more than doubling +103% & margin hit a new high, both a touch ahead of expectations.
Solid $GOOGL topline in Search with advertising +11%. Some loss of momentum from H1 at both Youtube & Search, but still decent on 2-year stack. But despite TAC still growing slower than revenue, Services margin down hefty 180bp y/y, lowest in 7 quarters to 40.7%, underwhelming.
Solid $GOOGL topline in Search with advertising +11%. Some loss of momentum from H1 at both Youtube & Search, but still decent on 2-year stack. But despite TAC still growing slower than revenue, Services margin down hefty 180bp y/y, lowest in 7 quarters to 40.7%, underwhelming.
What is lost amid Visa & Mastercard consistent & healthy reports is that US card spend has accelerated from +5-6% to +8-10% in recent years. $V cites strong economy as it manifests in strong jobs market & real wage gains. 💪 $MA $AMZN $WMT $WSM $XLY $XLF $XRT $DAL $CCL $MAR $ABNB


Visa cross-border accelerated 300bp QoQ on travel, latest sign consumers remain keen on experiences even as prices soar. But $V also points to web driving cross-border past historical trends as $AMZN & peers expand into staples. $DAL $UAL $HLT $ABNB $CCL $BKNG
