

- Momentum/Value stock picking strategy - Buy "out of favour", sell "animal-spirits" - Ex Management Consultant - $APPS expert
Aldebaran, Taurus
Joined March 2023
- Tweets2.6K
- Following172
- Followers216
- Likes649
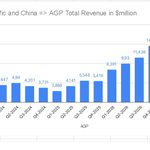




$APPS DT AGP has been growing at a rate of 26% quarter-over-quarter in APAC for the past 8 quarters. At this pace, that would amount to $200 million in 10 quarters. And you might think I’m crazy, but I consider that practically a done deal.

$APPS guess who's doing the monetization for them. Let U and APP focus on gaming. Microdramas growing at 67% this year, imo proxy for AGP.
global.chinadaily.com.cn/a/2…

$APPS just as reminder that EU DMA not only includes mobile apps, but also "virtual assistants" - so google can't just block out every competing ai agent from the phone. That's the loophole for DT in a post-apps world.

$APPS I remember June 2025, when CFO Steve Lasher started and pushed the earnings release back by two weeks to June 16th - in the grand scheme of things, did that lead to poor results or change anything about the company?

$APPS expanding into lock screens, e-commerce & more. DT’s edge in AGP: exclusive phone inventory you can’t bid on in the open market - fully protected from AppLovin & Meta. Lock screens = pure brand power. Coca-Cola when you’re thirsty or at the checkout . Underrated.

$APPS to quote the great philospher Bill Stone:
"...and momentum gets momentum"
I counted 10 times "momentum" in the last conference transcript


$APPS is now riding two massive secular tailwinds: the migration of brand dollars from the open web to apps, and the emergence of AI agent distribution.


$APPS ROTH MKM:
- July 21: $11.50
- Aug 6: $17.50
- Oct 15: $19.00
Just saying, in less than 3 months. What's gonna happen for the next 3 months, if they have to adjust 15% growth higher?
DT executes against a 20% annually growing pie (TAM) of brand ad until 2030
$APPS right now it's getting sold-off because of its debt. But we all know, the delta between EBITDA and Debt is closing faster and faster. (operating leverage above $150M/Q revenue, almost every $1 at the margin translates to $0.80 into EBITDA)
3:1 EBITDA Growth/Revenue Growth
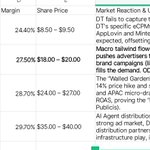
$APPS I told you that Rohit Kulkarni from ROTH knows what's up with Turbine. ($19.00) They are lifting the LONG-TERM revenue growth rate to 15%, it means terminal cash-flows and terminal value gets repriced fast.
(1/2)
uk.investing.com/news/stock-…

$APPS Imagine analysts expect 25% long-term growth next year, that's $50-60 according to me. Because growth rates above threshold revenue of $150M/Q translates 3:1 in terms of profitability.
(2/2)

DD regarding $APPS AI agents: (1/2)
Not DT building the AI agent.
DT’s Ignite is the distribution rail that gets the agent onto the device — pre-installed at the OS level, with SingleTap fulfillment.Partner builds the intelligence.
DD regarding $APPS AI agents: (2/2)
DT supplies the rails (pre-install + fulfillment). Expanding beyond app installs into AI agents, e-commerce experiences, and lock-screen content. Revenue model: CPI-style fee per agent install or rev-share on agent-driven transactions