

west palm beach, fl - planning, managing & advising wealth for athletes and entrepreneurs @momentwealth
West Palm Beach, FL
Joined May 2012
- Tweets4.5K
- Following1.5K
- Followers2.1K
- Likes2.8K






Pinned Tweet
$1,200,000. College Athlete. 1099 Income.
Here’s what nobody tells NIL athletes pulling real money:
The moment your first revenue share or NIL check cleared, you became a small business owner.
The IRS doesn’t care that you’re a student-athlete in college.
They don’t care that your earning window might be just a few years.
They want their cut. Today.
Here’s what we did to keep serious money in his pocket instead of sending a check to Uncle Sam:
1️⃣ LLC taxed as an S-Corp
Put him on his own payroll and paid him a reasonable salary. The rest? Taken available as distributions.
Stops 15.3% self-employment tax from gutting every endorsement check.
→ Saves tens of thousands of dollars.
2️⃣ Maximize business deductions
Training. Recovery. Content production. Travel. Equipment. Agent and legal fees. Home office.
The real cost of running a 7-figure brand, finally run through the entity.
→ Saves tens of thousands of dollars.
3️⃣ Solo 401(k)
$24,500 employee + $47,500 employer = $72,000 deferred for retirement.
At age 20 with 45 years of compounding ahead, that single contribution can grow to millions of tax free money.
And we plan to do this every year that we’re earning 1099 income.
→ Saves roughly $26,000 per year.
4️⃣ Pass-Through Entity Elective Tax
State tax paid at the entity level. Sidesteps the federal SALT cap.
→ Saves about $30,000
5️⃣ Backdoor Roth IRA
$7,500 in. Tax-free growth for life.
At 20 years old, this is the highest-leverage account he’ll ever own.
6️⃣ Donor Advised Fund / his own Private Non-Profit
Builds a giving legacy. Aligns with his personal brand. Generates real federal deductions.
→ Saves $15,000–$40,000+, depending on giving level
Total tax savings for 2026: $150,000+
This is what we do.
Same story every time with NIL athletes earning 6 and 7 figures:
→ Treating the income like an allowance
→ Spending before structuring
→ Trusting the same tax preparer their family used for W-2 income their whole life
You’re not a college kid with a side hustle.
You’re the CEO of a 7-figure personal brand.
Your team should look like one.
📍 If you want to see where you stand with your money, take our Moment Money Quiz and find out in two minutes 👇
Everyone wants passive income.
Then they buy a rental and become a landlord.
Or start a side business and take on a second job.
The most passive income I know of is owning public stocks.
You buy. You hold. You live your life.
No tenants. No inventory. No 2 a.m. phone calls.
Is your passive income actually passive?
1
208
Scott Morrison, CFP® retweeted

This is LinkedIn and X's most viral content format right now.
How to make graphics like this with Claude (playbook + system):
For one client, we've generated 689,130 impressions since Oct 9th with them.
Everyone thinks it's just a matter of copying a graphic format.
But what makes these viral is the underlying topic + compelling packaging.
The most viral ones:
- Scrape publicly-available but hard-to-congregate data on recognizable brands, names, or hot topics (usually with Grok Bot or Apify via Claude)
- Visualize the data while leveraging the recognizable brand names.
Here is the flow:
(1) Find a media format that catches your eye in the feed. We keep a media format swipe file at my agency.
(2) Paste it into Claude with this prompt:
Look at the image I’ve pasted. Explain what makes its layout and data visualization compelling.
My audience is [AUDIENCE], and I sell [OFFER].
Suggest 5 original graphic ideas that use a similar visual approach to explore something my audience would find interesting.
For each idea, tell me:
What we’d compare or reveal.
What data we’d need and where we could find it.
How we could search or scrape it without spending much.
How we’d visualize it.
Use publicly verifiable data. Don’t invent numbers or assume a source has data you haven’t checked.
Recommend the strongest idea that would be easiest to execute.
(3) Pick your favorite idea(s) and let Claude scrape the corresponding data.
(4) Optional cleanup of common AI tells.
Now go run this until the alpha is gone (maybe a couple of weeks).
nitter.gq/MitcheIl/status/212236…


Every athlete runs on two clocks.
Your earning clock lasts about a decade, if you're lucky.
Your spending clock lasts about 60 years.
The American Dream costs $5,043,323: the house, the cars, the kids, healthcare, retirement. It bills you on the second clock.
Here's what you don't control in your career: injuries, the depth chart, the trade, the cap, the new coach who wants his own guys.
Here's what you do control: how fast you build your lifestyle.
Nobody tells you this as a rookie, but spending only moves easily in one direction.
Moving up is a phone call. The car is a text to the dealership. The bigger house closes in 30 days. Nobody in your life pushes back.
Moving down is a different conversation. It sounds like this:
"We need to sell the house."
"The cars have to go."
"Your cousin needs to come off payroll."
You hear it at 31, the season after the last snap, with your whole family watching to see what happens next.
That's the conversation we work hardest to make sure you never have.
So we build the lifestyle slowly, on purpose:
1.Spend what's guaranteed, not what's reported.
2.Let each contract earn the next upgrade.
3.Keep the “entourage” small.
4.Fund retirement first.
Nobody regrets buying the house in year five instead of year one.
But I promise you that there is plenty regret having to sell it in year eight.
One of the things I pride myself on is not simply being a “yes man”. I am going to have the difficult conversations and tell you whether these are smart purchases and reckless ones.

4
379
Money compounds.
So do fees.
So do taxes.
So does the account you keep meaning to check.
Your wealth is built by thousands of small decisions, not one big one.
Are yours compounding the right way?
180
"I didn't even realize all of that went into my son's situation."
I hear that from parents all the time, usually right after I walk them through what the first 90 days look like.
Most families assume the first big decision after the signing bonus is what to buy or what to invest in.
Here's the first 90 days:
1. Residency, before the first half of the bonus hits.
Lease an apartment. Register the car. Register to vote.
2. Banking.
Checking, debit, credit. Opening and educating what the different uses are.
3. Taxable brokerage accounts.
One for long-term investing. One for savings.
4. Retirement accounts.
Roth IRA contributions. A Solo 401(k) for the 1099 income most families don't realize he has.
5. Tax coordination.
His return won't look like anyone else's his age. The tax team needs to know before the money moves, not in April.
6. Insurance.
His coverage should grow with his assets. A 21-year-old with seven figures shouldn't have the same coverage he had at 18.
7. Estate documents.
Revocable trust. Medical directive. Financial power of attorney. Once he turned 18, you lost the legal right to make those calls for him.
This is what the first 90 days look like. Not one conversation about investments.
Yet.
That's by design. My job is to build the infrastructure around the player so his only job is being the best player he can be. And he learns how every piece off the field works while we build it.
I work with the top 1% of the game:
→ Projected first-round picks
→ Established pros
→ All-Stars
→ Players stepping into career #2
That focus is the advantage. Multi-state taxes, a seven-figure bonus at 21, a career that can end on one play.
If you, your son, or someone you know fits this profile, ♻️ this and reach out.
Let's have a conversation to answer one question:
"Are you good?"

267
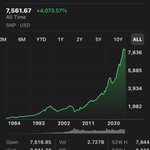
I’d bet most retired millionaires never knowingly bought the dip.
They just invested every paycheck they could.
Every crash on this chart, they bought right through it.

1
4
357
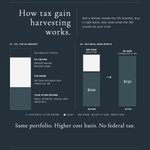
It’s mid-November, and every advisor is hunting for losses to harvest.
We’ve also been realizing gains. On purpose.
Tax-loss harvesting is a great tool, and we use it.
But for a young player, the bigger opportunity is often the opposite move, and it’s only available in years 3 and 4, maybe 5, of their career.
The high-earning years: a drafted player can collect a seven-figure signing bonus in his first two seasons. That money gets invested.
The low-earning years: then come a few seasons in the minors at $30,000 to $40,000.
In 2026, a single filer pays 0% on long-term gains up to $49,450 of taxable income.
On a $40,000 salary with no other income, that leaves $25,550 of room.
We realize gains up to whatever room is left after dividends and interest, buy the same positions back, and reset the cost basis higher.
He pays no federal tax on those gains.
Married during the low-earning years: the joint 0% bracket doubles to $98,900. If his spouse has no income, the room grows to $91,100.
Most of our players get married between October-December. A wedding before December 31 counts for the whole year for tax filing purposes.
Here’s why it matters.
If he sells during his big league years, those same gains would be taxed at 23.8% federally: the 20% top rate plus the 3.8% net investment income tax.
Every dollar of cost basis we reset in the minors is a dollar he never pays that on.
If this sounds a lot like your career and you haven’t had this conversation yet, you should.
If this sounds like your career and you haven’t had this conversation yet, you should. This is the playbook we run, from the signing bonus to the extension to your second career, and every stage in between.

1
3
312
Your NIL LLC isn't saving you a dollar in taxes.
I'm sorry to tell you this, but by default, the IRS taxes your single-member LLC exactly like it taxes you.
An LLC is a legal wrapper. It protects you. By itself, that’s all it does.
The savings come from how you tell the IRS to tax it.
Here's the exact stack we run for our highest-earning NIL athletes and pro clients with considerable off-the-field income:
1. LLC. Protection. Your brand deals stay separate from your personal assets.
2. S Corp election. This is the tax lever. Without it, your NIL profit is subject to self-employment tax of up to 15.3%, on top of income tax.
3. Reasonable salary + distributions. You pay yourself a reasonable salary through payroll. The rest comes out as distributions, which aren't subject to payroll tax.
4. Solo 401(k) + documented deductions. You shelter a real chunk of what's left and stop leaving write-offs on the table.
Most people stop at step 1 and think they’ve won the tax game.
The structure only works as a system.
And it's not for everyone. If your 1099 income is less than, I’d argue $200,000, payroll and filing costs eat the savings. This is for athletes whose off-field money is real money.
Comment "NIL" and I'll send you the one-page breakdown we use to decide if the S Corp election pays off at your number.
Being generous isn’t the problem.
Being generous without a number is.
Every yes to a cousin’s restaurant is a no to the 45-year-old version of you.
1
1
527
You’d never run your company without a CFO.
But you’re running your personal finances without one.
Same founder. Lower standard.
2
385
You can be the most technically skilled advisor in the room and still miss.
Tactics are table stakes.
Multi-state tax returns
Signing bonus structure
Career-ending injury coverage
any competent advisor should handle all three.
What most advisors miss is the human side of this work.
Behind every contract is a person deciding what the money is *for*. Maybe it's time. Maybe it's family. Maybe it's never feeling broke again.
Skip that question and the math can be right while the answer is wrong.
For athletes and entrepreneurs, the money is tied to who they are. A plan that ignores that looks perfect on paper and gets abandoned the first time life gets loud.
A perfect plan for the wrong goal is still the wrong plan.
1
4
492
You don’t just pay tax where you live. You pay it in the states where you play road games.
Your agent fought for every dollar of that contract.
Who’s fighting for how much of it you actually keep?
1
3
629
One of the most common topics we discuss with our clients revolves around personal real estate.
The problem is that the house you're approved for is rarely the house you can afford.
That's especially true for athletes and entrepreneurs, whose income rarely moves in a straight line.
Lenders approve you based on your best recent year. Your mortgage has to survive your worst one.
"We'll refinance later" depends on two things you don't control:
1. Rates fall.
2. Your earnings hold.
Here's how we approach it instead:
1. Buy for your floor, not your ceiling.
Set the payment based on what you'd earn in a down year.
2. Pay your future first.
Fund reserves and investing before the house claims its share.
3. Treat a refinance as a bonus, not a lifeline.
I've watched clients stretch for the bigger house. What it cost them was stress and regret.
The same messaging on the field applies to your personal life. Control the controllables.
1
4
364
Two players. Same $20M career.
One bought what he could afford.
The other bought what he could afford to keep.
Ten years after retirement, only one of them still gets to choose what he does next.
339
The way college athletes are paid is setting them up to fail.
Yet, they can retire with $33 million without ever signing a pro contract.
Let me explain.
It arrives in lump sums, with no taxes withheld, to a 19-year-old who has never filed a tax return.
Here's some of the work we do with the players earning $2M a year.
Start with the tax bill.
NIL is self-employment income. Left alone, $2M a year turns into a tax bill of ~$800,000. If that money isn't set aside the day it lands, it gets spent.
Then treat it like a business, because it is one. Four changes cut that bill by about $125,000 a year:
• An S-corp that pays him a reasonable salary and passes the rest to him as profit. That saves about $32,000 in payroll tax after the cost of running it.
• Real business expenses, run through the company like any other business would. At $100,000 of legitimate expenses, that's about $42,000 less in income tax.
• A Solo 401(k) funded to the $72,000 limit, which takes about $30,000 off his income tax.
• A PTET election, which lets the S-corp pay his state income tax itself. As an individual, his federal deduction for state tax is capped. Paid by the company, all of it is deductible. That's about $20,000 a year.
Then save before he spends. Every year:
• $800,000 (40% of the NIL money) into a brokerage account
• $72,000 into the 401(k)
• $7,500 into a Roth IRA. He keeps doing this one every year for the rest of his life.
After taxes and business costs, that still leaves him $170,000 to $225,000 a year to live on, as a college student.
Let’s assume he doesn’t get drafted.
After age 21 the big deposits stop. The only new money is the yearly Roth contribution. At a 7% average return:
Age 22: $2.8M
Age 30: $4.8M
Age 40: $9.2M
Age 50: $17.5M
Age 60: $33.4M
The Roth is the part most people skip, because $7,500 looks small next to a $2M deal.
By 60 he has three accounts, taxed three ways:
• Taxable brokerage: $28.7M, available at any age
• Tax-deferred 401(k): $3.0M, deducted from 19-21, taxed when withdrawn
• Tax-free Roth: $1.6M from $307,500 of his own contributions
Having all three means he decides each year how much taxable income he shows the IRS. Most people retire with one account and no choices.
None of this takes a special investment. It takes doing the dull things right during those three years, before the spending habits set in.
Parents and players: which of these were you never told about?

Your signing bonus isn’t income.
It’s the money you’ll live on for the 40 years after your last game.
Spend it like a paycheck and you’ll be looking for one when the paychecks stop.
3
4
554
The IRS has released the 2027 tax brackets.
Every bracket shifted up with inflation. The standard deduction climbs to $16,600 for single filers and $33,200 for married couples filing jointly.
Swipe to find your bracket, and to see why earning more never shrinks your take-home pay. 👉


S&P 500: -4.4%.
Nasdaq: -5.5%. Its worst day in 18 months.
That was yesterday.
If you were drafted in the last four years, you’ve mostly watched the market go up.
The S&P 500 bottomed in October 2022. Four years later it was up 118%, more than double.
So a day like yesterday feels like something broke.
Nothing broke. This is what normal looks like.
Since 1980, the S&P 500’s average intra-year drop has been more than 14%. Its average annual gain over the same stretch is 10.7%.
The drops come with the gains.
We saw it in 2025. The market fell 18.9% between February and April and still finished the year up double digits.
Selling in April meant locking in the loss right before the recovery.
You already know this from what you do on the field. One bad game doesn’t end a season. Nobody throws out their whole training program over one Thursday.
Money works the same way. After a day like yesterday, the worst move is to react. That means selling, or running to whatever feels safe or hot this week.
You also have less room for that mistake than almost anyone.
Your career is already the most concentrated bet you’ll ever make. Your portfolio is the part of your life that’s supposed to be patient.
Zoom out and the picture changes. Since 1950, the S&P 500 has been higher in 92% of rolling 10-year periods, not counting dividends.
Your career is measured in seasons. Your money should be measured in decades.
That's why we don’t build your plan for next week. We build it for the 40 years after your last game.
3
7,549
Really good perspective and talking points we’re having with our clients as we head towards Dec. 1.

MLB Lockout: What Players Must Do With Their Money Now 👇
youtu.be/GRD_AOsQ0TM

2
306
Morning thought from the airport on my way to see a client.
Nothing beats persistence matched with feel.
In our business the sales cycle can be years or it could be minutes.
Just the nature of the avatar.
What I’ll say to all of you is this.
My mantra.
do it anyway
It usually has a good probability of working out.
1
10
761