

Independent research on consumer cross-border money transfers: market structure, economics, fintechs, banks, remittances, crypto and stablecoins.
Joined October 2014
- Tweets2.2K
- Following43
- Followers788
- Likes481





BIS got Wise to reveal its marginal cost for a £1,000 GBP→EUR transfer: just £0.84, including only £0.32 for bank fees, treasury, and FX. Most costs come from servicing and compliance. Even if stablecoins were cheaper (they aren't), it wouldn't matter.
bis.org/publications/working…


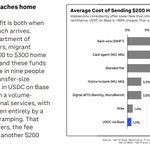
Good to see stablecoin fans finally include digital options like Wise. But “86% cheaper” compares some esoteric 1% USDC costs with a 7.1% fiat blend that includes irrelevant bank wires. Curiously, it doesn't compare with Felix prices.
theblock.co/news/web3/2026-1…

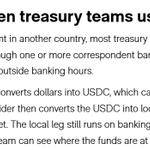
All stablecoins do is shift pre-funding to a local provider, without explaining why anyone would maintain liquidity on someone else's behalf for free.


Stablecoins, behind the scenes.
Our treasury team is using @checkercorp to access liquidity for FX and treasury operations.
Check it out 👇
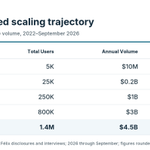
(1/2) While Félix’s growth rate is rapidly decelerating, its cumulative volume, adjusted for inflation, is scaling on par with Wise and faster than Remitly. WhatsApp, referrals, and recipient-driven distribution clearly helped, while stablecoins didn't matter...


(1/3) Felix claims USDC avoids parking pesos in Mexico. Remitly indeed prefunds Mexican payout partners, but Wise already pays locally through SPEI. Felix still needs a provider to supply pesos but has disclosed neither its FX spread nor total payout cost.
youtube.com/watch?v=cH6LSHBC…
(2/2) The unanswered question is whether Félix’s aggressive incentives via external financing deliver unit economics comparable to Wise and Remitly during their first five years, or whether Félix is buying growth, albeit less aggressively than Aspora.
saveonsend.com/money-transfe…

(1/3) Felix claims USDC avoids parking pesos in Mexico. Remitly indeed prefunds Mexican payout partners, but Wise already pays locally through SPEI. Felix still needs a provider to supply pesos but has disclosed neither its FX spread nor total payout cost.
youtube.com/watch?v=cH6LSHBC…
(2/3) Felix credits stablecoins with faster, cheaper transfers. In Colombia, Remitly's local partner already converts funds and pays instantly through Bre-B; Wise pays into local bank accounts and Nequi. Félix has shown no speed or cost advantage over either.
(1/3) Indeed, MGI's annualized stablecoin FX trading rose from $2B to $3B since June, while WU launched USDPT and a card. But these developments concern settlement infrastructure.
bloomberg.com/news/articles/…

(2/3) Two Coinbase customer anecdotes don't tell a story of industry disruption, and $135B in XB stablecoin payments is mostly institutional flows. Felix would have been a more interesting example, yet its pricing and speed are not remarkable.
Every quarter, investors are shocked to rediscover Wise's unique business model, just to immediately forget it.

Wise consumer volumes keep growing almost at 20%, reaching almost $50B per quarter. It is 50% higher than JPMC does per year and twice of BofA.
owners.wise.com/financials/f…


(1/3) Allium makes a better attempt than most to estimate stablecoin XB C2C, but its precision is illusory. Wallet activity reveals neither users’ identities nor payment purpose, so it extrapolates from a tiny geographic sample without validating actual remittance flows.


Our Q3 State of Stablecoins & Payments report is live.
9 months of onchain data. 15+ industry perspectives, including Visa, Stripe, Coinbase, Citizens, Stellar, Moody's Ratings and more.
From stablecoin supply to payments, cards and AI agents.
Download the full report: allium.so/reports/state-of-s…

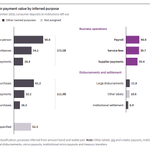
(2/3) In Jan–Sep 2026, $173B tagged C2C × 22% cross-border implies ~$38B, yet $54.1B is separately tagged “remittances.” The geography sample covers just 3% of payment value. Neither is reconciled with the joint FXC–Allium ~$20B for 2025 or FXC Intel/Weber’s 1% forecast.
The only thing funnier than stablecoin players trying to prove their tech is superior for remittances is when they try to prove they are superior to other stablecoin players. Enjoy rumblings of MAJORITY CEO against Felix.
linkedin.com/pulse/four-gene…

Wise consumer volumes keep growing almost at 20%, reaching almost $50B per quarter. It is 50% higher than JPMC does per year and twice of BofA.
owners.wise.com/financials/f…
For the first time, Wise disclosed its Platform’s average take rate: a surprisingly high ~40 bps. A testament to its value proposition, but perhaps also an explanation for its limited penetration among top cross-border players.
investing.com/news/transcrip…
