

Accountant/Investor.
Bath/Bristol
Joined May 2012
- Tweets4.5K
- Following735
- Followers925
- Likes2K

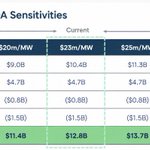


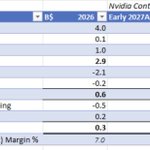



$IREN 2027 ARR guidance hasn’t been given due to the $/MW contract rate variable. Is the answer not a sensitivity analysis table (like they did for btc mining)? Here is my example. Suggestion to @danroberts0101 Stick it on an early slide and make Revenue/Ebitda the Nov earnings focal point 🙏

Block out the noise and focus on why you made it this far as an $IREN investor. 12+ months of laying the foundations to reap the rewards over the next 12+
“If people are trying to bring you down, it only means you are above them”

Sean James retweeted

There are still people out there that doubt $IREN's execution of the signed contracts, the credibility of the announced, but not identified or specified contracts, and/or the unsigned capacity in a severely constrained environment where 3 year deals pay back the whole investment.

Mackenzie UPDATE:
$IREN looks to be laying the groundwork for liquid cooling at Mackenzie while the air-cooled retrofit is still underway.
Drone footage from 9/23 shows black 2" to 3" rigid pipe entering the data hall wall at regular intervals along an open trench that runs the length of the building.
It looks like supply and return branch lines for a liquid cooling system. If you look closely, they go from the wall into buried trunk lines running parallel to the data hall for a future liquid-cooling loop, going in at the same time as the air-cooled GPU fit-out.
Why this is smart sequencing:


Can we expect the 87% EBITDA margin confirmed at the company level for the foreseeable, at scale @danroberts0101 ?

A few people have Thursday's numbers tangled, so let me untangle them.
The majority of the $684m loss is the cost of retiring Bitcoin miners as we convert those sites to AI Cloud. Non-cash. The cloud business underneath ran ~87% gross margins (ex D&A).
Every megawatt that comes off mining goes back on at multiples of the revenue. Recent 3-year AI Cloud contracts are at >$20m per MW (IT), more than double late last year.
And the $25-30bn of forecasted FY27 capex isn't an equity number. Customer prepayments can cover about half the GPU capex. Lenders can fund most of the rest. We raised ~$19bn over the last twelve months and only ~$3bn of it was equity. We haven't borrowed a dollar against the data centers yet either.
$4bn of ARR is contracted, with three sites commissioning between now and year end to bring it online. And that's the 2026 story. The real ramp is 2027, when Sweetwater and the next wave of capacity come into play.
It's delivery time.


Looking forward to next week 👀 $IREN


You can currently buy $IREN at a 45% discount to ATM equity injected prices through Q2 + $3B CN at >$50
