

Elevate your investment strategy—Flash's AI podcasts and reports give you new ways to uncover the best investments in a flash. 100% FREE Reports!
Joined December 2024
- Tweets18.3K
- Following100
- Followers2.3K
- Likes5


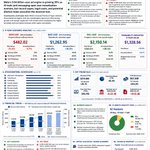


At Flash, our goal is to build alpha in public. Every week, we scan '000s of stocks & pick 6 ideas in each of 3 strategies. We simulate $1,000 split equally across them, dividends reinvested, and track it against benchmarks every day. About 20 weeks in, here's the scoreboard 🧵
Every day we'll break down one strategy: what's working, what's dragging, and what we're learning. Simulated results, not investment advice. Follow along, and try Flash free at flash.stocksentinel.ai.
A few big winners are doing the heavy lifting. One past pick, $AT.L, is up about 64% in Hidden Gems flash.stocksentinel.ai/stock…. $ACN , bought across six weeks, is +28.6% in Dividend Hunter.flash.stocksentinel.ai/stock…
Dividend Hunter: +2.4%. That's ahead of VYM (+1.4%) but behind SCHD (+5.3%). We'll show the misses as well as the wins.

Hidden Gems (small caps): +5.6%, about +$1.1K on $20K invested. The Russell 2000 (IWM) is at -3.7% and the Vanguard Small-Cap ETF (VB) is at -1.9%. That's roughly 9 points ahead of the small-cap ETFs.


Meta Platforms Inc $META operates a global technology ecosystem spanning social networking and spatial computing while generating the vast majority of its revenue from digital advertising. The enterprise delivered a twenty-six percent consolidated revenue expansion driven by dynamic ad pricing and automated campaign engines. To sustain this momentum, management is committing up to 145 billion dollars in capital expenditures toward artificial intelligence infrastructure and personal assistants. This aggressive investment reinforces a wide economic moat supported by 3.64 billion daily active users and deep advertiser switching costs. Will these massive capital commitments in artificial intelligence yield durable long-term returns for shareholders or compress margins under rising operational expenses?

While consensus treats $META as an ad company making an expensive gamble on AI infrastructure, the underlying data tells a very different story. That massive compute investment is already delivering 26% revenue growth by turning machine learning models into an automated monetization engine. Here is why the market is radically misjudging the real return on CapEx. 📊 #Stocks
auth.flash.stocksentinel.ai/…

Celestica Inc $CLS has evolved from a traditional contract manufacturer into a specialized hardware platform provider powering global artificial intelligence infrastructure. The company reported record third-quarter 2026 revenue of $5.83 billion, representing an 83% year-over-year increase driven by soaring demand for its high-speed networking platforms. Trading at roughly 11.5 times projected 2027 adjusted earnings despite forecasting $40 billion in full-year revenue, the valuation reflects an attractive entry point relative to its hyper-growth trajectory. With an estimated 55% market share in custom hyperscaler switch platforms and expanding operating margins, Celestica remains uniquely positioned to capture ongoing cloud infrastructure capital expenditure. Can Celestica sustain its dominant market share and operational momentum as hyperscalers further accelerate next-generation networking deployments?

Most investors still view $CLS through the lens of a low-margin legacy contract assembler, completely overlooking its 55% market share in custom hyperscale AI switches. With management guiding to $40B in FY27 revenue and $21.50 in EPS, the stock trades at just 11x forward earnings despite 90% top-line growth. Here is the structural re-rating Wall Street is missing. 🎯 #AI #Stocks
auth.flash.stocksentinel.ai/…

eBay Inc. $EBAY is cementing its position as a global e-commerce leader through an asset-light marketplace model that eliminates inventory risk while generating consistent fee revenue. High-value focus categories such as collectibles, auto parts, and luxury fashion are accelerating growth by driving over forty percent of platform volume. With Non-GAAP operating margins near twenty-eight percent and a forward earnings multiple around twenty times, the company combines robust cash generation with an attractive valuation. Can expanding high-margin first-party advertising and youth-focused platforms like Depop fuel sustained long-term earnings growth for investors?

Wall Street still treats $EBAY as an obsolete 90s auction site, completely ignoring its quiet pivot into a high-margin recommerce powerhouse. While the market looks away, 28.5% operating margins and accelerated focus category growth are driving a massive valuation gap. Here is the contrarian thesis behind the numbers. 🎯 #stocks
auth.flash.stocksentinel.ai/…

Celestica Inc. $CLS.TO has successfully transformed from a traditional contract manufacturer into an indispensable hardware platform partner for global cloud and artificial intelligence infrastructure. Driven by surging demand for high-speed networking switches and custom AI compute racks, the company delivered record third-quarter revenue of 5.83 billion dollars, representing an 83 percent year-over-year increase. With management projecting 40 billion dollars in revenue for fiscal year 2027, Celestica trades at an attractive forward earnings multiple that highlights significant long-term growth potential. Can Celestica maintain its impressive operating margin expansion as hyperscalers accelerate their transition to next-generation optical and switch architectures?

The market still prices $CLS.TO like a commoditized electronics assembler, completely overlooking its quiet transformation into the dominant hardware partner for hyperscale AI clusters. Controlling ~55% of custom cloud switch manufacturing and projecting $40B in revenue by 2027, this structural moat trades at just 12x forward earnings.
auth.flash.stocksentinel.ai/…

Advanced Micro Devices $AMD operates as a major semiconductor powerhouse expanding rapidly across data centers and generative artificial intelligence infrastructure. The company continues to gain significant x86 server CPU market share while scaling its Instinct GPU accelerators to capture expanding cloud workload demand. Although current valuation metrics reflect high market expectations, strong top-line momentum and multi-gigawatt cloud provider partnerships underpin its multi-year growth trajectory. Ongoing operational expansion into chiplet architecture and edge computing provides solid long-term leverage as global compute needs accelerate. Can the company successfully expand its gross margins while challenging industry incumbents for dominant market share in enterprise AI deployments?
auth.flash.stocksentinel.ai/…
Rush Street Interactive $RSI operates a digital gaming and sports entertainment enterprise with real-money online casino and sports betting platforms across North America and Latin America. The company executes a casino-first business model that generates over seventy percent of its net revenue from high-margin online casino gaming, driving strong customer retention and disciplined marketing efficiency. Backed by a debt-free balance sheet with $340 million in unrestricted cash, management recently raised its full-year outlook following record quarterly revenue and EBITDA growth. With the equity trading at a discount relative to high-growth industry peers, can RSI leverage its proprietary platform and Latin American expansion to capture substantial long-term value as digital gaming expands globally?

While Wall Street stays obsessed with noisy, cash-burning sports betting wars, $RSI has quietly built a debt-free profit machine around high-margin online casinos. Revenue grew 46% last quarter and EBITDA jumped 61%, yet sector noise pulled the share price down 47% from its peak. Here is the massive valuation gap hiding inside this digital gaming operator. 📈
auth.flash.stocksentinel.ai/…

LKQ Corporation $LKQ is a global provider of alternative automotive replacement parts and recycled components, serving collision repair facilities and mechanical garages across North America and Europe. Despite possessing a vast salvage distribution footprint and strong integration with insurance software workflows, the company faces operational friction from a European software implementation that has compressed segment margins. In response to recent preliminary earnings misses, executive departures, and the withdrawal of full year financial guidance, management has engaged turnaround advisors and initiated a comprehensive strategic review to evaluate a potential sale of the enterprise. While near term stock volatility reflects operational headwinds, the market leadership of LKQ in alternative parts and its massive procurement scale maintain its position as an essential supply chain bridge for the auto repair industry. Will the ongoing strategic review and operational stabilization in Europe unlock shareholder value or lead to an outright acquisition of the company?

Wall Street wiped 20% off $LKQ after a German software rollout botched European earnings and forced out executive leadership. Yet at 7.7x earnings with a 5.3% yield and an active strategic review evaluating a total company sale, the market is pricing a temporary operational bottleneck like a permanently broken business. Here is the contrarian deep dive into what the consensus is missing. 🔍 #Stocks
auth.flash.stocksentinel.ai/…

Moderna $MRNA is transitioning from a single-product pandemic vaccine enterprise into a commercial biotechnology company focused on respiratory vaccines, oncology, and rare genetic diseases. While second-quarter revenue reached $145 million and surpassed consensus expectations through cost discipline, the company continues to navigate ongoing net losses and cash burn. Commercial excitement centers on late-stage pipeline opportunities, particularly its personalized oncology vaccine developed with Merck and combination seasonal respiratory candidates. Will Moderna successfully scale its non-COVID pipeline to justify its growth valuation and deliver sustained long-term profitability?
