

Freight trader. Views are my own and not investment advice.
Geneva
Joined October 2025
- Tweets1.2K
- Following10
- Followers2K
- Likes435

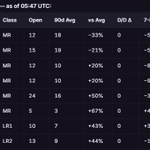




Is TC14 versus the HOGO swap a successful pair trade? Leonidas AI says no: a correlation of -0.19 over one year and -0.17 over three years. The diesel arb link is real, but the pair trade signal is overwhelmed by USGC MR tonnage count fluctuations. The cleaner trade is TC14 outright as the diesel arbs into Europe and LatAm open and shut. Leonidas AI is now live.
USGC VLGC tonnage has lengthened, with 9 ships open in the 35-day ahead window against a 90-day average of 6. BLPG3 has been offered most of the day for both November and December contracts, and November is looking closer to $300/mt value now against the $312/mt settle on Monday. Spot BLPG3 printed sideways today. The Houston to Chiba arb is shut by a material amount at -$53.20/mt for the 6 to 10 January delivery window and worse still through February, so freight and the Mont Belvieu to FEI spread has to widen before it opens. USGC FOBs moving back to single digits would help too. US propane and propylene stocks were 105.8 MMbbl in the week ending 16 October, against 103.2 MMbbl a year ago and a five-year average of 94.0 MMbbl. Stock levels are not the main driver behind the shut arb. Freight rates should weaken further from here. Charterers, let the USGC VLGC market come to you.
Mercuria v Baltic Exchange opened in the London High Court on Monday. Mercuria argues the Baltic should have suspended TD3C in early March once the US and Israel conflict with Iran disrupted Hormuz, on the basis the assessment stopped reflecting the physical market and breached the Benchmarks Regulation. It has dropped its damages claim and now seeks a declaration that the assessments should have been suspended. The Baltic says the route never lacked fixtures and that voiding more than eight months of prints would be highly destabilising. Anyone holding TD3C-linked contracts or FFA positions should be following this daily.

Clean tonnage report: NWE MR is at 12 ships against a 90-day average of 18 and USGC at 15 against 19, both down 5 on the week. East of Suez still sits above average, with AG MR at 12 against 10 and down 8, WCI at 12 against 10 and down 9, and SEA at 24 against 16 and down 3. AG LR2 is at 13 against 9 and also tightening. The only week-on-week builds are Far East MR at 5 against 3 and AG LR1 at 10 against 7.

Leonidas AI: The arb that opened: Houston → Rotterdam diesel (TC14 lane) — opens in the 6–10 November load window at +$1.53/mt, and widens further to +$5.66/mt for the 11–15 November window. The prompt (26–31 Oct) is still closed at −$6.7/mt, but the forward strip is cracking open. This is the first meaningful opening on the primary TC14 lane in the current cycle. The list is tight (15 vs 19 average) but the FSD points lower over 7 days — the arb opening improves the demand case.
Six of the eight Houston mid-November loading arb windows are open. Diesel to Buenos Aires leads at +$20.10 cpg, gasoline to San Jose at +$15.25 cpg and gasoline to Esmeraldas at +$6.25 cpg, with Santos at +$3.05 cpg and Rosarito at +$0.25 cpg marginal. Transatlantic diesel to Rotterdam reopened materially at +$19.00/mt. Neither of the two shut windows improves in the forward months: Barcelona diesel is at -$0.75/mt for November against -$17.00/mt for December, and Rotterdam naphtha is materially shut through the curve. USGC MR supply in the seven-day ahead window is 15 ships against a 90-day average of 19. Owners, the open arbs will drive vessel demand into November on short tonnage, so push for higher than last done this week, but monitor the incoming ballaster counts closely.
🚢🚀

A dozen open tabs of voyage economics per fixture? Leonidas AI does the same work in under a minute.
It gives you multi-voyage TCEs up to 12 months forward, chained voyage by voyage and built on your ship’s fuel consumption, capacity and port costs, with live freight and bunker rates. Live arb margins show where vessel demand is heading.
Position your ship where the market is going.
Try Leonidas AI: spartacommodities.com/leonid…
#oott #oiltrading #commoditytrading #energyindustry
Michael Ryan retweeted

A dozen open tabs of voyage economics per fixture? Leonidas AI does the same work in under a minute.
It gives you multi-voyage TCEs up to 12 months forward, chained voyage by voyage and built on your ship’s fuel consumption, capacity and port costs, with live freight and bunker rates. Live arb margins show where vessel demand is heading.
Position your ship where the market is going.
Try Leonidas AI: spartacommodities.com/leonid…
#oott #oiltrading #commoditytrading #energyindustry
NWE MR tonnage is at 4 ships against a 90-day average of 18, the tightest count so far this year, with the FSD model forecasting spot TC2 at WS 239 against a WS 231 assessment. The arbs are not driving the rally, with Amsterdam to New York gasoline shut at -$19.70 cpg and Rotterdam to New York diesel at -$31.40 cpg for November. This is a pure tonnage supply rally. The Med is the main driver, with Handy supply at 5 open ships against an average of 15 and TC6 running from WS 340 to WS 528 this month, pulling MRs off the NWE list for Med stems instead of transatlantic business. The Katherine Lady went on subs for Continent to Mediterranean at WS 295 against WS 222.5 for the Champion Julie to the United States. Owners, press last done towards WS 239 and take the Med stems.
TD3c paper is rallying back to spot. November traded at WS 1,050 on Thursday and firmed to WS 1,060, then on Friday the November/December spread traded at WS 50, with November at WS 1,100 and December at WS 1,050, against a spot settle of WS 1,214. November had priced down to WS 990 earlier in the week on the shadow fleet sanctions headlines, so the overreaction had another leg lower in it before it turned. Fundamentals did not change. The Sparta Crude Grade RBI has Arab Light into the Far East on a VLCC at -$8.18/bbl and stays undervalued forward at -$4.26/bbl for November, with tonnage at 28 ships against a 90-day average of 34. Paper is still undervalued with the US midterms on 3 November on the horizon.
October has already been the worst month on record for attacks on commercial shipping in the Strait of Hormuz and nearby waterways, with 28 incidents against 14 in September and 16 in August, according to Washington Institute for Near East Policy data going back to 2017. The regional earnings premium remains high. A 270,000 mt VLCC on the benchmark Ras Tanura to Ningbo run earns a round voyage TCE of $1,385,531 per day for spot and $1,321,991 per day for November, with Fujairah to Ulsan at $659,256 and $626,732 per day. At least 14 fixtures were reported out of the Arabian Gulf, Omani Gulf and Red Sea across Thursday and Friday, including the Sea Majesty for Yanbu to East at WS 750 for a 7 to 9 November laycan and the DHT Panther for Yanbu to Ulsan at WS 675. Owners, do not discount spot any lower.
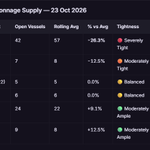
Leonidas AI: Tightest DPP Segment - NWE Aframax (TD7), by a wide margin
NWE Aframax is the standout. 42 open vessels against a 57-ship average is a 15-vessel deficit, -26.3% below the rolling mean — that's a severely tight list and it's still tightening. The week-on-week move is the most striking data point in this table: -19 vessels w/w. That's a sharp draw in a short window and the kind of move that gives owners real leverage on TD7 prompt fixtures.

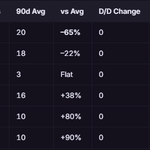
Leonidas AI: Atlantic MRs — the dominant story,
Both USGC and NWE MR lists remain at 7 vessels, 63% and 61% below their 90-day averages respectively. The FSD continues to point higher on both TC14 and TC2, and platform demand is strong — particularly USGC at +8 implied vessels, the strongest reading on the board. Spot TC14 is at WS 398 and spot TC2 at WS 207. Owners hold the leverage here.

The provenance of the USGC MR demand curve changes considerably after November. The Houston to Buenos Aires diesel arb is the prompt standout at +$21.00 cpg for November, but it fades to +$4.30 cpg in December and turns negative at -$3.95 cpg for January, and San Jose gasoline does the same, from +$11.55 cpg for November down to +$4.60 cpg by January. What replaces these demand centres is the transatlantic arb. Houston to Rotterdam diesel is open at +$3.75/mt for November, dips to +$1.25/mt in December, then widens to +$13.50/mt for January and +$30.00/mt for February. The Santos diesel arb is structured similarly, from +$1.45 cpg in November to +$6.60 cpg in January. LatAm demand for both diesel and gasoline is supportive into November, and then transatlantic demand begins to carry more weight behind it.
Spot USGC MR tonnage is at 7 ships against a 90-day average of 19, with strong incremental demand, and the FSD model forecasts WS 424 against a WS 398 assessment for the 28 October to 6 November window. TC14 paper rallied hard yesterday, with November trading at WS 410 and firming up to WS 445 before softening back to WS 425, and December trading at WS 420 up to WS 435, back down to WS 420 and firming again to WS 430. The chop is in part due to USGC ballaster counts up 65% week on week. Owners, push to the FSD forecast of WS 424 but no higher, in line with November TC14 paper; the ballasters are incoming.
Your daily DPP brief in a single prompt. Leonidas AI analyses the latest Hormuz escalations, tonnage counts, crude RBIs and TCEs across dirty freight markets: every route in steep backwardation, TD7 the standout long trade with the NWE Aframax list at 42 open ships against a 57-ship average, Afras and Forties crude undervalued, and a November 2026 TCE of $472,730/day. Owners, charterers, traders, analysts: start your day a leg ahead of the competition.
Houston loading gasoline arb margins are improving across the board. Houston to San Jose gasoline is at +$11.90 cpg for mid-November against +$9.40 cpg yesterday, and the shut routes are closing the gap, with Esmeraldas at -$1.50 cpg for November from -$3.70 cpg and Rosarito at -$1.50 cpg from -$5.00 cpg since 15 October. Ships are already getting fixed. The Torm Belis fully fixed for USGC to Brazil at WS 510 with gasoline for a 30 October laycan, and both Pozos Colorados cargoes were gasoline, the Elegant Voyager at $1.475m LS and the Gem Turquoise at $1.45m LS, for 26 October laycans. Owners, the incremental vessel demand is spreading beyond just diesel.
A wave of MRs went on subs in the USGC yesterday and the tonnage count has dropped from 20 ships to 7 against a 90-day average of 20. Incremental demand has improved materially and the FSD model now forecasts spot TC14 at WS 404 against WS 376 for the 27 October to 5 November window. The November diesel arb into Europe has reopened with it: Houston to Rotterdam is at +$4.28/mt for a 10 November loading, widening to +$15.89/mt for 6 to 10 December delivery, with Houston to Buenos Aires diesel at +$24.40 cpg for November on top. Close to 15 MRs went on subs yesterday, including the Largo Alpha for USGC to UK Continent Mediterranean at WS 365 and the Wisco Adventure for USGC to West Coast Central America at $3.2m LS, both for 25 to 26 October laycans. TC14 paper firmed through the day, with November trading at WS 390, then WS 395 and WS 405, and December at WS 385, then WS 400. Owners, push higher; today will be firmer again.
Your CPP daily brief in one prompt. Leonidas AI pulls the latest market news, tonnage lists, open arbs and FFA forecasts for every region: the USGC MR count at just 7 open ships against a 20-vessel baseline, with TC14 spot forecast higher to WS 403; East of Suez tonnage now long; TC5 at a 52-week high of WS 1,093; and Jubail to Chiba naphtha open at +$20.70/mt. A market call for owners, charterers and traders in every region.
Leonidas AI: USGC is the standout. Seven open MRs against a 90-day average of 20 is severely short — the tightest region on the board by a wide margin. The FSD now points higher over the next 7 days (WS 376 current, WS 403 forecast), the bottom for spot TC14 is in. The list has tightened by five vessels over the past week. Owners have clear leverage here.
