

I compile hedge fund pitches Database: 3000 pitches & 2000 fund letters ↓ https://nitter.gq/t.co/P8lwLZf1zW Newsletter : https://nitter.gq/t.co/uZjksJmJOO
Paris
Joined August 2023
- Tweets4.9K
- Following818
- Followers10.7K
- Likes1.6K






Pinned Tweet
Q3 fund letters are starting to come out. 170 new letters are already on the site since Oct 1.
Good time to show what I've built to save you hours of reading fund research 🧵

Platinium AM Platinum Trust is long CRH plc ($CRH) — their thesis in 5 points:
• CRH's share price has fallen approximately 35% from its early-2026 peak, but the fund says its competitive position, management and longer-term earnings power are fundamentally unchanged.
• CRH owns the world's largest reserves of construction aggregates; at the end of 2025, reserves totalled approximately 24 billion tons, and the proposed Arcosa deal adds approximately 1.3 billion tons plus 35 million tons of annual production in North America.
• Around 95% of revenues are connected to aggregates, and CRH's strategy is to maximise reserve value through integrated building materials operations and services across approximately 4,000 sites in North America, Europe and Australia.
• Current conditions are challenging: higher mortgage rates are weakening housing affordability, the Middle East conflict has increased energy, transport and other input costs, and the industry is trying to recover these costs through pricing, which takes time when demand is mixed.
• The fund says the Arcosa acquisition is sound given CRH's integration record, but the price was full; it no longer expects CRH to meet previous 2026 earnings guidance, and believes the share price decline has been greater than the reduction in underlying business value.
Source → hfbestideas.com/letters?open…


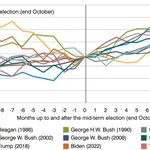
📊 S&P 500 around US midterm elections
Source: GAM Investments

ALT Chart: S&P 500 around US midterm elections — from a research article by GAM Investments.
📊 US corporate yield minus S&P 500 earnings yield
Source: Voya Investment Management

ALT Chart: US corporate yield minus S&P 500 earnings yield — from a research article by Voya Investment Management.
50 new pitches found in hedge fund reports this week:
🔹 AAON, Inc. (AAON US) by Baron Real Estate Income Fund
🔹 Altius Minerals (ALS CN) by Liontrust Sustainable Future Global Growth Fund
🔹 Amrize Ltd. (AMRZ SW) by Artisan Partners International Value Strategy
🔹 Apple (AAPL US) by Wedgewood Partners U.S. Large Cap Growth Strategy
🔹 Armstrong World Industries, Inc. (AWI US) by Baron Real Estate Fund
🔹 ASML Holding N.V. (ASML NA) by Royal London AM Global Equity Diversified Fund (IRL)
🔹 ASML Holding NV (ASML NA) by Brown Advisory Global Leaders Sustainable Fund
🔹 ATI Inc (ATI US) by Brown Advisory Mid-Cap Growth Strategy
🔹 Autonation (AN US) by Alluvium AM Conventum
🔹 BE Semiconductor Industries (BESI NA) by Baillie Gifford Global Alpha
🔹 Boston Scientific Corporation (BSX US) by Brown Advisory U.S. Flexible Equity Fund
🔹 Brambles (BXB AU) by Harris Associates International Strategy
🔹 Carrier Global Corporation (CARR US) by Aristotle Value Equity Strategy
🔹 Clearwater Paper Corporation (CLW US) by Longleaf Partners Small-Cap Fund
🔹 Compagnie Financière Richemont (CFRUY SW) by GreensKeeper Value Fund
🔹 Corpay (CPAY US) by Aristotle Small/Mid Cap Equity Strategy
🔹 Cytokinetics (CYTK US) by JAG Capital Management Small Mid Cap Growth Strategy
🔹 DexCom (DXCM US) by Liontrust Balanced Fund
🔹 Diploma (DPLM LN) by Aoris International Fund
🔹 DSV A/S (DSV DC) by The London Company International Equity Strategy
🔹 Exsitec by Kavaljer Quality Focus
🔹 Flowco (FLOC US) by FPA Queens Road Small Cap Value Fund
🔹 Fraport (FRA GR) by L1 Capital Long Short Fund
🔹 FuboTV (FUBO US) by White Brook Capital Ethical Strategies
🔹 GE Aerospace (GE US) by Brown Advisory Global Leaders Sustainable Fund
🔹 Haemonetics Corporation (HAE US) by Ariel Investments Small Cap Value Strategy
🔹 Honeywell Aerospace (HON US) by Broyhill Equity Composite
🔹 Honeywell Automation (HONA US) by Cambiar Investors Opportunity Fund
🔹 InnovAge Holding Corp. (INNV US) by Argent Capital Management Focused Small Cap Strategy
🔹 KLA (KLAC US) by Baillie Gifford Positive Change Strategy
🔹 Lam Research (LRCX US) by Baillie Gifford Long Term Global Growth
🔹 Lennar Corporation Class A (LEN US) by Brown Advisory Global Value Select Strategy
🔹 Moody’s Corporation (MCO US) by Akre Capital
🔹 Old Dominion Freight Line (ODFL US) by Wedgewood Partners U.S. Large Cap Growth Strategy
🔹 Palantir Technologies (PLTR US) by Artisan Partners Global Opportunities Fund
🔹 PWR Holdings (PWH AU) by Ganes Capital Focused Value Fund
🔹 Regal Rexnord Corporation (RRX US) by Argent Capital Management Large Cap Strategy
🔹 RELX (REL LN) by WS Lindsell Train UK Equity Fund
🔹 Salesforce (CRM US) by Antipodes Global Fund
🔹 Shopify (SHOP US) by Polen Focus Growth
🔹 Somnigroup International Inc. (SGI US) by The London Company Mid Cap Strategy
🔹 Stifel Financial Corp. (SF US) by Argent Capital Management Dividend Select Strategy
🔹 Suja Life (SUJA US) by Minot Light Capital Appreciation Fund
🔹 Taiwan Semiconductor Manufacturing Co., Ltd. (2330 TT) by Alger International Opportunities Fund
🔹 Telephone & Data Systems (TDS US) by Middle Coast Investing Equity Portfolios
🔹 The Southern Company (SO US) by Nexus Investment Management ULC
🔹 Thermo Fisher Scientific (TMO US) by Lindsell Train Global Equity Fund
🔹 Verisure by Harris Associates International Small Cap Strategy
🔹 VSE Corp. (VSEC US) by Conestoga Capital Advisors Small Cap, SMid Cap, and Micro Cap Strategies
🔹 Waystar Holding (WAY US) by Diamond Hill Select Fund
-> hfbestideas.substack.com/p/5…


Brown Advisory Global Leaders Strategy's latest quarterly letter — key takeaways:
• The portfolio remains a concentrated stock-picking strategy built around differentiated customer value, recurring revenues, pricing power, strong cash generation and low leverage, with the team emphasizing patience over a five-year horizon but warning that patience must not become inertia.
• Market leadership has been unusually narrow, especially around AI and large-cap tech, and the team is intentionally broadening research beyond the obvious AI beneficiaries to identify second- and third-order effects across industries and value chains.
• AI is treated as a tool for testing assumptions and connecting information, not a substitute for investor judgment, challenge and accountability.
• Semiconductors remain strategically important, but the manager is explicitly underwriting cyclicality, capital inflows and possible demand normalization; ASML, TSMC and Nvidia are viewed as businesses that can strengthen their positions through an industry downturn.
• Financials were a key area of strength, led by Deutsche Börse, B3, Visa, Mastercard and Charles Schwab, reflecting a preference for financial-market infrastructure and payment businesses with structural growth and increasingly recurring revenues.
• Rentokil remains under review after weaker-than-expected North American execution, especially in commercial pest control: the team still likes the resilient industry and potential for margin and capital-efficiency improvement, but wants clearer proof of a turnaround before getting more constructive.
• New positions were initiated in HCA Healthcare and MTU Aero Engines: HCA for non-deferrable healthcare demand, local market density and disciplined capital allocation; MTU for aircraft aftermarket economics and expected improvement in free-cash-flow conversion.
• PT Bank Central Asia was exited despite strong operating performance because rising political, regulatory and policy risks in Indonesia reduced the stock’s probability-weighted attractiveness.
• The process itself is being refined around substitution, competition, regulation, financial risk, management quality, company lifecycle and a broader range of outcomes, reinforcing that the team is actively trying to widen the opportunity set without abandoning its quality discipline.
Read the full letter → hfbestideas.com/letters?open…

Baillie Gifford's report on Moderna — key points:
• Moderna’s positive Phase 3 melanoma result suggests its mRNA technology could become a broader, personalised cancer-treatment platform, but regulatory, manufacturing and clinical risks remain.
• Baillie Gifford invested in Moderna’s December 2018 IPO; the shares later gained more than 2,000 percent before falling 95 percent, exposing the risks in its position sizing and conviction.
• Covid vaccine sales reached $36bn through 2022, leaving Moderna with about $18bn in cash and investments, but collapsing demand, excess manufacturing capacity and execution problems subsequently eroded its finances.
• Management responded with cost reductions, a narrower focus on the most promising programmes and stronger commercial execution; Baillie Gifford kept a smaller holding as its conviction and the risk-reward balance changed.
Halvio Capital is long Master Drilling Group Limited ($MDI) — their thesis in 5 points:
• Global leader in raise boring for mining, with 80% of revenues tied to raise boring worldwide, not one region, and a history of strong profitability
• Backlog has doubled recently and sits at an all-time high of $1 billion; gold is 38% of that amount, and the company says the pipeline is now over $1 billion
• With a market cap just under $150 million, MDI trades at under 4x earnings, 3x EV/EBIT, 2.3x EV/EBITDA and 0.63x book value
• Growth could come from mining budgets tied to the metal bull market, plus new tech: Shaft Boring System trials ran at 3 to 5 metres per day vs 1 to 2 metres per day, with potential for 5 to 10 metres per day by next year
• Risks: Johannesburg Stock Exchange listing limits access and price discovery, stock is in South African Rand while reporting is in USD, and it is cyclical despite revenue growth in all but one of the past 10 years
Source → hfbestideas.com/letters?open…


Desert Lion Capital Fund I, LP is long iOCO ($IOC) — their thesis in 5 points:
• iOCO is one of South Africa’s largest IT services companies, covering software implementation, managed IT services, cloud/data/automation/AI, cybersecurity, custom development, payroll/HR, legal/risk/forensics, and industrial systems for mining, utilities and manufacturing.
• The business has turned around under new management and a strategic activist shareholder: EPS was up +42% YoY to 57cps, ROIC was 26%, ROE was 35%, and net debt fell to 0.2 times Net Debt to EBITDA.
• The stock is under the radar at a R2.5bn ($150m) market cap, with no sell side coverage, and the market is also weighed down by a tarnished EOH history.
• iOCO trades at 400cps and 7 times trailing PE; management sees 200 cents in FCF per share over the next 2 years, which it wants to use for earnings-accretive acquisitions and buybacks of 20% of outstanding shares.
• Desert Lion’s base case for FY2027 is EPS of around 68cps, implying about 5.9 times forward earnings with EPS growing at circa 20% per annum.
Source → hfbestideas.com/letters?open…

Magellan Asset Management's report on Crown Castle — key points:
• Crown Castle offers an attractive combination of predictable cash flows, structural growth and a 6.2% 2027 AFFO yield despite recent market weakness.
• Crown Castle operates approximately 39,700 tower and rooftop sites in the US, with about 71% located in the country’s top 100 trading areas.
• North American mobile data traffic grew by an average of 25% per year between 2015 and 2025, supporting additional tenants, larger antennas and higher rental income with limited incremental costs.
• Each tower generates approximately US$95,000 per year on average, while long-term contracts include rent escalators of around 3% and largely predictable operating costs.
Cedar Grove Capital Management Multi-Strategy's latest quarterly letter — key takeaways:
• The drawdown was framed as a macro shock, not a fundamental one: the manager points to the 10-year Treasury moving above 5%, persistent inflation fears, fiscal uncertainty, and heavy AI-related debt issuance as the real pressure on the portfolio, while stressing that operating performance at the businesses owned has continued to improve.
• Market breadth deteriorated materially even as small-cap indices held up, and the manager is watching to see whether participation broadens again or whether index levels have to fall to force that divergence to close.
• The portfolio remains highly concentrated in 13 longs, with a deliberate bias toward profitable businesses, strong industry tailwinds, modest leverage, and balance-sheet resilience; gross leverage was raised to 106% to lean into discounted valuations.
• The manager made a meaningful portfolio reset: closed longs in MTY Food Group, uniQure, ClearPoint Neuro, and Suja Life, exited numerous shorts, and added exposure to ABVX, EVLV, GRID.TO, HIMS, KITS.TO, LNSR, NKTR, NURS.V, REAL, and STLN.
• New long Zedcor is a mobile surveillance and monitoring provider; OneSpaWorld was added because it looks mispriced relative to resilient cruise demand; Auxly Cannabis was initiated as a vertically integrated Canadian producer with improving revenue, EBITDA, and free cash flow.
• Evolv Technologies remains the largest position and the clearest core conviction: the manager cites recurring subscription revenue, growing ARR and contracted obligations, improving margins, and continued guidance increases, while acknowledging the overhang from prior revenue-recognition issues, regulatory scrutiny, valuation compression, and possible acquisition interest.
• The RealReal is another major contrarian bet, viewed as a turnaround in luxury resale driven by higher-quality consignment growth, AI-enabled authentication, improving EBITDA margins, rising GMV, and network effects between buyers and consignors; the main risks remain 4.4x leverage, consumer weakness, and take-rate compression.
• Abivax and Nektar Therapeutics are treated as catalyst-driven biotech positions whose valuations have been pressured by rising yields and temporary uncertainty, but where the manager still sees attractive long-term drug economics and development prospects.
• The throughline is a classic deep-value, research-intensive approach: buy companies below estimated intrinsic value, tolerate volatility, and stay invested when fundamentals are improving even if the stocks are being punished by the market.
Read the full letter → hfbestideas.com/letters?open…
📊 Growth signals beneath the surface
Source: Legal & General Investment Management

ALT Chart: Growth signals beneath the surface — from a research article by Legal & General Investment Management.

