

Your seat at the quant venture table, turning data into actionable insight
New York, USA
Joined November 2020
- Tweets128
- Following190
- Followers74
- Likes5





Oratomic: $475M Series B at ~$5.4B, up from ~$1.5B three months ago.
The pitch: a useful quantum machine needs ~10,000 qubits, not 1M. Six top funds co-led.
Gartner says over half of quantum startups may close by 2030.
Priced before any revenue.
@TeamOratomic
go.systematicventures.com/sv…

TypeSafe AI: $40M seed at ~$200M, then an $870M Series A at $7.5B three weeks later. a16z led.
~37x step-up. The adoption claim, a third of the Fortune 500, is the company's own.
Price discovery is outrunning access.
@typesafeai

See our @typesafeai profile at go.systematicventures.com/sv…?

Anthropic: $965B at the last private round. $2T+ floated for the IPO.
A $2T listing is ~2x the Series H mark and works only if growth barely slows. Reuters says investors are tempering expectations as it does.
Public buyers pay for forward revenue.

See our @reflection_ai profile at go.systematicventures.com/sv… for free.


FT: @nvidia in early talks to buy @reflection_ai or invest more. Reuters couldn't verify.
One structure floated: acqui-hire. Hire the staff, license the tech, possibly avoid a lengthy regulatory review.
A $25B headline means little until you know how the exit pays out.

FT: @nvidia in early talks to buy @reflection_ai or invest more. Reuters couldn't verify.
One structure floated: acqui-hire. Hire the staff, license the tech, possibly avoid a lengthy regulatory review.
A $25B headline means little until you know how the exit pays out.
Higher rates and stickier inflation do not kill venture, they reprice it: punishing distant, capital-hungry cash flows, and rewarding companies that reach real revenue with finite capital and durable pricing power.
Full brief in the reply.
Crusoe: $3.9B Series F at $30.9B. Lead investors: Mubadala, QIA, GIC. Three sovereign funds, one round.
Meanwhile a @CoreWeave -tied data center just paid a 2.7-point premium to raise debt.
Equity's still paying up. Debt's getting nervous.
@CrusoeAI
See our @CrusoeAI profile at go.systematicventures.com/sv…

Nearly 2,500 VC funds tracked since 2000: emerging managers beat established firms on DPI, IRR, and TVPI.
2026 capital allocation: 71.9% still went to funds over $1B, up from 49% in 2025.
The data says one thing. LPs did the other.

XDOF: $70M Series A in June. Talks for a $1.2B Series B now, led by 8VC. 17x in three months.
It's not a robotics company. It's the data pipeline training every robotics company's models.
That's the real chokepoint.
@xdofai
XDOF profile:
go.systematicventures.com/sv…?

HiddenLayer: $100M Series B led by Delta-v Capital.
Investors include Morgan Stanley and Microsoft's M12.
A bank and a hyperscaler underwriting AI security tooling. That's procurement money.
$155M raised since 2022.
@hiddenlayersec
go.systematicventures.com/sv…

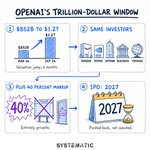
OpenAI's next round could price at $1.2T. Six months ago it was $852B.
Same investor list both times: Amazon, Nvidia, SoftBank, BlackRock, Temasek.
IPO isn't coming until 2027. The private markup already happened.
@OpenAI

Ontario Teachers'. GIC Singapore. Goldman Sachs Alternatives. D.E. Shaw.
Those aren't venture funds. That's an IPO preparation committee.
Ramp: $750M at $44B. $1.5B ARR. 5x in 24 months.
@tryramp

See our in-depth research on @tryramp at go.systematicventures.com/sv…

Cursor ARR: $100M → $500M → $1B → $2B . In 13 months.
@SpaceX preempted the fundraise with a $60B acquisition right.
The exit might not be an IPO. It might be a bilateral private deal.
Investors without cap table access don't get a second shot. @cursor_ai

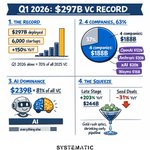
Q1 2026: $297B in global VC. +150% YoY.
OpenAI ($122B), Anthropic ($30B), xAI ($20B), Waymo ($16B) = 63% of all of it.
Seed deal count: -31%.
Capital concentration this extreme doesn't reduce opportunity. It concentrates it elsewhere.

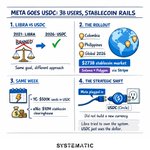
Meta started paying creators in USDC this week.
Colombia, Philippines, Solana, Stripe. Libra tried building a new monetary system. USDC just attaches to the dollar.
Same week: @ycombinator seeds in USDC. @a16z backs a stablecoin clearinghouse. GENIUS Act moves. @Meta

Blackstone co-invested in a 2-year-old AI coding startup at Series C.
Factory: $150M at $1.5B. Droids handles the full software development life cycle autonomously. Customers: Nvidia, Adobe, EY.
They don't do this for developer productivity plays. They do it when AI starts replacing labor at portfolio scale.
