




Pinned Tweet
I’ve been on X for a few months now, but I've never properly introduced myself.
Hi, I'm Tõnis
24 years old
Studying Mechanical engineering
🇫🇮 Investor
Mainly growth stocks, $META $SOFI $NBIS
Sharing my buys and sells, longer write ups on businesses that I've found interesting and some other things that comes to mind
Looking to connect with fellow investors!


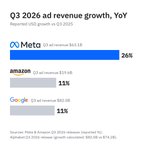
S&P: $META Meta's Ability to Monetize Its AI Investments Is More Limited Than That of Its Peers
Tõnis retweeted
$75B+ in annualized ad revenue now runs through Meta's Advantage+.
But what exactly is Advantage+ and why it matters?
What Advantage+ is?
Advantage+ is part of Meta's suite of AI powered advertising tools that automate many of the decisions which businesses traditionally had to make themselves.
How does it work?
Imagine that you are clothing brand trying to sell new shoes.
You previously had to make bunch of manual decisions:
> Who to target? (age, interests, demographics)
> Where to advertise? (Instagram feed, Reels, Facebook)
> How to distribute your advertising budget?
With Advatage+, much of this can now be done automatically.
Human advertisers make decisions based on who they think their customers are.
But AI can identify patterns in user behavior that humans might never think to look for.
As Meta's AI models improve, so does their ability to find the right customers for advertisers.
Meta's AI helps to optimize:
1. Audience: Finds people likely to buy, even if they fall outside the advertiser's suggested audience.
2. Placements: Determines where ads are most likely to perform well across their ecosystem of apps.
3. Budget: Dynamically distributes spending across ad sets based on expected performance.
4. Creative: Uses AI tools to generate and optimize different versions of ads.
Advertisers still control their objectives, budgets, brand assets and certain restrictions.
Does it actually work?
During their Q2 earnings call, Meta highlighted an Indian apparel brand that switched from manually configed campaigns to Advantage+.
The company reported 13% incremental lift in purchases and 16% increase in add to cart conversions.
Why does it matter?
Advertising is becoming increasingly automated.
Small businesses no longer need same level of expertise to manage every aspect of their campaigns.
For Meta, this could mean more businesses advertising on its platforms and existing ones spending more as their results improve.
Meta isn't only improving the ads people see, but also making the process of buying advertising easier.
$META

$META shared new details on Andromeda, its new ads retrieval system
What is Andromeda?
Andromeda is responsible for the first stage of Meta's ad recommendation process.
It narrows down massive pool of eligible ads into smaller group of more relevant ads, which are then evalued by other models.
What's new?
They redesigned Andromeda to make it way more efficient. Compared to 2024, new improvements are:
- 300x less computing work needed to evaluate ads
- 100x more ads processed per second
The new system can now evaluate over 1 billion ads per second on a single GPU server.
Interesting improvement is also introduction of 'Mixture of experts' architecture.
Instead of relying on a single model to understand user interests, Andromeda uses multiple specialized models that can better capture different interests and behaviors.
Meta also worked with $NVDA to optimize how Andromeda runs on its GPUs.
Why does it matter for Meta?
As AI makes it easier for advertisers to generate new ads, the number of ads Meta needs to evaluate is also growing.
Andromeda allows Meta to evaluate more candidates, imrpove ad matching and use its computing resources more efficiently.
Meta reported that Andromeda has contibuted to 2.4% increase in Facebook conversions since 2025.
Great to see that they aren't simply throwing more compute at their ad models, but always optimizing what they have.

source: engineering.fb.com/2026/10/2…

Tõnis retweeted
$META shared new details on Andromeda, its new ads retrieval system
What is Andromeda?
Andromeda is responsible for the first stage of Meta's ad recommendation process.
It narrows down massive pool of eligible ads into smaller group of more relevant ads, which are then evalued by other models.
What's new?
They redesigned Andromeda to make it way more efficient. Compared to 2024, new improvements are:
- 300x less computing work needed to evaluate ads
- 100x more ads processed per second
The new system can now evaluate over 1 billion ads per second on a single GPU server.
Interesting improvement is also introduction of 'Mixture of experts' architecture.
Instead of relying on a single model to understand user interests, Andromeda uses multiple specialized models that can better capture different interests and behaviors.
Meta also worked with $NVDA to optimize how Andromeda runs on its GPUs.
Why does it matter for Meta?
As AI makes it easier for advertisers to generate new ads, the number of ads Meta needs to evaluate is also growing.
Andromeda allows Meta to evaluate more candidates, imrpove ad matching and use its computing resources more efficiently.
Meta reported that Andromeda has contibuted to 2.4% increase in Facebook conversions since 2025.
Great to see that they aren't simply throwing more compute at their ad models, but always optimizing what they have.
Tõnis retweeted
$GOOGL Q3 earnings:
- EPS miss due losses in equity (spaceX)
- Slight miss of revenue $127.6B, 25% YoY
- Google Cloud platform growth 103% YoY🤯with 36.2% operating margins.
- TPU system sales were meaningful contributor to Cloud growth, nearly 100 customers already use TPUs.
- 3rd party compute came online at the end of Q3 and they will increase reliance on external capacity.
- GCP backlog of 561B and expected to realize 55% of the revenue in next 24 months
- Customers who use gemini enterprise more than quadrupled their spend YoY
- Search revenue grew 12% YoY and management said that query growth was highest in 5 years.
- AI mode still less monetized than traditional search and contributed to the slowdown in revenue growth, alongside FX effects.
I think there is still ways to go for search growth here.
- Gemini has now 1B monthly users, Google's first-party model APIs process nearly 32B tokens per minute.
- Introduced Gemini 4 carbon, strongest frontier model atm.
- Talked about golden age of productivity, where they can scale gemini 4 carbon models internally, and to customers. We have to find out how good these models actually are outside benchmarks.
- Google spent $51.4B on capex in Q3, compared to $42.3B in operating cash flow, which means negative cash flow of $9.1B
- They mentioned in the call how capex will increase significantly in 2027 but remain confident that these investments will generate good returns.
- Youtube advertising revenue gre 9% YoY to $11.2B, with living room viewing now accounting for 1/3rd of ad revenue.
- Youtube premium also is now at 150m subscribers globally, including trials.
Tõnis retweeted
Google reports their Q3 finanicial results today. Here is a pre-earnings warmup for you:
- Revenue is expected to come in at ~$128B, 25% YoY. EPS of around $3,02.
- Q2 free cash flow was negative and this quarter will also be negative. How many negative cash flow quarters will we have?
- Capex is estimated to be around $55,4B. Watch for capex raise during the call. Sundar himself mentioned that they are capacity strained.
- All eyes will still be on GCP growth, margins and backlog. GCP revenue could come in at wild 100% growth, OP margins at 38% and RPO at $520B+
- Search and other growing at 15% but worth listening for commentary on agents and what does that means for search going forward.
- Youtube watch time keeps going up and up. Youtube ads revenue could surprise people.
- Subscriptions, prices have been going up lately but are they growing in general?
- Could hear commentary on 2027 TPU business and how well that is doing.
- Gemini 4 Argon processed nearly 25 trillion tokens in its first 72 hours, around 3x Gemini 3.0s launch. Watch for more Gemini 4 commentary
- According to Similarweb, Gemini's share of website traffic has grown from 13,6% to 25% over the past year, although it's down slightly from 26.7% in April.
- Implied move after the earnings is around 6% or ±19.07 per share
- From technical perspective, Google has been under pressure lately as it has fallen roughly 10% from its October highs. Daily RSI is approaching oversold territory at 34. Watch for $316 area for support and $325-330 for resistance
$GOOG $GOOGL


Tõnis retweeted
I think commerce could become nice opportunity for Meta.
TikTok shop generated estimated $50B in GMV during H1 2026, growing 92% YoY
Now imagine something like that inside of Instagram and Facebook reels.
If all the Facebook mums and doomscrollers could buy stuff they discover in Reels without ever leaving the app.
Meta already has infrastructure in place for that like, Meta pay for payments, reels for discovery.
Only thing missing is to complete buys directly inside IG or Facebook.
Keeping transactions inside its apps, Meta could gain better purchasing data, improve their ads and collect commission on sales.
TikTok shop shows that the model can already work in scale.
Thoughts on MetaShop?
$META
Tõnis retweeted
Thought I'd share some thoughts after the new company Sundays, so here goes nothing:
- Zeta is AI powered marketing company. Perfect because my portfolio is already filled with ad tech companies.
- Founder-led by David Steinberg, who has around 30 years of experience building companies.
- Management made decision years ago to rebuild its platform around AI and intentionally pushing profitability to near 0.
- 20 quarters of beat and raise.
- Platform is delivering 6x return on ad spend. Expecting to push this to 10x with Athena OS.
- They have surprising data moat, as they have proprietary data platform, which is almost as big as Meta, Google and Amazon.
- They are working semiconductor partner to develop AI inference chips, wtf?
Overall it's quite technical company, but I'm quite interested in learning more. Specially with Steinberg in charge.
$ZETA

Happy Sunday! Looking little bit into $ZETA today. What are you up to today?
Also any Zeta enjoyers out here?


Thought I'd share some thoughts after the new company Sundays, so here goes nothing:
- Zeta is AI powered marketing company. Perfect because my portfolio is already filled with ad tech companies.
- Founder-led by David Steinberg, who has around 30 years of experience building companies.
- Management made decision years ago to rebuild its platform around AI and intentionally pushing profitability to near 0.
- 20 quarters of beat and raise.
- Platform is delivering 6x return on ad spend. Expecting to push this to 10x with Athena OS.
- They have surprising data moat, as they have proprietary data platform, which is almost as big as Meta, Google and Amazon.
- They are working semiconductor partner to develop AI inference chips, wtf?
Overall it's quite technical company, but I'm quite interested in learning more. Specially with Steinberg in charge.
$ZETA
Happy Sunday! Looking little bit into $ZETA today. What are you up to today?
Also any Zeta enjoyers out here?
One thing I found interesting from Nvidia GTC Berlin keynote was improvements in Vera Rubin.
Jensen mentioned that grace blackwells were 80% liquid cooled, while vera rubins are now 100% liquid cooled.
Now think about Coreweave signing contracts for A100s through 2029. Thats nearly 9 years after the GPUs were introduced.
Makes me wonder how long Vera Rubins and future generations could be economically useful
Maybe known information but I just heard that and thought it’s pretty interesting.
$NVDA $CRWV
