
Small and microcaps. No Buffet quotes. Only tweet when I have something to say. None of my tweets are investment advice
Joined January 2024
- Tweets615
- Following170
- Followers10.3K
- Likes8.2K






Might be a good time for a stock pitch. $TIC is down 11% today despite reporting phenomenal results, raising guidance, organic growth accelerating to 8.4% yoy and backlog growing.
But first a little story.
Six years ago, in the height of COVID, I heard of company called Api Group ($APG), a global provider of safet and specialy services that had been taken public through a SPAC. I found out the majority shareholder was a man called Martin E. Franklin, a pretty smart fella and capital allocator that had multibagged firms like Benson Eyecare or Jarden Corporation in the 1990s.
Api's playbook was simple: organic growth + bolt-ons + trying to increase the % of recurring revenue and lift margins. After buying shares in Oct 2020 and making a nice 30% in a few months, I sold. 6 years later, Api's revenue has 2.5x, EBITDA has 3.3x, the EV/EBITDA multiple has doubled from 8x to 16x, and the share price has returned 300%.
Today, I think $TIC presents many similar characteristics. An under the radar biz with exposure to growing trends like the aging electrical grid, O&G, DCs, aerospace and digital twins. Same playbook: organic + bolt-ons + operational discipline. I bought $TIC at $13 when I first read it from @citrini. The stock has gone nowhere since, but it's one of the few shares where I have been averaging down. It trades at 10x EBITDA.
Last 2 Qs the thesis that management laid out 1y ago is tracking: organic growth is accelerating (+8.4% Q3 26), cross selling between TIC and NV5 is starting to show up, and accretive bolt-ons are happening. The backlog ex-I&M is up 23% in Q3, and even the legacy core business I&M (Inspection and Mitigation) has accelerated this quarter, and management looked confident the operational changes they have implemented can keep the segment in the LSD-MSD growth range.
Oooh Mr Franklin, you'll fool me once but not twice. This time I'm down for the long ride.
Not rocket science. Dems restricting DC construction benefits those players with the largest cloud installed base in the world, not those gambling on GPU pricing. That's what's happening. Existing compute installed base becomes even more valuable.
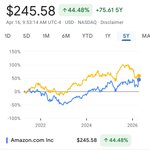
+ an externally imposed capex slowdown can make $AMZN FCF climb again.
I still think this this is a short-lived rally. Curtailing reinvestment opportunities is negative long-term, although it might save us from bubble.


An undeniable truth of stocks is that valuation vs growth is the only thing that matters. Valuation is your friend or it can be your worst enemy.
Even if I try to guide every investment decision by this principle, there’s been times when I overlooked this in favor of a good story. $LPTH and $LASR at 10-12x sales back in June is the perfect example. Both sizable positions, growing and with a very bright future, but both had a very demanding valuation. I did some trims but should’ve trimmed much more. Now they’re down 50%, still own them.
I also sold many when I had to because I didn’t let a good story blur my judgment. Sold most $OSS at $15-20 because valuation was nuts, now it’s $6. Sold $OKTA at $200 when valuation passed >10x sales after buying at $90. Similar with $FEIM, $FTG.TO, Jentech and plenty of other stocks. I tend to take profits gradually.
$EOS.AX is still my largest position and at a gain, but I’ll trim some because it doesn’t feel responsible to have 14% in a stock in this environment.
For now I’ve managed to say positive YTD, which feels a success in this market. I’ve been raising cash and I think it’s time to protect the capital gained during 2025 and H1 2026. Be patient and even more valuation grounded. If things change, change.
I am not too excited about $EOS.AX Kuwait A$700m contract. MARSS gross margins are already below EOS’s 50% gross margin + both the sensors and the hard-kill effectors are from 3rd parties.
You can’t assign the same revenue multiple to this contract than to a RWS/HEL proprietary sale. EOS is attractive bc of its vertical integration, I don’t want it to become a low-margin defense prime. This is a marginally profitable contract with an initial working capital drag, and its only value is it might open new opportunities with Gulf states where EOS can be the one actually supplying the RWS/HEL.
So you’re telling me $SPCX needs to deploy billions in capital just to catch up with 3 incumbents to enter a 120% penetrated and undifferentiated market and this is supposed to get me excited?


Stay away from people like this like the plague. Because what could go wrong at 25x sales? @peter_mantas the only real person I know that has been calling out $TWST since it was an undiscovered gem.

AI Drug Discovery Is Becoming a Bottleneck Trade
I get excited when an industry starts going through a real regime change. AI drug discovery (“AIDD”) increasingly looks like one of those moments.
Two things are happening:
1/ Upstream: the frontier AI labs are piling in.
2/ Downstream: The supply chain is clearly moving.
Supply-chain checks suggest the upstream picks-and-shovels of discovery and early preclinical R&D are starting to feel the increase in experimental volume.
DNA → protein → assays → sequencing → automation → preclinical testing
Names across that stack include $TWST , @GenScript , $ILMN , $TXG , lab-automation vendors and CROs.
$TWST expects triple-digit percentage growth in AI-enabled drug-discovery orders in FY26, and another year of triple-digit order growth in FY27.
@GenScript's AIDD business doubled YoY in 1H26. Its current platform advertises industrial-scale validation of 4,000+ designs/day, with integrated sequence-to-data workflows. Our channel checks suggest the ramp is moving even faster: roughly 8,000 designs/day currently, with a path toward ~16,000/day by YE26.
---
Why does AI drive more wet-lab demand?
1/ AI makes hypothesis generation almost free → way more shots on goal.
The bottleneck is moving from expert-driven design to biological validation.
2/ AI models need continuous experimental feedback — and both good and bad data are useful.
Traditionally, only the highest-conviction A+ candidates might get pushed into expensive validation. With AI, even the B/C candidates can be valuable because failed experiments generate training data.
@GenScript has said its sequence-to-binding workflow can return data in 4–7 days, and that faster cycle times matter because AI models depend on continuous experimental feedback.
@Anthropic is a clean example. @claudeai designed 1,320 protein binders. @adaptyvbio converted those digital sequences into DNA, expressed the proteins and tested binding. Only 354 actually bound. And the 966 failures are not wasted. They are useful negative labels: what does not express, what does not bind, what has poor affinity. Those results help train the next model iteration.
3/ Wet labs are no longer just making drugs. They are making training data.
$TWST / @GenScript increasingly look like biological data foundries.
$TWST explicitly talks about generating model-ready data from AI-designed sequences. In some workflows, the customer may care less about receiving the physical protein than about getting structured experimental results back into the model.
Traditional drug discovery asks: “Does candidate X work?”
AI drug discovery also asks: “What can this experiment teach the model?”
---
TAM of AIDD
If AI is simply a better R&D tool, the relevant spending pool is the $300–400B of annual global pharma R&D. If AI meaningfully increases the number of viable drug programs, the opportunity is larger because it expands downstream demand for DNA synthesis, protein production, assays, and preclinical work.
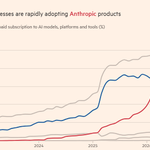
Near term, we can also size demand from AI-company spending. If Anthropic reaches $80B of ARR in 2026 and spends just 1% on AIDD, that alone would imply ~$800M of annual investment.
---
Trade setup
This is a trade that could have long legs. It’s hard to really stop working until PhaseI/II results (2028+)
It smells a lot like the bottleneck trade we just saw in semis: GPUs → HBM → networking → power/cooling. In biology, It basically follows the drug discovery process downstream: AI models → designs → DNA/protein → assays → preclinical capacity.
After the upstream picks-and-shovels, animal testing could become the next bottleneck. Monkey prices are already near prior highs and CRO capacity is tight. AIDD pushing more candidates into preclinical development would only add demand.
?? But clinical trials are still the bottleneck?
This is the biggest pushback I keep coming back to. No matter how fast discovery becomes, drugs still need to go through preclinical → Phase I → Phase II → Phase III → approval. You still need patients, time and capital.
But that doesn’t mean the bottleneck trade won’t work. More viable candidates — especially with higher success rates — still means more demand throughout the development process.
And who knows: clinical trials themselves may eventually be optimized by AI.
?? What breaks the trade?
Near term, the picks-and-shovels trade breaks if experimental budgets stop growing, AI-generated designs don’t translate into useful wet-lab hits, or capacity catches up too quickly.
Longer term, the thesis breaks if AI drugs look great in discovery / Phase I but fail at normal rates in Phase II/III. That is why Phase II matters so much.
?? Milestones
Late 2026–2027: first Isomorphic-designed drugs enter human trials; more AI-native programs move into IND-enabling work / tox.
2028–2030: clinical trial results start telling us whether AI-designed drugs actually perform better than conventional drugs.
Calling all the "bottleneck bros". :) @jukan05 @zephyr_z9 @aleabitoreddit @ParadisLabs
+++
More comprehensive analysis: robonomics.substack.com/p/ai…


Look folks, anyone that is able to maintain a minimum of human attention is going to thrive in the next few years. Using AI doesn’t mean being consumed by it. I find myself reading the Wikipedia more and more lately.
You’d be surprised at how much better your understanding of any topic can be by reading the Wikipedia rather than obsessively asking ChatGPT until you find the very specific answer that you want. There are benefits on unstructured learning as it makes you scratch your head and forces you to have a thinking process.

I am done with this shit. It is over. The state of engineering right now is horrible. It has been half a month since I started a new role at a big company. Nobody knows anything here. The specs, code, tests, PRDs, tickets, resolution of those tickets, reports, etc., everything is made by Claude Code. Nobody on my team likes this. They are being forced to ship as much as they can. I have heard multiple times from higher management that pushing code is not a bottleneck, so why are we slow? People are working 12 to 13 hours a day just to press enter. Nobody is reading anything. Humans in corporate are doing nothing on their own. Everyone, literally everyone, from an L1 to an L7 engineer here is doing the same thing. Talk to Claude. There is no sense of victory. Nobody is resolving bugs. In reality, nobody is thinking anymore. Everything is done by LLMs. It is so soul-sucking. I would not mind it, to be honest, if we were at least given the time to check out the code and see what is going where. But no, the goal is to just ship. No matter what happens.
If EOS Slinger has truly shot down 20.000 Russian drones in the last 2 months, I am still shocked this firm is still valued at a $1.6B market cap. Contrary to $LASR or $AVAV, $EOS.AX has the advantage of its deep RWS product portfolio in case laser adoption gets delayed. Plus a thriving command & control business for all sort of threat detection and a nascent interceptor business. So many paths to grow backlog. Still my largets position and I sometimes consider averaging up.

$eos.ax 60:20 to 64:40 cluster of slingers alleged 20k drones destroyed over a couple of months and created space to allow Ukraine movement
nitter.gq/i/spaces/1qJDzWLanQeKV
$OKTA has been a fantastic 2x in 3 months, with some call options that provided additional torque. But at 10x FY27 sales and a >50x PE the risk/reward is not that attractive anymore.
Even assuming 50% penetration of Okta’s 20,000-enterprise customer base from Agentic AI products in the next 2y with a 40% ACV uplift, it's still not cheap (that'd mean c. 13-15% annuales sales growth). In a bull case where ACV uplift reaches 50-60% instead of 40% and annual sales growth accelerates to 17-20%, also not cheap.
Agentic AI is an exponential force as AI invokes more AI without the need of any human interaction, and there is a chance I'm underestimating the duration of this growth. But for now, I've sold 2/3 of the initial position.

I started small teaser positions in $OKTA and $SAIL on the thesis that every enterprise agent will need identification, tracking and different levels of authorizations. I read Citrini's write-up a couple of months ago.
$OKTA is still 60% down from ATH, but it's climbing off the lows with +30% last month. Earnings are tonight. It might still be early - as their secure enterprise agent solution was only announced on March 16th - but I think worth a shot. They have huge enterprise penetration with 20k total customers and 5.1k large-enterprise customers.
$SAIL 7.6x fwd EV/sales but growing 25%+. Recent partnership with Antrophic.
$OKTA 5.3x growing HSD. Guidance is admittedly conservative so maybe more room for surprises.
Thinking every enterprise would vibe-code its own software and get rid of SaaS is like thinking every enterprise would run its own on-prem racks and never move to the cloud.
The Small Pond retweeted
I think $OKTA still has room to run. Stock is up 44% since management upgraded FY27 rev guidance from 9% to 9%-10%, but Street revenue and EPS estimates for the next 2 years haven’t moved an inch.
Okta’s average ACV jumps +40% when you upsell to include agentic AI security. If Okta upsells to 50% of its 20,000 enterprise customer base by CY28, revenue growth accelerates to 13-15% over a 3y-period. And that is holding the ACV bump at +40%. If you push the ACV uplift to 50-60% as new functionalities are introduced, you could be looking into 17-20% growth for that same 50% penetration, a 2x from the current 9-10% growth.
The chart looks decent, valuation reset to $115 from the June 1st $140 high, and now coming back to the $130's.

Europe would rather cut down its own tree whenever it grows too tall than risk it overshadowing the others—then wonder why the tallest trees in the forest are all American.
If the whole EU uses Google it's because Europe has never had the framework for such company to exist. The EU would rather destroy its own European Google just to avoid it having "significant market power".
Healthy competition is only enabled through free competition, and regulatory obsession does not enable free competition. The fittest survive. A (ironically European) man called Darwin laid the thesis out 150 years ago.
If you’re investing in $NFLX what’s the upside case?
More price increases? Ad-supported growth? Using AI to optimize the recommendation engine? Crack down on your own subscribers so they don’t share accounts and make them more unhappy?
Why do you think they stopped reporting MAUs 18 months ago? Content is absolute crap and engagement hours are flattish. HBO has less quantity but more quality, Prime Video has a much better film catalogue, even if not its own. Looks like a value trap. Way more chances of things getting worse than better unless they decide to invest in decent shows again.

The $LASR Q2 26 earnings call left a lot of important read-throughs on which I have taken action.
1 - $LPTH – the most obvious of all.
nLight’s China supply issues materialized only 2 weeks before the earnings call. nLight is a clear example that China is trying to slow-down the US defense industry by restricting rare-earth access. While most revenue impact was on the commercial side, management acknowledged there could be some defense/HEL spillover. We don’t know how long these headwinds will last or how quickly $LASR can adapt. I haven’t sold a single $LASR share, but I think yesterday’s decline is deserved.
Which brings me back to $LPTH. In this geopolitical context, what is the strategic value of a US firm that provides the only alternative to restricted rare earths?? Lightpath is also moving up the value chain into cameras, incorporating their proprietary glass into their cameras, and recently made a phenomenal acquisition that allows it to manufacture much larger optical products and sell into applications like satellites.
Cash-flows aside, the strategic national value of such a firm looks enormous to me. I’ve been consistently adding to $LPTH in the $10-$13 range over the last month.
2 - $ESP – US infantry wants to incorporate HELs into heavy ground vehicles. But integrating a multi-kW weapon on a mobile vehicle requires a lot of onboard power and this is not simple. When asked about this, $LASR management confirmed power is the key constraint for this implementation and not beam quality.
I came across $ESP a few months ago thanks to @BlackScholesMan. I owned a small position, then sold it, and I just bought back.
At a 15x fwd PE this looks a very asymmetric setup, and looks like a “if I’m wrong I don’t lose much, if I win I can win big” situation. $ESP offers direct revenue exposure to this opportunity + other catalysts like the General Dynamics contract Mike has discussed extensively.
3 - $VELO – An analyst said their internal surveys show strong demand for metal printing in aerospace and defense . $LASR management confirmed it. Simple: Velo is tripling its metal printing production capacity to meet strong defense and aerospace demand, and the stock is still down 55% from June highs. At these levels, worth taking a starter position.
This is NOT financial advice. Do your own due diligence.