

Ex-Equity PM & Quant. I built an AI engine to apply 10y+ institutional rigor to the open web. 🟢 Scanning for hidden gems. 💎 I invest my capital using this.
Tracking 1,000+ Authors
Joined December 2025
- Tweets1.1K
- Following498
- Followers633
- Likes912




Pinned Tweet
📊 H1 2026 is in the books - our first real out-of-sample stretch.
The setup: we built Trade Ideas Flow in late 2025, then froze everything - definitions, methods, hyperparameters, prompts. No tuning. No hindsight. Just the system running daily.
The result:
🟢 TIF: +18%
⚪ S&P 500: +9%
💎 +9% alpha in 6 months
Every pick was published to the web + emailed to subscribers in real time. The audit trail speaks for itself.
Not advice. Just how we run the process. Past performance ≠ future results.
Link below if you want to see how it keeps performing and want to get our picks (FREE for now)

4
7
1,469
Short pitch today, 3 pages, from someone who has bought the same stock about 65 times.
$ABXX.NE pitched by Russell Dodds
Abaxx runs a commodities exchange in Singapore. It is listed in Canada and trades as ABXXF in the US. Russell started buying in June 2023, about 65 purchases since, average cost $10.21 a share, and was still adding a few at $8.88 on November 16.
Why it got so cheap. A short report last May said Abaxx was basically paying traders to use its exchange, through liquidity credits. Company answered with an independent audit, which found no irregularities. Russell's read is that every exchange pays to get a new market going, and Abaxx pays more than competitors for now because its contracts have never traded on an exchange before.
And they really are new. Physically deliverable lithium, which gives the world a way to set a true benchmark price for lithium. Also LNG, nickel sulphate, wind and solar generation, Singapore gold and silver sold in offshore Chinese renminbi too, and carbon credits. Russell says no other exchange has these.
THE NUMBERS, IN US DOLLARS LIKE THE WRITE-UP
→ $8.88 on November 16 was a $362M market cap
→ 52-week high $52.20 in mid May. Before the short report it was valued at about $2B, around 1/50th of CME or ICE
→ Q3 loss about $14M, cash about $47M
→ Contract count grew again in Q3 and kept growing into the start of Q4
→ CEO Joshua Crumb bought $47,000 of stock on November 13
→ ABXXF is around $6.60 today, about 26% under the note's $8.88
What gets it back to $52? Russell's guess is a few more quarters of growth at this rate and the turn to positive cash flow. Path to profitability is promised with Q4 results.
"There are only about 10 commodity exchanges in the world. Abaxx will probably be the last one to be created this century."

Russell Dodds' Q3 note on Abaxx, with links to the company's results and the webcast: 📖
russell2024.substack.com/p/a…
I read every pitch like this at tradeideasflow.ai 💎🟢
6
391
Biotech pitch today where the main drug already passed 2 Phase 3 trials, only they were run in China.
$NVCT pitched by Truffle Pigs
Nuvectis licensed NXP100 from Haisco, a Chinese drugmaker. It is a once-daily pill for PNH, a rare blood disease, and China approved it in July. In the trial on patients new to treatment about 60% hit the main hemoglobin goal, against 8% on Soliris, the older standard drug.
Now the FDA has to say how much of that Nuvectis must repeat in the US. Truffle Pigs expect the answer in the coming weeks.
The part I liked is how they tested whether Chinese data can carry over. Novartis already sells a very similar pill in the US, Fabhalta. Its own PNH trials recruited 94% of patients outside the US, about 38% of treated patients were of Asian descent, and its FDA label found no clinically significant effect of race on how the body handles the drug.
THE FDA PATHS, WITH THEIR ODDS
→ Repeat both Phase 3 trials, 50%. NXP100 worth $2B in their model, filing mid-2029
→ Switch about 35 US patients over from an older drug, 30%. $2.4B, filing 1 year sooner
→ Only a small study of drug levels in the blood, 20%. Nearly $3B, filing possibly Q3 2027
Their base case already takes the slow path, and they write that even confirming that one should move the stock, because $2B for one drug sits far above a company priced at about $700M.
Second drug, NXP200, is a BRAF pill that gets into the brain. BRAF is a mutation behind some cancers. In 27 glioma patients, a brain tumor, 40.7% responded and 4 had complete responses. 3 of them had already been on other BRAF drugs, and 2 of those 3 saw tumors shrink more than 80%, responses lasting over 14 and 17 months.
THE NUMBERS
→ Near $20 a share in the write-up, about $700M market cap, $560M enterprise value. Around $19.40 today
→ Base case $2.5B, about $73 a share, after discounting each drug for the chance it fails. Slow FDA path and glioma only
→ Their upside scenarios reach $5.2B to $5.4B
→ Soleus Capital, Tang Capital and Braidwell each hold over 1.5M shares
→ 2.54M shares short, about 35% of the 7.3M shares Truffle Pigs estimate actually trade
They own the stock. In their words, the FDA answer and first data from a new salt version of NXP200, which gets more drug into the body, could "begin narrowing the significant discount to our estimated intrinsic value".
They have been on Nuvectis since January 2025. First piece was called "Nuvectis Pharma's Truffle Pig Moment".

1
194
Full write-up from Truffle Pigs, with the FDA path odds and every valuation table: 📖
trufflepigs.substack.com/p/n…
I read every pitch like this at tradeideasflow.ai 💎🟢
37
One of today's writers put a number on a closeout retailer's moat, 10.77% return on capital against a 6.53% cost of capital. The other picked an industrial in July while 95% of the sector sat closer to its highs than its lows.
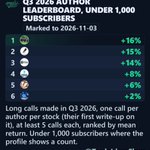
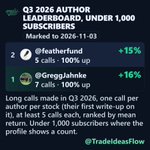
🥁 Final day of the Q3 2026 AUTHOR LEADERBOARD, UNDER 1,000 SUBSCRIBERS. Writers ranked by the average return of their Q3 calls, one call per stock. 4 are out. Today: 2 and 1, then every source in one place.

1
90
#1 is the only record on this board where the typical call beat the average, median +17.7% against a mean of +16.3%. Following every Gregg call in Q3 made money 7 times out of 7.
That is the whole board, 6 writers. Sources for all 6 in the next post.
1
44
Go support these authors, they did the work. The whole Q3 2026 AUTHOR LEADERBOARD, UNDER 1,000 SUBSCRIBERS, in rank order.
Every author in our database, pitched on or after Jul 1, 2026 and before Sep 30, long calls only, market cap above $50M, share price above $0.50, one call per author per stock, their first write-up on it, later write-ups not counted, at least 5 qualifying calls, ranked by mean return. Under 1,000 subscribers where the profile shows a count, and every record checked against the author's own archive. Marked to Nov 3.
#1 @GreggJahnke
jahnke.substack.com
#2 @featherfund
featherfund.substack.com
#3 The Stock Stories
thestockstories.substack.com
#4 @Spread_Hunters
spreadhunters.substack.com
#5 @abroninvestor
andrewbrown174150.substack.c…
#6 @CompoundingLab
compoundinglab.substack.com
We read 1,000+ authors and send the best pitches out every morning:
tradeideasflow.ai 💎🟢

67
💎 MY FAVORITE STOCK PITCH FROM THE LAST 24H
$GG8.AX pitched by 8020Invest
Gorilla Gold has 1.5Moz of gold across Comet Vale, Mulwarrie and Vivien in WA. As far as the author can tell, no plant to put any of it through.
Now it is buying one. Cosmos, from IGO, about 30km north of Leinster: a 1.1Mtpa plant refurbished in 2023, with camp, aerodrome, tailings dams, power and water. Management says all of it would cost more than A$300m to build today, and the write-up flags that this is their own estimate.
Paid in shares, so IGO ends up with 19.9% and becomes the biggest shareholder. Alongside that, about $60m raised at 26.5c, the last close before the halt, no discount. Tembo Capital put in $30m. Simon Lawson, a geologist at Cosmos from 2006 to 2010, puts in $1m of his own and becomes Executive Chairman. Bellevue Gold is right next door with 2.7Moz at 8.6g/t.
THE CATCH
There is no gold resource at Cosmos yet. Old pits, old drill hits and a plant. The plant was built for nickel too, so it needs a gold circuit, and there is no cost for that yet. $25m is set aside to drill it out.
8020Invest got a loupe in the goodie bag at Gorilla's Diggers breakfast and "still can't read a rock", so this is an accountant reading the announcements instead. The things "I had to read twice":
→ IGO's 65m performance rights vest on a Cosmos resource of 0.5Moz and then 1.0Moz, or if the 20-day average price gets above 60c. So they can vest on share price alone
→ The raise does not depend on the deal. $48.4m of new shares start trading on 26 November, the vote is in early January
→ Shares go from 732.7m to about 1,197.3m, 63% more, and no share purchase plan for small holders
→ Cash went from $19.7m to $9.5m in the September quarter. At that pace $69.5m lasts under 7 quarters, before any Cosmos drilling
Written at 39c, already up 47% on the placement, about $467m for the whole company after the deal. Closed A$0.38 today. A 10-bagger means nearly twice the size of Spartan, which sold for $2.4b, "which is a lot to ask".
Holds the shares and says so in the first line. "Simon's own top hurdle is $1.05, about 2.7 times from here. I'd be very happy with that."

1
1
209
Full write-up, with the deal terms read clause by clause and the cash runway worked out by an accountant: 📖
8020invest.substack.com/p/go…
I read every pitch like this at tradeideasflow.ai 💎🟢
49
💎 THE GRID BUILDOUT, PITCHED FROM THE LABOUR SIDE
$PWR pitched by @Delta9Echo of Rock & Turner
The grid needs to grow for AI and for everything else plugged into it. A utility can get the line approved and financed and the transformers on order, "but somebody still has to build it". There are not enough lineworkers and electricians to do that.
Quanta Services is the largest specialty infrastructure contractor in North America, about 96,000 people and over $40B of revenue a year. It spends about $250M a year training its own people, with its own lineman college. A journeyman lineworker takes roughly 4 years to train, so a competitor with money cannot just go and hire the capacity.
The CEO line the pitch is built around: "you cannot buy craft, you have to build it."
THE NUMBERS
→ Added 26,000 workers in 2026, 33% more than at the end of 2025, about 12,000 of them recruited directly
→ Does over 80% of its work with its own crews, so the margin does not leak to subcontractors
→ Data centres: about $3-4M of revenue per megawatt a year ago, $5-7M now by doing the mechanical, electrical and plumbing work inside the building, and management is aiming for $7-10M
→ Q3 revenue $12.01B, up 57%, with $1.45B of operating cash flow and $1.20B of free cash flow, both quarterly records
→ NiSource was a customer spending under $100M a year. Now it is a 3GW gas plant program, a 50/50 venture with Zachry, worth $5-7B of backlog through 2032
THE PART I LIKED
Backlog is a record near $64B, and the write-up went into what it is made of. About $22B of it is estimated renewals of service agreements and short-term work with no fixed price, and most contracts can be ended on short notice. The firm orders are about $42B. And the big 765kV transmission lines in Texas, Ohio and the Midwest are mostly not in backlog yet.
Stock pulled back after the mid-term elections on worries about federal clean energy incentives. Closed $602.60 yesterday, and the author owns it. "The market is still valuing it on trailing multiples and incomplete guidance, yet taking a forward looking view, the risk/reward set-up appears compelling."

Nvidia smashes expectations, but the markets closed down on the day and the VIX spiked
Report:
rockandturner.substack.com/p…
$NVDA $HD $CRM $INTU $NOW $WDAY $SBAC $CCI $UNH $NKE $FICO $FSLR $MKC $GPN $FIX $COHR $CIEN $LITE $AVGO $CHRW $ILMN $MRVL $SYK $GEV $GLW $PWR $CTVA $SKYD $DUK

131
463 stock pitches went out in the week to 10 November. 3 made this issue.
📈 Thursday Tailwinds #15 is out. A battery salt, a radiation badge and a camera that sees silent drones.
A tailwind is a force that keeps pushing money toward the same companies for as long as it runs. Owning one is more forgiving than owning a good company, since you can be roughly right about which business catches it and still do well.
This week somebody other than the paying customer sets each force. A US tax credit decides who sells battery salt to Korean cell makers, a regulator decides that every reactor buys a dosimeter, and an enemy drone decides that a soldier keeps the radio off.

1
159
4 more I liked and could not fit, all credited inside the issue.
🔹 India's 40% local-content rule for subsidised battery projects lands on the box around the cell, worth about USD 0.75 billion to local makers of racks, cooling and fire safety in the 30 GWh tranche alone, on illustrative arithmetic. Anatrop Capital
🔹 Meta's average price per ad rose 14% in the third quarter on 10% more impressions, the first time since 3Q25 that price beat volume. Korea Invest Insights
🔹 Software is moving from charging per user to charging per action an AI agent takes, with Salesforce's rate card at 10 cents an action. DC Capital
🔹 Germany's labour force shrinks 6.9% by 2036, from 55.0 million to 51.2 million people, and the IFR expects robot installations to grow 7% a year to about 806,000 in 2029. Sören, in German
7 writers did this work and I only picked between them, so follow them before me.
Link in the comments.
1
70
Inside: why India's evening power sold for 25 times the noon price, and the Indian chemists selling the salt inside its batteries abroad first.
tradeideasflow.substack.com/…
41
In June, shareholders of a concrete-machine maker voted down 4 resolutions at its AGM, and the directors owned 0.3% of the stock outright. One of today's writers read that revolt as the catalyst.
🏆 Day 2 of the Q3 2026 AUTHOR LEADERBOARD, UNDER 1,000 SUBSCRIBERS. Writers ranked by the average return of their Q3 calls, one call per stock. 6 and 5 went out yesterday:
#6 bought Wolters Kluwer in February and built the valuation model in August to check it
#5 runs a trust that only buys companies with a controlling shareholder
Today: 4 and 3.

There are 2 ways to top a quarter, and this board has both.
#3 got there on 1 call. Thinkific is up 71.7% and the other 4 calls average about -0.2%, so the median is +4.2% against a mean of +14.2%.
Tomorrow's #2 and #1 got there the other way. They made 12 calls between them and all 12 are up.
I rank by the average because that is what you would have made following every call. The median is what a typical call did, and next week I will post the same 6 ranked that way. 2 of them swap places.
1
39
Tomorrow: a closeout retailer holding 119.3 days of inventory, which its writer argues is the asset, and a model portfolio built 1 sector at a time that made 7 calls in 3 weeks of July.
That was 4 and 3. The top 2 tomorrow.
Today's sources, go support these authors:
#4 @Spread_Hunters
spreadhunters.substack.com
#3 The Stock Stories
thestockstories.substack.com
We read 1,000+ authors and send the best pitches out every morning:
tradeideasflow.ai 💎🟢
47