

A probabilistic gambler.
Joined January 2016
- Tweets8.5K
- Following1K
- Followers2.9K
- Likes39.2K




Pinned Tweet
“Quant” for non-IT people
Ane bangun sistem untuk normies ngelakuin quantmaxxing.
- Terhubung ke broker + live-trading
- Backtesting + Monte Carlo + uji statistik
- Trade crypto, US stocks, dan commodities
- Tanpa biaya bulanan seperti QuantConnect/LuxAlgo
- Lifetime


Abida Massi retweeted

The Art and Science of Trading will be published in four weeks time, on the 1st December. Have you ordered your copy yet?


Abida Massi retweeted

Read more books. Read to escape reality. Read to understand reality. Read to challenge what you believe. Read to think better. Read to write better. Read to argue better. Read to know yourself. Read to build something. A single book can completely rewire your brain.

Abida Massi retweeted

The trailing stop is effectively a trend-following component, but that’s precisely the point of @basso_tom experiment.
It doesn’t prove that entry signals have no value. It simply shows that a profitable systematic strategy doesn’t necessarily require a sophisticated entry signal, expecially in presence of autocorrelated assets.
Basso conducted his experiment back in 1991. Could you share the title of the later Winton study you’re referring to?

Ane publikasi strateginya di akun “pet project” ane btw. Ini akun mainan ane buat have fun (somehow banyak yang follow wkkwkw). Akunnya di TikTok dan IG @/donchiancapital.
Kalo mau belajar systematic trading comprehensively no-brainer cek aja donchiancapital.com/mastercl…

Abida Massi retweeted

Tech Stocks in Bear Market Territory:
1. AppLovin, $APP: -68%
2. Coinbase, $COIN: -62%
3. CoreWeave, $CRWV: -60%
4. Arm Holdings, $ARM: -55%
5. Western Digital, $WDC: -54%
6. Intel, $INTC: -54%
7. Oracle, $ORCL: -51%
8. SanDisk, $SNDK: -49%
9. Circle, $CRCL: -48%
10. ServiceNow, $NOW: -44%
11. Robinhood, $HOOD: -44%
12. Seagate, $STX: -42%
13. Marvell Technology, $MRVL: -39%
14. Super Micro Computer, $SMCI: -39%
15. Broadcom, $AVGO: -34%
16. Alphabet, $GOOGL: -31%
17. Adobe, $ADBE: -29%
18. Micron, $MU: -29%
19. IBM, $IBM: -23%
20. Meta, $META: -21%
21. Amazon, $AMZN: -21%
The Nasdaq 100 is now down nearly -$5 trillion since October 6th.
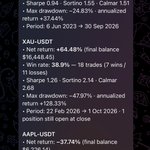
Ane running 15 routes di live-trading. Somehow, dalam 2 minggu terakhir, intensitas XAU-USDT relatif tinggi dibandingkan route lain.
Rupanya karena “longgar”. Dalam systematic trading, ini namanya under-filtered (bukan underfitting).

Abida Massi retweeted

Kenapa SBN makin susah narik asing?
Rumusnya begini:
Yield SBN wajar = yield UST + premi risiko gagal bayar Indo (CDS) + premi risiko rupiah melemah (FX risk)
Kalo yield SBN naik, tapi kenaikan CDS & ekspektasi pelemahan Rupiah (FX risk) ternyata lebih kenceng, expected return dalam USD buat asing malah turun.
Coba kita hitung2 kasar, per hari ini:
SUN 10Y sekitar 7.6%.
UST 10Y sekitar 5%, premi CDS Indo sekitar 1.03%.
Sisanya sekitar 1.6%, itu kompensasi untuk nutup risiko pelemahan rupiah.
Pertanyaannya, apakah 1.6% ini sepadan untuk nanggung risiko pelemahan rupiah?
Tahun 2019, waktu asing lagi rame2nya masuk SBN, angka ini ada di sekitar 4.6%, sekarang tinggal 1/3 nya.
Kalau market expect Rupiah akan melemah lebih dari 1.6% setahun ke depan, hitung2annya jadi ga masuk buat asing.


Apa yg lagi terjadi di Indonesia ini sebenernya ngeri2 sedap ya..
Bisa bayangin gak, Surat Utang RI (SBN) nyaris gak laku? Pemerintah mau gak mau nawarin yield (imbal hasil) yg tinggi, hari ini sampai naik dari 7,54% ke 7,7%
Asing pada jualan SBN (capital outflow) yang bikin yield kita meroket drastis. Habis jual SBN, mereka tukar Rupiahnya ke Dolar buat dibawa keluar, ini yang bikin Rupiah makin lemah dan bakal ngaruh ke semua aspek ekonomi kita
Di ekonomi riil, efeknya bank harus nawarin deposito lebih tinggi, tapi harga yg harus dibayar jadinya cicilan makin susah, perusahaan jadi harus lebih hemat buat produksi dan angka pengangguran bisa makin tinggi
Di saat yg bersamaan, capital market kita ini miris banget bjirr. CIO Danantara, Pandu Sjahrir bisa2nya jadi ‘pemain’ saham, di saat yg bersamaan jadi wasit ke MSCI juga. Nyang bener aje
Abida Massi retweeted

🇮🇩 JUST IN: Bloomberg reported that the Chief Investment Officer of Danantara Indonesia, Pandu Sjahrir, indirectly owns 27.5% stake in Supra Sekuritas (SS), which is recently sanctioned by OJK in relation to stock-market manipulation case.
Based on data from Stockbit, Supra Sekuritas top net buy this year in all market are $DSSA, $CUAN and $BUMI.


Abida Massi retweeted

So they pay you a $150K salary just to be a middleman between Claude and your boss?

Abida Massi retweeted
M&A 101: Takeover Defense Playbook
Belakangan isu "Hostile Takeover" lagi sering dibahas di market Indo, terutama setelah transaksi 30% saham Bayan bulan ini.
Saya jelaskan 9 jurus yang biasa dipakai perusahaan untuk bertahan dari hostile takeover di dunia M&A.
Semua jurus ini sebetulnya hanya turunan dari 6 logika dasar: bikin mahal, bikin lama, bikin ga menarik, cari teman, balik nyerang, atau bayar biar pergi.
1. BIKIN MAHAL
• Poison pill: kalau ada pihak tembus ambang kepemilikan tertentu, pemegang saham lain boleh beli saham baru dengan diskon. Porsi penyerang otomatis terdilusi.
Contoh: Twitter pasang ambang 15% sehari setelah Elon nawar USD 54.20/saham di April 2022.
Elon akhirnya harus lewat board, dan deal USD 44 miliar nya disetujui 25 April 2022.
• Golden parachute: Perusahaan menyiapkan klausul pesangon jumbo untuk direksi/manajemen kalau kendali perusahaan berpindah. Tujuannya supaya ongkos akuisisi makin mahal buat si penyerang.
2. BIKIN LAMA
• Staggered board: Direksi diganti bertahap, misal 1/3 per tahun. Penyerang jadi butuh lebih dari satu kali RUPS buat bisa menguasai board secara penuh.
Contoh: Airgas pakai jurus ini (plus poison pill) untuk bikin Air Products mundur di 2011.
3. BIKIN GA MENARIK
• Crown jewel: Jual aset paling berharga milik perusahaan ke pihak ketiga supaya perusahaan target jadi ga menarik lagi di mata penyerang.
Contoh: Tahun 1982, waktu diserang tender offer oleh Whittaker, Brunswick memilih untuk menjual anak usahanya, Sherwood Medical seharga USD 425 juta.
4. CARI TEMAN
• White knight: Cari pembeli/investor lain yang lebih "ramah" untuk menyelamatkan perusahaan.
Contoh: Revlon gandeng Forstmann Little di 1985 buat melawan Pantry Pride.
• White squire: Investor ramah masuk dan beli porsi minoritas, cukup buat ngeblok penyerang tanpa harus ambil kendali.
Contoh: Berkshire nyetor USD 700 juta ke Salomon di 1987 buat ngeblok manuver Ronald Perelman.
5. BALIK NYERANG
• Pac-Man: Target berbalik menawar dan mencoba mengakuisisi si penyerang.
Contoh: Tahun 1982, Martin Marietta ngutang sampai USD 1 miliar buat memborong saham Bendix yang saat itu justru lagi nyerang dia.
6. BAYAR BIAR PERGI
• Greenmail: Beli balik saham penyerang di harga premium supaya dia pergi.
Contoh kasus Tahun 1984 Disney beli balik 11.1% saham Saul Steinberg di USD 70/saham plus biaya.
• Selective self-tender: Perusahaan melakukan buyback saham dari semua pemegang saham, KECUALI dari si penyerang.
Contoh: Unocal nawar USD 72/saham ke semua pemegang sahamnya selain Mesa Petroleum di 1985.
Di market US, hostile takeover lebih mungkin terjadi karena kepemilikan saham publiknya menyebar (dispersed ownership).
Di IHSG, banyak emiten punya controlling shareholder dengan porsi besar.
Per 31 Mei 2026, 327 emiten (35.8%) free float-nya masih di bawah 15%.
Hostile takeover di market Indo jauh lebih susah dieksekusi, dan biasanya butuh modal besar buat berhadapan dengan pemegang saham pengendalinya.

- Iseng bikin pet project
- Upload di TikTok 0 followers jam 6
- Ga nyangka jam 10 udah closing satu 😂
Hasil belajar AI dari om @mrayhanfadil 😂

Abida Massi retweeted

There is an interesting market rumor circulating that Bank DBS Indonesia could be merged into $BBCA through an inbreng (non-cash capital contribution) transaction, with BCA remaining the surviving entity and the DBS shareholder receiving newly issued BBCA shares in exchange.
This is what I heard as one possible explanation for BBCA’s sharp rally today, reportedly reaching approximately 7% at the time of writing. To be absolutely clear, this is an unconfirmed market rumor, not an announced corporate action.
One important clarification on the ownership structure: DBS Bank Ltd. currently owns 99% of Bank DBS Indonesia, while BCA already owns the remaining 1%. Temasek is a major shareholder of DBS Group, so any share-for-share transaction would involve the relevant DBS entity rather than automatically converting a directly held Temasek stake into BBCA shares.
Now, does this transaction make economic sense?
Strategically, I can see the rationale. DBS Indonesia has an established corporate banking, treasury, wealth management and institutional client franchise, which could complement BCA’s exceptionally strong domestic deposit franchise, payments ecosystem and retail distribution network. Combining the two could create opportunities in corporate lending, transaction banking, cross-border financing, wealth management and fee-based income.
However, the financial contribution would be relatively modest. DBS Indonesia generated approximately Rp1.72 trillion in net profit in FY25, compared with BCA’s Rp45.2 trillion in the first nine months of 2026 alone. On a simple annualized basis, DBS Indonesia’s earnings would represent less than 3% of BCA’s existing profitability, before any synergies or adjustments.
Therefore, I struggle to see how this transaction alone would fundamentally transform BCA’s earnings trajectory or justify a substantial valuation re-rating.
The more important questions concern the transaction structure and exchange ratio. At what valuation would DBS Indonesia be contributed? How many new BBCA shares would be issued? Would the transaction be earnings-accretive after dilution? What would happen to BCA’s ROE, capital adequacy and cost-to-income ratio? And perhaps most importantly, why would DBS Group want to give up direct control of its Indonesian banking operations in exchange for a minority stake in BCA?
That last question is particularly interesting because DBS Indonesia remains profitable and DBS only recently strengthened its Indonesian financial conglomerate through its securities business.
Of course, an appropriately priced transaction could make sense for both parties, particularly if DBS values exposure to BCA’s franchise more highly than maintaining direct control of its Indonesian subsidiary.
But without knowing the proposed valuation, ownership structure, expected synergies and strategic intentions of both shareholders, I would not automatically interpret the rumor as bullish for BBCA.
A good acquisition is not simply about acquiring a profitable business. It is about acquiring that business at a price that creates value for existing shareholders.
For now, I would treat this as speculation until we see formal confirmation from BCA, DBS or the relevant regulators.
Interesting rumor, though. Let’s see whether there is any substance behind it.

