

financially independent and retire early | dividend investment BTC | AI | DCA
Joined May 2022
- Tweets615
- Following443
- Followers62
- Likes1.4K




The bond market is sending a warning that equity investors shouldn't ignore.
As of Nov. 20:
Oracle's 5-year CDS hit 327.9 bps, versus roughly 76 bps a year ago.
CoreWeave's 5-year CDS surged to 1,232.6 bps, implying a market-implied 5-year default probability above 65%.
These numbers tell us something important.
AI infrastructure requires enormous upfront capital. GPUs, data centers, power and cooling must be financed before compute capacity can reliably generate revenue.
If deployment takes longer and cash flows arrive later, companies must borrow more, pay higher financing costs and carry greater liquidity risk.
The danger is a potential chain reaction:
Higher CDS → Higher borrowing costs → Tighter liquidity → Delayed CapEx → Slower GPU demand.
This is especially concerning for highly leveraged AI infrastructure providers like CoreWeave.
Oracle's situation deserves attention too. Its scale and business diversification are very different, but its rising CDS suggests creditors are increasingly questioning the cost and timing of its AI investment cycle.
One important caveat: CDS-implied default probabilities are market-based estimates, not literal forecasts of bankruptcy.
AI demand can remain strong while the financing model becomes fragile.
The next phase of this trade will be determined by more than GPU demand. Cash flow, balance-sheet strength and the ability to finance infrastructure at scale will matter just as much.
24
Elon Musk is highlighting a risk the market may be underestimating.
AI infrastructure requires massive upfront spending. But paying for GPUs doesn't mean they can immediately generate revenue.
Power, cooling, networking, deployment and reliability all take time.
If compute takes months longer to become operational, hundreds of billions in capital could remain tied up before generating returns.
The key risk for 2027:
Higher working capital requirements
Longer cash conversion cycles
Rising financing needs
Potential CapEx delays if funding tightens
I'm watching GPU utilization, operating cash flow, customer prepayments and deployment timelines.
AI demand can remain strong while the companies building the infrastructure face serious liquidity pressure.
Demand is only one side of the equation. The ability to finance, deploy and monetize compute will determine who actually captures the returns.
15
VIX JUST HIT 40. THE MARKET IS UNDER SERIOUS STRESS.
The fear gauge surged 86% in one week, reaching its highest level since the April 2025 tariff turmoil.
Meanwhile:
• S&P 500: -3.7%
• Nasdaq 100: -5.6%
• Goldman Sachs Panic Index: 9/10
• CTA funds have sold ~$57B in equities over the past month.
The bigger concern is forced selling.
If the selloff continues, systematic strategies could amplify downside pressure.
But here's what I'm watching:
Does VIX stay above 30?
Do CTA outflows begin to stabilize?
Do AI earnings estimates hold up?
A VIX spike alone doesn't signal a bottom.
I want to see volatility decline, selling pressure fade, and earnings expectations stabilize before calling this a durable buying opportunity.
Fear creates opportunities. But confirmation matters.
30
AI CapEx IS NOT PEAKING. IT'S SCALING.
J.P. Morgan projects hyperscaler CapEx to rise from $800B in 2026 to nearly $2T by 2030.
Even as growth slows from 66% in 2027 to 22% in 2028, that's still another $292B flowing into the AI supply chain.
The bigger picture:
• $284B cumulative FCF burn through 2028.
• Operating margins expanding toward 35%.
• FCF reaching $624B by 2030.
This challenges the narrative that AI investment is destroying shareholder returns.
The hyperscalers are absorbing enormous upfront costs to build infrastructure that could generate substantial long-term cash flows.
The real question isn't whether AI CapEx is expensive. It's whether the returns on that investment justify the spending.
For now, the projected long-term economics suggest the market may be underestimating the scale of AI monetization.
$AMZN $GOOGL $META $MSFT $ORCL
9
Short sellers have found the AI trade's pressure point: vendor financing.
Hunterbrook Capital just hit AMD with a report alleging the chipmaker is increasingly financing or guaranteeing the customers who buy its AI chips — essentially lending buyers the money they use to purchase its products. On paper, it inflates revenue and makes demand look insatiable. In reality, it raises an uncomfortable question: how much of the AI demand boom is real, and how much is leverage wearing a costume?
The specific vulnerability is AMD's balance sheet. Its financing commitments are large, while its cash position is relatively thin. If AI capex cools and customers can't repay, AMD faces a double hit — bad debt plus a revenue cliff. The stock dropped as much as 11% intraday and dragged the whole semiconductor complex down with it.
This is the second time in weeks this playbook has appeared — Muddy Waters used a similar circular-revenue framework against NVIDIA. It's now a pattern, not an incident.
The distinction that matters: same accusation, different balance sheets. NVIDIA's customers are Microsoft and Google, which print their own money. AMD leans on second-tier cloud providers that need the financing. The report hits different P&Ls with very different force.
25
Anthropic just pulled off the biggest IPO in history, raising $81.3B at $83 a share, and the first day of trading told two stories at once.
The stock opened at $111.50, up 34%, as opening-cross euphoria briefly pushed the valuation past $2 trillion. Then it faded all afternoon and closed at $97.17 — still up 17.1% on the day, but 12.9% below the first print, with the entire 7.4% float turning over roughly once.
That shape is the classic signature of a deal where the order book was real but the opening price was crowded: $83 was a real demand price, $111.50 was an emotion price, and the close was the compromise between the two.
Meanwhile the rest of the AI trade bled, with AMD down 9% and the Dow off 1,100 points, as traders sold AI beta to make room for AI's new core asset. The real test comes in December, when $26B of unlocked strategic-placement shares meet forced buying from Nasdaq-100 index inclusion.
Day one proved the market still pays up for AI core assets — it just stopped paying for AI emotion.
24
Stan Druckenmiller just did something more informative than any forecast: he stepped aside.
"I can't recall a time when I had less conviction about where markets will be a year from now... Our goal is simply not to lose money."
What triggered the retreat:
→ The Fed stopped cutting (and the November minutes say hikes are coming)
→ Commodities weakening, credit spreads widening
→ His warning: watch H2 2027 for economic disappointment
His 13F tells the rest:
→ Portfolio cut from 95 positions to 65
→ ALL index call options gone — SPX, Russell 2000, equal-weight
→ Sold 94% of TSMC, halved STMicro
→ Nearly TRIPLED Seagate, added Western Digital — AI storage, not AI chips
→ New positions in Newmont, Barrick, Agnico Eagle — gold miners
→ And he's short copper — this year's hottest AI-linked commodity, now down 10%+ from its record high
The most interesting shift: he's moving from AI infrastructure builders to AI adopters, and questioning per-token pricing itself.
When the best macro trader alive says "I'm taking a break — maybe two days, maybe six months," that's not bearishness. It's information: the easy money in this cycle has been made.
Cash is a position too
22
The biggest macro repricing of 2026 is happening right now, and most portfolios aren't positioned for it.
The market spent two years waiting for rate cuts. The Fed just hiked in September — the first since 2023 — and the November minutes say the quiet part out loud:
→ Nearly ALL officials see further hikes as appropriate
→ Waller floated a 50bp move in December
→ Core PCE is running at 3.6% — and rising
→ The drivers: tariffs, the Iran war, and uncertainty around AI capex itself
Now follow the money. Every asset priced for low rates is being repriced simultaneously:
→ Long bonds: down as yields rise (duration is a trap here)
→ Gold: off 20%+ from its January high despite war and central bank buying
→ Growth stocks: the AI trade just lost 30% on its leader
→ Crypto: liquidity tailwind becomes a headwind
What benefits? Almost nothing glamorous: short-term Treasuries and cash. When the risk-free rate is rising, "boring" is the position.
The regime question for 2027 is simple: does inflation break before the Fed breaks the market?
Until that answer arrives, duration and leverage are expensive. Patience is cheap.
1
20
$NVDA 's Q3 was a blowout. But two numbers matter more than the headline beat.
The beats:
→ Revenue $115.8B vs $109.2B expected (+103% YoY)
→ Data Center $107.6B (+110%)
→ Q4 guidance $130B — assuming ZERO China data center revenue
→ Vera Rubin: fastest ramp in company history, $20B in sequential revenue already shipping, not a roadmap
1. China doesn't matter anymore. Shipments were $2.4B, just 2% of revenue — down from 20-25% of Data Center before export controls. NVIDIA is already ex-China. China is no longer downside risk; it's a free option.
2.valuation. The stock fell 30%+ before earnings, hitting 12x forward earnings — a 14-year low. That's multiple compression, not earnings decline. At 12x, the market is pricing an AI capex collapse next year, while the company just guided FY28 revenue growth of 70%.
The real cracks to watch: Q4 gross margin guide of 71-72%, $390B of supply commitments, and the unfinished CEO transition.
1
76
THE CHEAPEST STOCKS CAN SOMETIMES BE THE MOST DANGEROUS.
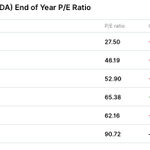
Look at current forward P/E multiples:
• $SNDK: 2.74x
• $SKHYNIX: 3.03x
• $MU: 3.37x
• $NVDA: 9.87x
These valuations look incredibly attractive. But there's a catch: semiconductor earnings are highly cyclical.
When earnings peak, forward P/E often looks deceptively cheap.
If memory prices roll over and AI demand slows, EPS estimates get cut. At the same time, investors may assign lower valuation multiples.
That's a Davis Double Kill:
Earnings decline.
Valuation multiples contract.
Both hit the stock price simultaneously.
A stock trading at 3x forward earnings isn't necessarily undervalued if those earnings are near cyclical highs.
Don't confuse peak-cycle earnings with sustainable earnings power.
In semiconductors, the real question isn't how cheap the P/E looks today. It's how much of today's earnings will still be there two years from now.
158
Why does gold keep refusing to break? Look at WHO is buying. Gold has four types of buyers, and they're not equal:
→ Central banks: the floor. 244 tonnes bought in Q1 alone. China's 19th straight month of buying, Poland at 632t toward a 700t target. Price-insensitive — they buy reserves, not charts. 84% of central banks plan to hold MORE gold in 5 years.
→ Insurers & institutions: the new entrants. China's top insurers got approval to allocate 1% of AUM to physical gold — 200 tonnes. And 1% is likely just the starting point.
→ ETFs: the swing vote. Western money, fast in and fast out. Outflows of 93t in May-June flipped to inflows of 70t in July-August. They don't set the floor, but they set the momentum.
→ Retail: the noise. Price-sensitive, fades at highs.
But hold on — if the floor is so strong, why is gold still down 20%+ from its January peak ($5,600)?
Because floors stop free-falls, not repricing. Three headwinds hit this year:
→ Profit-taking after a +64% run in 2025
→ Energy-driven inflation revived Fed hike fears — real yields rose, the dollar strengthened
→ ETF money (the swing vote) spent months flowing OUT
The key insight: structural buyers (central banks, insurers) set the floor. Cyclical forces (rates, dollar) set the price. This year, the cyclicals are winning the battle — but the structural floor explains why gold corrected 20% while AI stocks fell 30%+ and Bitcoin fell 35%.
Floors limit damage. They don't prevent drawdowns.
31
Muddy Waters is short $NVDA . Read the report carefully before you panic — it's not what the headline suggests.
What they allege: a former NVIDIA sales chief (Ajay Puri) may have undisclosed ties to an ex-SMCI executive (Cenly Chen), who a shareholder lawsuit claims managed GPU distribution during an alleged $2.5B chip-smuggling scheme to China.
What they don't have:
→ No criminal charges against Chen or Puri — everything sits in civil allegations
→ Their own report admits they cannot confirm the woman photographed with Puri is the same Chen
→ No challenge to revenue, margins, backlog, or cash flow
Context matters. This dropped on earnings day, into a stock already down 30%+, with shorts sitting on $24B in paper gains. And a year ago, Carson Block himself said shorting NVIDIA would put you "out of business." The company didn't change — a governance window opened.
The real risk isn't this report. It's Dec 1, when Huang testifies before three House committees. If hearings reveal systemic export-control failures, the "ex-China" narrative underpinning the valuation gets repriced.
Until then: noise with a catalyst attached. Watch the testimony, not the short seller.
90
THE MARKET IS ENTERING A DANGEROUS POSITIONING TRAP.
Tech stocks look historically cheap on forward P/E, while traditional value stocks are trading at increasingly expensive valuations.
Neither side offers an obvious safe haven.
Stay in tech, and downward EPS revisions could trigger a brutal double hit: earnings compression and multiple contraction.
Rotate into value, and you risk buying an overcrowded trade just as valuations peak.
The bigger danger? Traditional value stocks could become the next crowded trade after semiconductors, attracting excessive capital before an equally violent reversal.
When both growth and value are expensive in their own ways, chasing sector rotation is not risk management. It's just moving from one crowded trade to another.
I'd rather focus on earnings quality, free cash flow, balance sheet strength and reasonable valuations than blindly follow the next rotation.
15
$AMD closed its $8.2 billion purchase of World Labs on November 16. Fei-Fei Li, who co-founded the startup, is now AMD's chief scientist. AMD paid in shares, not cash.
The stock fell 5.58% that day to $504.28, and is down 13.8% over two sessions. Plenty of coverage linked the drop to Li. The timeline doesn't: when the deal was announced in late September, AMD already fell about 4%. Investors had two months to price it in. November 16 was also a broad pullback across AI infrastructure, with Nvidia falling more.
So what actually changed? Nvidia has spent years building everything around physical AI: world models, robot simulation, and the CUDA software most developers already use. AMD had almost none of it. World Labs gives it about 70 researchers and a way to test future chip designs against real 3D and robotics computing before those designs are locked in. No acquisition, though, buys a decade of developer habits.
My view: this is a bet on computing demand that doesn't yet exist at scale. If robots and 3D simulation become the next big driver of chip sales, $8.2 billion looks cheap. If they don't, AMD paid a lot to narrow a gap it hasn't closed. The closing-day price tells us nothing either way. Watch whether AMD's next chips include features built for world models, and whether the World Labs team is still publishing a year from now.
1
64
SMART MONEY IS REPOSITIONING IN THE SPACE RACE. 🚀
Citadel just made two notable moves in its Q3 portfolio:
• Cut its $SPCX position by 94%.
• Opened a $221M position in $RKLB.
The message is worth watching.
Rocket Lab is emerging as a major player in the commercial space industry, with launch services and space systems creating multiple growth opportunities.
The space economy is expanding, and institutional capital is taking notice.
$RKLB is becoming a serious name in the next generation of aerospace.
Keep it on the radar.
43
Morgan Stanley published its 2027 outlook on Nov 15 and went maximum overweight global equities: 15 percentage points above benchmark, 70% of the portfolio, funded by cutting cash, commodities and fixed income. The S&P 500 target is 8,700 by end-2027 — roughly 15% upside, built on 14% earnings growth. Industrials are the top sector pick.
Japan and Europe were both upgraded to overweight, with TOPIX at 4,800 and MSCI Europe at 3,030. Emerging markets stay equal-weight, MSCI EM at 1,760. China stays equal-weight too: MSCI China at 9.6 times forward earnings, 8% profit growth, healthcare raised to overweight and internet cut to underweight.
Three assumptions sit behind that call. Valuations: MSCI ACWI trades near 15 times forward earnings, the lowest since 2023.
AI: 44% of companies in the bank's survey now report measurable benefits, up from about a third a year ago. So 2027 is a story about adopters, not just hyperscalers. China is still bottoming in 2027: real GDP at 4.4%, nominal growth slowing from 5.8% to 4.8%. A turn isn't expected until 2028.
My view: 8,700 is the least interesting number here. What matters is the rotation underneath it — away from a few AI builders toward a wider set of users, and away from the US alone toward Japan and Europe. That's a different portfolio from the one that worked in 2026, and it needs oil and rates to hold steady.
1
45
Berkshire's latest 13-F is a masterclass in positioning during the AI frenzy.
The headline: they did almost nothing in tech.
Apple still 25% of the portfolio, untouched.
Google 12%, not a single share added.
No chasing AI, no panic selling.
The real moves were elsewhere:
→ Lennar (homebuilder): position nearly DOUBLED. High rates crushed housing stocks — classic "be greedy when others are fearful."
→ Delta Air Lines: 3rd consecutive quarter of buying, +12% this time.
→ Financials trimmed: BofA -6%, Capital One -60%.
And the backdrop: $300B+ in cash, a net seller overall, but buying back its own stock aggressively.
The formula is neither offense nor defense. It's this: keep the core untouched, buy cyclical fear, hold plenty of cash.
The result? While semis swung wildly and tech struggled, Berkshire hit all-time highs — the S&P 500 fell over the same period.
In uncertain markets, not betting on a single narrative IS the edge.
1
25