

Former HFM | Institutional-grade quant research for individual investors | Not Financial Advice | https://xitter.cf/t.co/7AGyvCDsb5 | Email: [email protected]
United States
Joined July 2023
- Tweets11K
- Following95
- Followers15.8K
- Likes8.6K




Pinned Tweet
Every call goes up before the print. Every receipt goes up after.
Q2 2026, Alphatica Earnings Quality Signal:
0/6 BEARISH TSLA -14%
0/6 BEARISH INTC erased a 15% rally
0/6 BEARISH SNDK -7%
2/6 BEARISH JEF -10%
2/6 BEARISH CAR -10.19%
2/6 NEUTRAL TER beat called to the penny, sell-off called
3/6 NEUTRAL AAPL -9%
4/6 BULLISH AMZN +6%
5/6 BULLISH NOW +4.22%
5/6 BULLISH FFIV +11.4% off the low
Next up is NVDA, August 26 post-market. The call posts before it.
What else runs here: Institutional quality research that you will only find behind trading desks and prime brokerages.
The edge was never the data. It was who could afford the analysis. Q4 changes that.
Institutional and data licensing: [email protected]
Get on the list first: alphatica.io
$NVDA $SPY $QQQ

🚨 TOMORROW IS FOMC DAY.
FINANCE'S MOST FAMOUS FED TRADE IS DEAD.
In 2015, researchers found the S&P gained 0.50% in the 24 hours before Fed announcements. FinTwit made it a rule: buy the day before FOMC.
We retested it across 183 meetings, including 66 since 2018 that the original study never saw.
Pre-FOMC return: +0.08%, p = 0.45. That's no different from any ordinary day.
The strategy turned $10,000 into $14,861. Buy and hold turned it into $70,142. It earned less than T-bills.
But the data showed a different signal: what happens AFTER the Fed.
FOMC day: +0.22%
Next session: -0.17%
Next two sessions: -0.31%, p = 0.002
Gains on Fed day tend to get given back within 48 hours.
If SPY rallies tomorrow after the decision, watch the next two sessions. That's where the edge is now.
$SPY $QQQ

Everyone will watch whether GOOGL beats tomorrow.
That doesn't matter.
We tested GOOGL earnings back to 2004. Beat vs. miss has no statistically significant effect on SPY. Neither does pre-earnings volume.
One thing survived: how BIG the beat is.
SPY over the next 10 days, by beat size:
•Small ($0.00–0.01): +1.00%, 80% win rate
•Medium ($0.01–0.10): +0.56%, 75%
•Large ($0.10+): +2.06%, and +2.34% at 20 days
Any beat: SPY +1.22% at 10 days, 75% win rate (p = 0.0004).
🚨The live test since our June post:
July 22, GOOGL beat by $6.23. SPY was +2.99% 10 days later.
The setup:
•14 straight beats
•EPS consensus of $3.00, revenue consensus of $127.8B
•Revenue revisions 18 up, 2 down. EPS revisions 15 up, 9 down.
Analysts expect more sales but are split on how much reaches the bottom line.
The number to watch tomorrow isn't beat or miss. It's the size of the beat.
$GOOGL $SPY

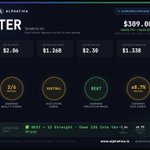
TER just reported. We called BEAT. It beat on both lines. The stock is down 6.4% after hours to $303.01.
Street Adj. EPS: $2.06
Alphatica Adj. EPS: $2.30
Actual Adj. EPS: $2.29 ✅
Street Revenue: $1.26B
Alphatica Revenue: $1.33B
Actual Revenue: $1.31B ✅
EPS beat the street by 11.2% and landed one cent from our number. It cleared the $2.20 beat line we flagged and the top of the company's own $1.85 to $2.15 guide. Revenue beat by 3.8% and grew 70% from a year ago. Our revenue number was 1.5% too high.
We said the beat was not the question. The question was whether the Q4 guide showed AI test demand still climbing. Q4 guide: adjusted EPS $1.95 to $2.25 and revenue $1.25B to $1.35B. The midpoints sit above the street, but they are flat to down from tonight's quarter. Not climbing.
Our Earnings Quality Signal was 2/6 NEUTRAL going in. It said the score moves when revenue growth turns into margin expansion. Tonight, EPS fell 7.3% from June on revenue down 1.4%. GAAP net margin slipped from 28.2% to 26.1%. The neutral read held.
The risk signal priced an 8.7% move. The first move is down 6.4%, inside that.
Not Investment Advice.
$TER


TER reports tonight after the close.
12 for 12 on beats over the last three years, and the last three came in 20% to 30% above the street. The stock is down 23% in four weeks and 37% off its high going into the print.
Street EPS: $2.06
Street Revenue: $1.26B
Alphatica Estimates:
EPS: $2.30
Revenue: $1.33B
OUR CALL: BEAT ✅
Management guided $1.85 to $2.15 on EPS and $1.2B to $1.3B on revenue. The street sits just above the midpoint on both. Teradyne has beaten the last four quarters by an average of 19.8%. We are at $2.30, an 11.7% beat that clears the top of the guide, and $1.33B on revenue, 5.4% above the street.
WHY THE BEAT:
The street wants revenue up 64% from a year ago. Teradyne has beaten on revenue in each of the last four quarters, by 3.4% to 11.6%. In July the revenue guide came in 21% above where the street was sitting. Management said it reflected robust AI-related demand, with record memory test in DRAM and NAND.
Operating margin has gone 18.9%, 27.1%, 36.9%, 32.9% over the last four quarters. Gross margin has held between 57% and 61% the whole way. The extra revenue is falling to the bottom line.
Analysts are still raising. FY2027 EPS estimates went from $9.94 to $11.46 in 90 days. The freshest quarter estimates sit above consensus.
WHY THE STOCK FELL:
No company news. On October 22 chip equipment sold off as a group. Teradyne fell 11% to $308.75 that day, with Lam down about 12% and KLA down about 10%. The stock now trades at 27x FY2027 estimates.
The beat is not the question tonight. The question is whether the Q4 guide shows AI test demand still climbing.
OUR FOUR SIGNALS:
Earnings Quality: 2/6 NEUTRAL. Cash conversion is clean. Operating cash flow ran 1.22x net income and stock comp is only 2% of revenue. What holds the score back is the FY2025 10-K: operating margin 20.4% against 26.3% at the 2022 peak, with no operating leverage yet. The 2026 quarters have changed that, at 36.9% and 32.9%. The next annual filing is where the score can move.
Disclosure Signal: NEUTRAL. Filing tone improved slightly in the 10-K after three years of decline. The 2026 quarterlies dipped and only partly recovered, and the June 10-Q is still weaker than a year ago. Risk factors were meaningfully updated in Q2. No clear improvement, no clear deterioration.
Prediction Model: BEAT. 12 straight quarters. Last four averaged a 19.8% surprise.
Earnings Risk Signal: +/-8.7% NEUTRAL. IV spread -1.66, calls and puts priced about even. Expected move about $27. The last four reports moved 20.5%, 13.4%, 19.4% and 0.4% the next day, an average of 13.4%. Options are pricing less than this stock has recently delivered.
THE SETUP:
We have seen this pattern before. In July the stock fell 14.3% in the five days before the report, then rose 25.9% in the five days after. Three of the last four reports were followed by five-day gains of 21.7%, 24.2% and 25.9%. The one that was not fell 6.1%.
September-quarter reports have been Teradyne's best. Over 23 reports the stock has averaged +3.7% over the next five days and +5.8% over ten.
Short volume ratio averaged 50.8% over 20 days and hit 59.8% on the October 22 selloff. Shorts are leaning in, not backing off.
Beat line: $2.20, the top street estimate.
Options range: about $282 to $336.
$309 is the close. $2.06 is the bar. AI test demand is the story. The beat is likely. The guide decides whether the 23% comes back.
Not Investment Advice.
$TER $SPY

This is not helping either. Right before the close:
Seagate Technology Price Target Cut to $1100.00/Share From $1400.00 by Rosenblatt
$STX
STX reports tonight after the close.
6/6 on our quality signal, a perfect score. 13 straight beats. And the stock is down 30% in four weeks going into the print.
Street EPS: $7.43
Street Revenue: $4.14B
Alphatica Estimates:
EPS: $8.00
Revenue: $4.29B
OUR CALL: BEAT ✅
Seagate has beaten the last four quarters by an average of 11.8%. We are sizing at $8.00, a 7.7% beat, and $4.29B on revenue, 3.6% above the street.
WHY THE BEAT:
Gross margin has gone 39.4%, 41.6%, 46.5%, 52.3% over the last four quarters. That is pricing power, not volume. The street is asking for revenue up 57% from a year ago and up 14% from June, in a quarter with one fewer week. Revenue has beaten in each of the last four quarters by 2.5% to 5.1%.
Analysts are still chasing. FY2027 EPS estimates went from $28.58 to $36.66 in 90 days, with 12 raises and zero cuts. The freshest estimates sit above consensus.
WHY THE STOCK FELL:
On October 2, Toshiba said it plans to double its AI data-center drive capacity by fiscal 2027. The market read that as a supply threat to pricing. Seagate is now 41% below its $1,145 high and trades at 17.6x FY2027 estimates.
The beat is not the question tonight. The question is whether management says pricing holds.
OUR FOUR SIGNALS:
Earnings Quality: 6/6 BULLISH. A full cycle turn. A loss in FY2023, a 33.6% operating margin in FY2026. Debt down 37%. Equity flipped from a $1.49B deficit to positive $2.17B. Operating cash flow 1.15x net income. Management's internal accounting signals point to confidence in future earnings.
Disclosure Signal: NEUTRAL. Seagate rewrote its risk factors almost entirely this year, 61% vocabulary turnover. Tone is neutral.
Prediction Model: BEAT. 13 straight quarters. Last four averaged an 11.8% surprise.
Earnings Risk Signal: +/-6.2% NEUTRAL. IV spread +1.29. Expected move about $41.74. The last four reports moved 2.3%, 11.1%, 19.1% and 19.1% the next day, an average of 12.9%. Options are pricing about half of what this stock has recently delivered.
THE SETUP:
We have seen this pattern before. In July the stock fell 16.2% in the five days before the report, then rose 13.1% in the five days after. The last four reports were followed by five-day gains of 12.3%, 19.6%, 33.2% and 13.1%.
Short volume ratio averaged 40.2% over 20 days and hit 28.1% on October 16. Even with a 30% drawdown, shorts are not leaning in.
Beat line: $7.85, the top street estimate.
Options range: about $633 to $716.
$644 is the close. $7.43 is the bar. Pricing is the story. The beat is likely. The guide decides whether the 30% comes back.
Not Investment Advice.
$STX $QQQ

STX just reported. We called BEAT. It beat on both lines. The stock is down 5.1% after hours to $611.19.
Street Adj. EPS: $7.43
Alphatica Adj. EPS: $8.00
Actual Adj. EPS: $7.68 ✅
Street Revenue: $4.14B
Alphatica Revenue: $4.29B
Actual Revenue: $4.2B ✅
EPS beat the street by 3.4%. That makes 14 straight beats. Revenue beat by 1.4% and grew 60% from a year ago. Adjusted EPS nearly tripled, up 194%.
Where we were wrong: our numbers ran hot. We had $8.00 and $4.29B. EPS came in 4.0% under ours and missed the $7.85 beat line we flagged. Revenue came in 2.1% under ours. It was also the smallest revenue beat in five quarters. The last four ran 2.5% to 5.1%.
We said before the print that the beat was not the question. The question was whether pricing holds after Toshiba's capacity plan. A beat that cleared the street but not the high end did not settle it. The stock is lower.
The risk signal priced a 6.2% move. The first move is down 5.1%, inside that.
The guide and gross margin are not in the headlines yet. Those decide whether this holds. We will update when they post.
Not Investment Advice.
$STX $SPY

STX reports tonight after the close.
6/6 on our quality signal, a perfect score. 13 straight beats. And the stock is down 30% in four weeks going into the print.
Street EPS: $7.43
Street Revenue: $4.14B
Alphatica Estimates:
EPS: $8.00
Revenue: $4.29B
OUR CALL: BEAT ✅
Seagate has beaten the last four quarters by an average of 11.8%. We are sizing at $8.00, a 7.7% beat, and $4.29B on revenue, 3.6% above the street.
WHY THE BEAT:
Gross margin has gone 39.4%, 41.6%, 46.5%, 52.3% over the last four quarters. That is pricing power, not volume. The street is asking for revenue up 57% from a year ago and up 14% from June, in a quarter with one fewer week. Revenue has beaten in each of the last four quarters by 2.5% to 5.1%.
Analysts are still chasing. FY2027 EPS estimates went from $28.58 to $36.66 in 90 days, with 12 raises and zero cuts. The freshest estimates sit above consensus.
WHY THE STOCK FELL:
On October 2, Toshiba said it plans to double its AI data-center drive capacity by fiscal 2027. The market read that as a supply threat to pricing. Seagate is now 41% below its $1,145 high and trades at 17.6x FY2027 estimates.
The beat is not the question tonight. The question is whether management says pricing holds.
OUR FOUR SIGNALS:
Earnings Quality: 6/6 BULLISH. A full cycle turn. A loss in FY2023, a 33.6% operating margin in FY2026. Debt down 37%. Equity flipped from a $1.49B deficit to positive $2.17B. Operating cash flow 1.15x net income. Management's internal accounting signals point to confidence in future earnings.
Disclosure Signal: NEUTRAL. Seagate rewrote its risk factors almost entirely this year, 61% vocabulary turnover. Tone is neutral.
Prediction Model: BEAT. 13 straight quarters. Last four averaged an 11.8% surprise.
Earnings Risk Signal: +/-6.2% NEUTRAL. IV spread +1.29. Expected move about $41.74. The last four reports moved 2.3%, 11.1%, 19.1% and 19.1% the next day, an average of 12.9%. Options are pricing about half of what this stock has recently delivered.
THE SETUP:
We have seen this pattern before. In July the stock fell 16.2% in the five days before the report, then rose 13.1% in the five days after. The last four reports were followed by five-day gains of 12.3%, 19.6%, 33.2% and 13.1%.
Short volume ratio averaged 40.2% over 20 days and hit 28.1% on October 16. Even with a 30% drawdown, shorts are not leaning in.
Beat line: $7.85, the top street estimate.
Options range: about $633 to $716.
$644 is the close. $7.43 is the bar. Pricing is the story. The beat is likely. The guide decides whether the 30% comes back.
Not Investment Advice.
$STX $QQQ
Visa earnings are out. We called BEAT. $3.48 adjusted vs $3.44 street. Our beat line was $3.48. Hit it exactly.
Revenue $12.1B vs $12.09B street. In line. We had $12.25B. Too high.
The model said $2.75 because it reads GAAP. GAAP came in at $3.19. Adjusted came in at $3.48. The street grades adjusted.
Cross-border +14%. Payments volume +9%. Dividend up 16%.
Stock down about 1.2%. The line that stands out: client incentives up 21% against revenue up 13%. Visa is paying more to win volume.
Options priced a 2.5% move. The first move is inside it.
Right call. Our numbers ran a little hot. Both go on the record.
Not Investment Advice.
$V $MA

V reports tonight after the close.
Street EPS: $3.44
Street Revenue: $12.09B
Alphatica EPS: $3.53
Alphatica Revenue: $12.25B
OUR CALL: BEAT ✅
Visa has beaten 11 of the last 12 quarters by an average of 3.1%. Our $3.53 sits above every estimate on the street.
OUR FOUR SIGNALS:
Alphatica Earnings Quality Signal: 4/6 BULLISH. Net income up four straight years. Cash runs 1.15x earnings.
Disclosure Signal: BULLISH. Latest 10-Q tone is the best since late 2024. Zero litigious language.
Earnings Prediction Model: BEAT.
Earnings Risk: NEUTRAL. Calls and puts priced even.
WHAT TO WATCH:
Beat line: $3.48, the top street estimate.
Options range: $390 to $410, a 2.5% move. The 3-year average move is 2.2%. Premium is priced above what this stock usually does.
52-week high: $414.60. A clean beat has room to test it.
Short volume dropped to 34% on Monday, the low of the last 20 sessions.
September-quarter reports have averaged +2.6% over the next five days, up 12 of 18 times. Not statistically significant, but the lean is up.
Not Investment Advice.
$V $MA $SPY

TER reports tonight after the close.
12 for 12 on beats over the last three years, and the last three came in 20% to 30% above the street. The stock is down 23% in four weeks and 37% off its high going into the print.
Street EPS: $2.06
Street Revenue: $1.26B
Alphatica Estimates:
EPS: $2.30
Revenue: $1.33B
OUR CALL: BEAT ✅
Management guided $1.85 to $2.15 on EPS and $1.2B to $1.3B on revenue. The street sits just above the midpoint on both. Teradyne has beaten the last four quarters by an average of 19.8%. We are at $2.30, an 11.7% beat that clears the top of the guide, and $1.33B on revenue, 5.4% above the street.
WHY THE BEAT:
The street wants revenue up 64% from a year ago. Teradyne has beaten on revenue in each of the last four quarters, by 3.4% to 11.6%. In July the revenue guide came in 21% above where the street was sitting. Management said it reflected robust AI-related demand, with record memory test in DRAM and NAND.
Operating margin has gone 18.9%, 27.1%, 36.9%, 32.9% over the last four quarters. Gross margin has held between 57% and 61% the whole way. The extra revenue is falling to the bottom line.
Analysts are still raising. FY2027 EPS estimates went from $9.94 to $11.46 in 90 days. The freshest quarter estimates sit above consensus.
WHY THE STOCK FELL:
No company news. On October 22 chip equipment sold off as a group. Teradyne fell 11% to $308.75 that day, with Lam down about 12% and KLA down about 10%. The stock now trades at 27x FY2027 estimates.
The beat is not the question tonight. The question is whether the Q4 guide shows AI test demand still climbing.
OUR FOUR SIGNALS:
Earnings Quality: 2/6 NEUTRAL. Cash conversion is clean. Operating cash flow ran 1.22x net income and stock comp is only 2% of revenue. What holds the score back is the FY2025 10-K: operating margin 20.4% against 26.3% at the 2022 peak, with no operating leverage yet. The 2026 quarters have changed that, at 36.9% and 32.9%. The next annual filing is where the score can move.
Disclosure Signal: NEUTRAL. Filing tone improved slightly in the 10-K after three years of decline. The 2026 quarterlies dipped and only partly recovered, and the June 10-Q is still weaker than a year ago. Risk factors were meaningfully updated in Q2. No clear improvement, no clear deterioration.
Prediction Model: BEAT. 12 straight quarters. Last four averaged a 19.8% surprise.
Earnings Risk Signal: +/-8.7% NEUTRAL. IV spread -1.66, calls and puts priced about even. Expected move about $27. The last four reports moved 20.5%, 13.4%, 19.4% and 0.4% the next day, an average of 13.4%. Options are pricing less than this stock has recently delivered.
THE SETUP:
We have seen this pattern before. In July the stock fell 14.3% in the five days before the report, then rose 25.9% in the five days after. Three of the last four reports were followed by five-day gains of 21.7%, 24.2% and 25.9%. The one that was not fell 6.1%.
September-quarter reports have been Teradyne's best. Over 23 reports the stock has averaged +3.7% over the next five days and +5.8% over ten.
Short volume ratio averaged 50.8% over 20 days and hit 59.8% on the October 22 selloff. Shorts are leaning in, not backing off.
Beat line: $2.20, the top street estimate.
Options range: about $282 to $336.
$309 is the close. $2.06 is the bar. AI test demand is the story. The beat is likely. The guide decides whether the 23% comes back.
Not Investment Advice.
$TER $SPY
STX reports tonight after the close.
6/6 on our quality signal, a perfect score. 13 straight beats. And the stock is down 30% in four weeks going into the print.
Street EPS: $7.43
Street Revenue: $4.14B
Alphatica Estimates:
EPS: $8.00
Revenue: $4.29B
OUR CALL: BEAT ✅
Seagate has beaten the last four quarters by an average of 11.8%. We are sizing at $8.00, a 7.7% beat, and $4.29B on revenue, 3.6% above the street.
WHY THE BEAT:
Gross margin has gone 39.4%, 41.6%, 46.5%, 52.3% over the last four quarters. That is pricing power, not volume. The street is asking for revenue up 57% from a year ago and up 14% from June, in a quarter with one fewer week. Revenue has beaten in each of the last four quarters by 2.5% to 5.1%.
Analysts are still chasing. FY2027 EPS estimates went from $28.58 to $36.66 in 90 days, with 12 raises and zero cuts. The freshest estimates sit above consensus.
WHY THE STOCK FELL:
On October 2, Toshiba said it plans to double its AI data-center drive capacity by fiscal 2027. The market read that as a supply threat to pricing. Seagate is now 41% below its $1,145 high and trades at 17.6x FY2027 estimates.
The beat is not the question tonight. The question is whether management says pricing holds.
OUR FOUR SIGNALS:
Earnings Quality: 6/6 BULLISH. A full cycle turn. A loss in FY2023, a 33.6% operating margin in FY2026. Debt down 37%. Equity flipped from a $1.49B deficit to positive $2.17B. Operating cash flow 1.15x net income. Management's internal accounting signals point to confidence in future earnings.
Disclosure Signal: NEUTRAL. Seagate rewrote its risk factors almost entirely this year, 61% vocabulary turnover. Tone is neutral.
Prediction Model: BEAT. 13 straight quarters. Last four averaged an 11.8% surprise.
Earnings Risk Signal: +/-6.2% NEUTRAL. IV spread +1.29. Expected move about $41.74. The last four reports moved 2.3%, 11.1%, 19.1% and 19.1% the next day, an average of 12.9%. Options are pricing about half of what this stock has recently delivered.
THE SETUP:
We have seen this pattern before. In July the stock fell 16.2% in the five days before the report, then rose 13.1% in the five days after. The last four reports were followed by five-day gains of 12.3%, 19.6%, 33.2% and 13.1%.
Short volume ratio averaged 40.2% over 20 days and hit 28.1% on October 16. Even with a 30% drawdown, shorts are not leaning in.
Beat line: $7.85, the top street estimate.
Options range: about $633 to $716.
$644 is the close. $7.43 is the bar. Pricing is the story. The beat is likely. The guide decides whether the 30% comes back.
Not Investment Advice.
$STX $QQQ
V reports tonight after the close.
Street EPS: $3.44
Street Revenue: $12.09B
Alphatica EPS: $3.53
Alphatica Revenue: $12.25B
OUR CALL: BEAT ✅
Visa has beaten 11 of the last 12 quarters by an average of 3.1%. Our $3.53 sits above every estimate on the street.
OUR FOUR SIGNALS:
Alphatica Earnings Quality Signal: 4/6 BULLISH. Net income up four straight years. Cash runs 1.15x earnings.
Disclosure Signal: BULLISH. Latest 10-Q tone is the best since late 2024. Zero litigious language.
Earnings Prediction Model: BEAT.
Earnings Risk: NEUTRAL. Calls and puts priced even.
WHAT TO WATCH:
Beat line: $3.48, the top street estimate.
Options range: $390 to $410, a 2.5% move. The 3-year average move is 2.2%. Premium is priced above what this stock usually does.
52-week high: $414.60. A clean beat has room to test it.
Short volume dropped to 34% on Monday, the low of the last 20 sessions.
September-quarter reports have averaged +2.6% over the next five days, up 12 of 18 times. Not statistically significant, but the lean is up.
Not Investment Advice.
$V $MA $SPY
SPY MIDDAY | Tuesday October 27 | FOMC tomorrow
$770.51. Up 0.67%. Friday's selloff is fully repaired.
YESTERDAY:
At 12:05PM SPY was $765.15 with the rebuild underway. It closed $765.37.
By midday today it's back above $770.
MON 12:05PM → TUE 11:57AM:
Price: $765.15 → $770.51
Composite: +17.7 → +26.8 (lean bullish)
Options surface: -$1.10B → -$391M
Engine: +53M → +103M
Net premium: +$480M → +$667M
Premium: 68% calls → 77% calls
Every reading improved again. The engine doubled. New calls are opening almost 10 to 1 over closing.
THE MAGNETS ARE BACK:
Positive gamma from $770 to $790:
Friday: $295M
Monday: $450M
Today: $855M
Last Wednesday, before META and IBM, it was $960M. Two sessions and it's almost all the way back.
$770 (+$133M), at price
$772 (+$72M)
$775 (+$66M)
$780 (+$121M)
$800 (+$143M), the biggest positive strike on the board
THE FOMC CATCH:
About a third of that positive gamma is today's calls.
$770: +$108M of +$133M expires at 4PM
$771: +$56M of +$66M expires at 4PM
$772: +$52M of +$72M expires at 4PM
The cushion right at price thins out the night before the Fed. What carries into tomorrow is $775, $780 and $800.
YESTERDAY'S CLIFF:
$767 (-$90M) is all today's puts. It expires at 4PM.
BELOW:
$765 (-$160M)
$762 max pain
$760 (-$138M)
$755 (-$159M)
$750 (-$225M)
About $1.2B of negative gamma from $740 to $767.
$770 is the line. $770.51 is price. $765 is the first cliff. $762 is max pain.
The rebuild is done. The magnets are back. Tomorrow the Fed tests it with a thinner cushion than today.
$SPY $QQQ

From the Alphatica Bot:
What were the main drivers of Boeing’s revenue and margin performance this quarter?
Boeing reported third quarter 2026 revenue of $24.2 billion, up 4% from $23.3 billion a year earlier. According to the release, revenue “primarily reflect[ed] higher defense and services volume and less favorable commercial delivery mix.”
Main revenue drivers
Defense, Space & Security revenue rose to $7.9 billion, up 15%, “driven by higher volume.”
Global Services revenue increased to $5.6 billion, up 4%, also “on higher volume.”
Commercial Airplanes revenue was $10.7 billion, down 3%, despite deliveries increasing slightly to 161 from 160, because of a “less favorable delivery mix.”
Main margin drivers
At the total company level, GAAP operating margin improved to 1.5% from (20.5)% last year, while core operating margin improved to 0.8% from (21.7)%.
In Commercial Airplanes, operating margin was (6.5)%. The release says this “primarily reflects less favorable delivery mix, higher projected costs associated with future production rate adjustments and higher estimated supply chain costs.”
In Defense, Space & Security, operating margin improved to 6.2% from 1.7%, primarily due to “a $252 million gain on the HRL Laboratories sale and improved operational performance.”
In Global Services, operating margin improved to 18.3% from 17.5%, reflecting “favorable volume and mix.”
Overall, Boeing’s quarter was supported by stronger defense and services activity, while commercial margins were pressured by mix and cost factors.
We would be buyers of this dip.
$BA

Eight months ago this account had 450 followers. Today it has 15,800.
No promotions and no engagement pods. Just data, research and receipts.
For the 300 new followers just joining us, here's what we do. We build the kind of institutional-grade quant signals and research that usually lives behind Bloomberg terminals and hedge fund desks:
→ Earnings quality signals that flag accounting stress before the market prices it in
→ Institutional vs. retail flow classification on every major name
→ SPX/QQQ positioning and dealer exposure analysis
→ Special reports and short-seller deep dives
→ Statistically tested trading ideas
→ Honest scorecards: we show the misses, not just the wins
To everyone who's been here, thank you. Your questions and pushback made every signal sharper.
Email subscribers get our original research first. They'll also be the first to hear when our institutional grade product goes live.
We will be in our platform soon and encourage you to use the sign up Link in bio.

Everyone's watching TLT calls into FOMC, expecting a bond rally.
History says that's the wrong trade.
In 25 episodes where TLT call positioning hit the top 5%, bonds weren't the winner.
Equities were:
SPY: +1.49% in 5 days vs +0.23% normally (p = 0.005), up 80% of the time
QQQ: +1.88% vs +0.29% normally (p = 0.009), up 76% of the time
Tech led.

SPX GEX Levels: Tuesday, October 27
SPX closed Monday at 7,676.77, up 53 points (+0.70%), inside our 7,545–7,705 range. We said Monday's setup would amplify whatever came next. It amplified a bounce.
Net gamma repaired $487M in one session, from -$655M to -$168M. Still negative, but the shape changed in a way that matters.
The overhead is light. Between spot and the flip at 7,731, there's only -$59M: 7,700 (-$44M) and 7,725 (-$15M). 7,750 is flat. Above that, positive gamma starts: 7,775 (+$27M), 7,800 (+$79M), 7,825 (+$70M), 7,850 (+$65M).
The floor is still heavy. 7,650 (-$98M) is the first test below spot. Then 7,600 (-$122M, the top put-volume strike), 7,550 (-$61M) and 7,500 (-$114M). That's -$545M from 7,500 to 7,650.
So the structure is lopsided. A rally has little in the way until the flip. A drop through 7,650 hits a stack that accelerates it.
Flow is split. Puts at 7,400–7,650, calls at 7,750–7,900. Volume put/call 1.53, right at the line. ATM IV eased from 16.7% to 15.4%.
FOMC is tomorrow. The day before a Fed decision often compresses as traders wait, and today's range reflects that. The bigger move is more likely to come after 2pm Wednesday, and with net gamma still negative, it will travel.
Predicted range: 7,630–7,745. Hold 7,650 and the flip is in reach. Lose it and 7,600 is next.
$SPX $SPY
