

Wall Street Writer: Wide Moat Research and Seeking Alpha https://nitter.gq/t.co/DCJLTvT3sm
United States
Joined May 2009
- Tweets21.6K
- Following5.1K
- Followers23.3K
- Likes20.9K




I'll be listening closely to $VICI's earnings call this morning. The good news:
✅ Q3 AFFO beat expectations
✅ 2026 guidance raised
✅ Dividend increased to $1.84 annually (7.8% yield)
✅ NEW $2 billion share buyback
The elephant in the room? $CZR
A $313M credit reserve tied to $CZR raises questions about tenant health and rent coverage.
At ~10x AFFO, is the market pricing in too much bad news?
I'll be listening closely for answers on $CZR's capital allocation and the potential for a valuation reset.
The dividend looks attractive, but can $VICI finally regain investor confidence?

🚨 WARNING: Is Your High-Yield Dividend a SUCKER YIELD?
A 15% dividend sounds great… until it gets CUT!
On this week's Wide Moat Show, Nicholas Ward and I break down 3 high-yield stocks:
🔴 $STWD — 15% yield, dividend at risk?
🟡 $OWL — 9.5% yield, speculative opportunity?
🟢 $LADR — A better risk/reward?
I explain why I see a 60–70% probability of a dividend cut at $STWD.
Remember: It's not how much a stock pays you. It's how much you KEEP.
🎥 Watch The WIDE MOAT SHOW (I'll drop the link in the comments)
#REITs #DividendInvesting

$EQIX continues to demonstrate why it's one of my favorite data center REITs!
Q3 annualized bookings surged 35% to $533M, AFFO/share jumped 18%, and management raised 2026 guidance for the THIRD consecutive quarter.
Shares are up 3% after hours.
AI demand is real, pricing power is strengthening, and $EQIX's competitive moat keeps widening.
This is what I call a SWAN stock!
LOng $EQIX

Earlier this week, I published a @SeekingAlpha deep dive on $OWL, an alternative asset manager yielding 9.5%.
The debate was lively, especially around dividend safety.
My conclusion: SPECULATIVE STRONG BUY.
I see potential for 25%+ annualized total returns, but this is NOT a SWAN.
Looking forward to revisiting my thesis after Q3 earnings on October 29.
#Investing #Dividends

$DY looks compelling and is quietly becoming a major beneficiary of the AI infrastructure boom.
✅ $12.2 BILLION backlog, up from $8B a year ago
✅ Building Systems EBITDA margins above 20%
✅ Power Solutions running 30% ahead of acquisition expectations
✅ Exposure to fiber networks, data centers, and electrical infrastructure
The market appears focused on near-term margin pressure while potentially overlooking a powerful long-term growth story.
AI needs more than chips. It needs power, fiber, and infrastructure.
Adding $DY to my Wide Moat Research watchlist.
#AI #Infrastructure #Investing

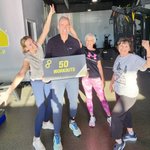
50 workouts and counting! 💪
I've spent much of my career studying companies with wide moats, but I've learned that one of the best investments you can ever make is in your own health.
Just like investing, fitness requires discipline, consistency, and a long-term mindset.
Special thanks to my amazing workout crew for keeping me motivated!
The best returns in life aren't always measured in dollars. 💪🏋️
#Fitness #Longevity #InvestInYourself

🚨 SUCKER YIELD ALERT: $STWD
$STWD is yielding a whopping 15.3% but look beneath the hood:
⚠️ 132% dividend payout ratio
⚠️ Dividend frozen for 10+ years
⚠️ Earnings failing to cover the payout
⚠️ Elevated leverage
Even Barry Sternlicht can't defy dividend mathematics. I estimate a 65% probability of a dividend cut within 12 months.
My rating: SELL.
Remember: The safest dividend isn't always the highest.
Sleep Well At Night. 🦉
(I'll drop a link to my latest @SeekingAlpha article in the comment section)


$JLL is looking especially attractive!
📈 10 straight quarters of 25%+ EPS growth and 9%+ revenue growth.
✅ Operating margins expanded 8 straight quarters
✅ Operating cash flow +81%
✅ Free cash flow doubled to $1.12B
✅ Shares outstanding down 10% over 5 years
Yet $JLL trades at just 12.6x earnings vs. its historical 15.2x P/E, with analysts forecasting 11% growth in 2027 and 12% in 2028.
No dividend, but impressive capital allocation.
Adding $JLL to the Wide Moat Watchlist! 🏰

After nearly 16 years of writing on @SeekingAlpha, comments like these still mean the world to me. My latest deep dive on $OWL generated some incredible reader feedback:
💬 “I'd put this article high on the list of your best ever.”
💬 “One of the cleanest and most objective executive-memo style articles regarding OWL I've read.”
💬 “A very balanced and objective note.”
💬 “WOW! What an informative article.”
I spent considerable time examining $OWL's history, earnings, dividend safety, valuation, and private credit risks.
My conclusion: Speculative Strong Buy. Not a SWAN, but potentially a compelling risk/reward opportunity.
Thank you to everyone who reads, challenges, and supports my research. That's what makes this work so rewarding.
$OWL $ARES $BX $APO Long : $HHH $OWL $BX

$OWL: The feedback on my latest @SeekingAlpha article has been terrific! I'm grateful to my 120,000 followers for the thoughtful comments and engagement. I'll post the article in the comment section below. Long $OWL


☕🦉 Coffee with the $OWL this morning!
Just published my latest @SeekingAlpha deep dive.
📈 9.5% dividend yield
💰 $319B in AUM
⚠️ Payout ratio above 100%
🎯 SPECULATIVE STRONG BUY
Is this a sucker yield or a golden opportunity?
My conclusion: This $OWL is no SWAN… but it's not a sucker yield either!
Grab your coffee and check out my latest research on @SeekingAlpha ☕🦉
$OWL #DividendInvesting #PrivateCredit
I was glad to see my letter to the editor featured in this week's @barronsonline mailbag.
John D. Rockefeller understood something many investors have forgotten:
Dividends are among the clearest expressions of shareholder ownership.
Buybacks have their place, but dividends represent a recurring financial commitment to shareholders.
With the $SPY yielding near historic lows, dividend discipline matters more than ever.
#Dividends #Investing #Barrons

$OWL: Margin of Safety or Value Trap?
Shares now yield a whopping 9.5%, trading at just 11.1x earnings. Compare that with peers:
$ARES: 22.2x
$APO: 13.4x
$BX: 20.3x
$KKR: 12.2x
$BAM: 26.6x
Is the market pricing in excessive fear or signaling deeper problems with private credit?
I'll be digging into the balance sheet, dividend safety, and valuation in a @SeekingAlpha deep dive this weekend.
Stay tuned. 🦉

Excellent recap by @HoyaCapital ...
$REXR is showing signs of a turnaround in Southern California industrial real estate.
✅ Occupancy rebounds to 96.9%
✅ Leasing volume surges
✅ $1.5B in asset sales
✅ $709M in share buybacks
✅ Leverage down to 3.8x
What catches my attention?
Selling assets at a 5.5% yield and repurchasing shares at an implied mid-6% yield.
Negative rent spreads remain a headwind, but I'm encouraged by the improving fundamentals.
$REXR #REITs #Investing


📊 REIT Earnings Quick Takes
Rexford Industrial (REXR) - the fourth-largest industrial REIT with an exclusive focus on the Southern California market - rallied 5% today after reporting an improved leasing quarter, raising its full-year earnings and same-store NOI outlooks, and making substantial progress on its $2B portfolio realignment and deleveraging plan.
REXR raised its 2026 FFO growth outlook to 1.0% from 0.2% previously, while increasing cash same-store NOI guidance to 0.5% from a 0.3% decline.
Operating trends improved meaningfully beneath the headline numbers, with 3.7M SF of leases signed, nearly 60% above the trailing quarterly average, while same-property occupancy increased 200 basis points sequentially to 96.9%.
Leasing economics remain the primary near-term challenge, although trends moved in the right direction, with cash leasing spreads improving to -3.0% from -11.3% in Q2.
REXR expects spreads to remain negative in the low-to-mid teens on average over the next couple of years as leases signed near the 2022-2023 market peak roll over, but noted that the portfolio realignment has removed many of the assets facing the steepest rent resets.
Encouragingly, Southern California market rents increased roughly 1% sequentially, marking the first quarterly increase since 2023, while the market posted a second consecutive quarter of positive absorption.
The bigger strategic story remains REXR's portfolio reset, with $1.5B of dispositions completed year-to-date, including a $1.2B portfolio sale at a 5.5% NOI yield. Proceeds have been redeployed into debt reduction and share repurchases, with roughly $709M of stock repurchased year-to-date while leverage fell to 3.8x.
REXR noted that repurchases currently offer an implied yield in the mid-6% range, making them more attractive than acquisitions and providing a compelling arbitrage relative to the assets being sold.
The results reinforce the stabilization theme highlighted in our earnings preview, with recovering tenant demand, constrained new supply, and improving absorption beginning to translate into stronger occupancy.
REXR noted that demand was particularly broad across advanced manufacturing and logistics users, while increasingly strong demand for high-quality Class A space is benefiting its repositioning and development pipeline.
$REXR | @AllTheREITNews | @DailyREITBeat | @ReitAcademy | @bradthomas | #REITs #Dividends #Investing


$EGP is one of my favorite industrial REITs and just delivered another strong quarter!
$EGP continues to demonstrate why I favor high-quality Sunbelt industrial real estate.
📈 Q3 FFO/share +7.9% YoY
💰 Cash leasing spreads +20.6%
🏢 Occupancy approaching 97%
🚀 2026 FFO guidance RAISED to $9.61/share
🏗️ Development pipeline expanding, with 8.1% projected yields
📊 Cash same-store NOI growth guidance raised to +7.5%
Not everything is perfect. Development pre-leasing has softened, and CA remains a laggard.
But $EGP continues to demonstrate pricing power, disciplined development, and durable earnings growth.
This is what I call a SWAN (Sleep Well At Night) REIT.
Quality matters. Valuation matters. And dividends matter.
$EGP $PLD $REXR $STAG

$EPRT delivering again. 🏠📈
+3.6% after hours following Q3 results:
• AFFO/share +6% YoY to $0.51
• Rental revenue $157.8M — ahead of estimates
• 2026 AFFO guidance tightened to $2.02–$2.05
• 2027 AFFO guidance introduced at $2.10–$2.18
What stands out to me: disciplined underwriting in a changing cost-of-capital environment.
That’s exactly what I want from a net lease REIT: steady growth, disciplined capital allocation, and no need to swing for the fences.
$EPRT remains one of my favorite net lease REITs.