

Boutique M&A Firm specialized in DTC & Amazon Brands
Joined October 2015
- Tweets82
- Following23
- Followers2.5K
- Likes595




New Deal | Supplement Brand
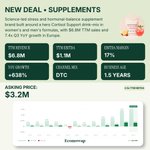
Science-led stress and hormonal-balance supplement brand selling drink-mixes in women’s and men’s formulas, built around a hero cortisol support product. Launched in April 2025, it has reached $6.8M in TTM revenue and $1.1M in EBITDA at an 80.9% gross margin, selling through Shopify DTC, TikTok Shop and Amazon.fr across France, Italy, Spain and Germany.
Why this opportunity stands out:
• Repeat demand is building: 27% of customers on recent cohorts reorder within 6 months, up from ~15% in 2025, with subscribe-and-save still to be built on a 112k-subscriber email list.
• An asset-light operation with a team in place: ~20 freelance specialists led by a full-time COO, one French 3PL, Amazon FBA and +€317K in LTM operating cash flow.
• Markets and channels are still opening up: pharmacy distribution is live in 2 of 100 targeted pharmacies, and Italy, Spain and Germany are early, with Poland and the Nordics next.
Asking price: $3.2M
EBITDA: $1.1M
Multiple: 2.9x
🔗 View the opportunity here: ecomswap.io/dashboard/buyer/…

When Barilla Group announced its acquisition of GOODLES in September, the price wasn’t disclosed. It has now been reported: $750M, all cash. The deal closed this week.
GOODLES launched five years ago and is now sold in most retailers, from Whole Foods to Walmart. Its estimated revenue over the last 12 months was $175M, with an estimated operating profit margin of around 20%. That puts the price at over 4x revenue, and it is Barilla’s first U.S. acquisition in more than three years.
Recent better-for-you pantry deals provide some context:
• Bachan’s sold to Marzetti at 4.6x revenue on $87M.
• Annie’s sold to General Mills at 4.0x on $204M.
• Primal Kitchen sold to Kraft Heinz at 4.0x on roughly $50M.
The median across six of these deals is 3.7x. GOODLES sits above that median.

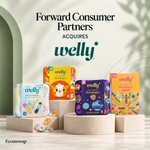
Forward Consumer Partners has agreed to acquire Welly, the first-aid and bandage brand, from Unilever. Financial terms weren’t disclosed.
Welly was founded in 2018 by Eric Ryan - the same entrepreneur who built OLLY and sold it to Unilever in 2019. Unilever acquired Welly two years later in 2021. Five years on, it’s leaving Unilever’s portfolio as the company continues its shift toward beauty and wellbeing brands under its current CEO.
Forward manages $925M in committed capital and has made eight investments since launching in 2023, including Kodiak, Justin’s and Bar Keeper’s Friend. Welly is its first move into consumer health.
Eric Ryan returns to the business as a strategic advisor and board member alongside the acquisition. A founder returning at the point of PE ownership preserves the brand knowledge and consumer connection that made the asset worth acquiring in the first place.
Unilever is actively reshaping its portfolio around beauty and wellbeing. Welly sits outside those priorities - and that created the opportunity for a buyer better positioned to focus on it.

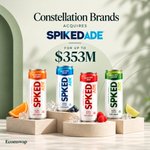
Constellation Brands has acquired SpikedAde, a spirit-based ready-to-drink beverage brand combining sports drink flavours with a vodka base, for $75M upfront with up to $278M in additional payments over five years tied to future performance.
SpikedAde built its initial footprint across the eastern U.S. as a first mover in the emerging “Ade” segment - zero sugar, 100 calories, non-carbonated. Spirit-based ready-to-drink beverage sales grew 25% in dollar terms in the 52 weeks ending August 2026. Constellation is betting that category growth continues and that its distribution network can accelerate what SpikedAde started.
The $75M upfront reflects Constellation’s caution on an early-stage brand in an unproven segment. The remaining $278M is contingent on performance over five years - meaningful upside for SpikedAde’s founder if the brand delivers under Constellation’s infrastructure, without Constellation committing to a price the business hasn’t yet earned.
SpikedAde will be fully integrated into Constellation’s Beer Division, with production, marketing and distribution all transferring to Constellation. The brand identity stays intact - the operational independence does not. For a brand at this stage, that structure makes sense. SpikedAde needed Constellation’s national distribution infrastructure to grow beyond its eastern U.S. footprint. The full consideration is only reached if the brand delivers the growth both sides are expecting.

New Deal | Skincare DTC Brand
Profitable direct-to-consumer skincare brand selling a PDRN-powered overnight hydrogel treatment mask, generating $3.0M in TTM net sales and $1.06M in EBITDA at a 35% margin. The hero mask drives 60% of sales and carries 1,300+ reviews.
Why this opportunity stands out:
• Customers who come back: 63% of customers are returning, supported by a 78K-subscriber email list and a subscription offer already in place.
• A near hands-off operation: ~10 owner hours a week, with a customer service VA, email VA and video editor all willing to stay on, and a 3-month founder transition with documented SOPs.
• Channels still to open: Amazon is yet to launch, Google Ads has been paused since early 2025 after prior spend of up to $52K a month, and SMS and win-back flows are not yet built.
Asking Price: $1.4M
TTM Net Profit: $1.06M
Multiple: 1.3x
🔗 Opportunity linked here: ecomswap.io/dashboard/buyer/…

New Deal | Supplement DTC Brand
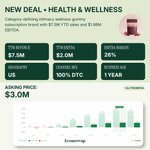
Single-SKU subscription brand in the intimacy wellness category, launched in January 2026 and scaled to $7.5M in net sales and $1.98M EBITDA (26.4% margin) in eight months. Sold exclusively through Shopify DTC, it is marketed around a fast-acting intimacy claim that no direct competitor is making.
Why this opportunity stands out:
• Recurring revenue from the start: $1.61M average subscription MRR, built on a default 4-week refill cycle.
• Proven customer response: a 4.8 out of 5 rating across roughly 56,800 reviews.
• Room to build on: a 275K-contact email list that is currently dormant, with Amazon, TikTok Shop, influencer marketing and UK/Australia localization all still untested.
Asking price: $3M
EBITDA: $1.98M
Multiple: 1.5x
🔗 Opportunity linked here: ecomswap.io/dashboard/buyer/…

Cerebelly, the science-backed children's nutrition brand, has acquired Fresh Bellies - Acquired by Cerebelly, a plant-based freeze-dried snack brand for kids. Financial terms weren't disclosed.
Both brands will continue operating independently - separate product lines, separate formulations, separate brand identities. What they share is ownership and back-end infrastructure. Cerebelly gains product development capabilities in snacking formats it didn't previously have. Fresh Bellies gains the supply chain and retail infrastructure to fulfill larger orders, more retailers and faster growth.
The CEO was direct on this point: "This is a platform play, not a consolidation."
Fresh Bellies was already in Target, Whole Foods and Walmart - the retail relationships were there. What it lacked was the operational infrastructure to scale reliably behind them - inventory, supply chain, certifications. The acquisition provides that infrastructure without altering the brand's identity or positioning.

New Deal | THC & CBD Supplement Brand
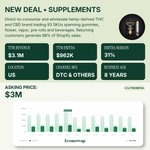
Trading since 2019 across 93 SKUs spanning gummies, flower, vapor, pre-rolls and beverages, this direct-to-consumer and wholesale brand runs on lean, in-house fulfilment out of a company-owned 3,000 sq ft warehouse. A wholesale channel built in the last year now supplies 400+ retail accounts, with expansion already underway into Texas.
Why this opportunity stands out:
• Loyalty built without a subscription: 88% of Shopify sales and 81% of orders come from returning customers, with no subscription programme ever built.
• Lean, owner-light operations: ~20 hours of combined owner involvement a week, with two full-time warehouse employees handling all pick, pack and ship in-house.
• Room to grow into a wider market: management expects a federal hemp framework by December 2026 that would open marketplaces, SMS, social and mainstream paid media to the category, with milligram caps seen as favouring this brand's existing low-dose range.
Asking price: $3M
EBITDA: $962K
Multiple: 3.1x
Link to more details: ecomswap.io/dashboard/buyer/…

New Deal | Electronics DTC Brand
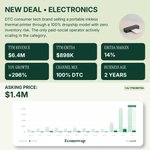
DTC consumer tech brand selling a portable inkless thermal printer through a 100% dropship model with zero inventory risk. The business runs on a high-volume Meta creative testing engine at a 1.8x blended MER, with a lean, fully outsourced contractor team handling everything from video to customer support.
Why this opportunity stands out:
• A near hands-off operation: Genuinely low owner time: the entire operation runs on ~2 founder hours a week, with a 10-person contractor bench covering video, ads, store management and support.
• Zero inventory risk: fulfilment runs 100% through a single dropship partner, no MOQs, no warehousing, automatic fulfilment on every order.
• Multiple acquisition channels still untouched: email has a built list that's never been sent to, and TikTok Shop, Google Ads and influencer/affiliate are all identified but unactivated, on top of an existing video library well suited to the format.
Asking price: $1.4M
EBITDA: $898K
Multiple: 1.5x
Link to more details: ecomswap.io/dashboard/buyer/…

Ecomswap retweeted

Went to @ecomswap's office today to discuss on brand exit and acquisitions with @ecom_jad .
Here are some key points you need to understand if you want to sell your Ecom brand for a premium multiple:
- Ads and scale are just one part of the game.
Most ecom bros are great marketers but terrible business owners. And you need to understand that brands are acquired for multiple reasons outside of just their scale.
Their products, their team, their systems & financials.
Just having a good scale doesn't guarantee good valuation.
- Retention affects your multiple more than you think.
Retention = Profit, Profit = Higher EBITDA, Higher EBITDA = Higher Multiple
- Don't black-hat your shit into 8 figure and expect high multiple. High change your shit wont even get acquired.
if you push extreme DR, lower chance that an investor will give you their money.
- Low risk = Higher Selling price.
Founder dependency, dependency on a single channel, compliance, team structure, SOP & Operating Mechanisms are some variables you need to fix before selling your brand.

New Deal: A leg health apparel brand with $18.7M TTM Revenue and $3.7M EBITDA has just landed on the Ecomswap deal floor.
The brand sells compression products to an underserved community that attests to the comfort and relief they provide. Net sales have grown 3.6x across the last two twelve-month periods.
A look at the numbers behind it:
• 72% gross margin, with EBITDA up 4x YoY and growing in every quarter since launch
• 300k+ email database, driving more than 25% of revenue organically
• 27% repeat purchase rate, trending above 30% in the most recent month
• A new product range introduced less than 12 months ago now drives 80% of product sales
• Streamlined remote team supported by agency partners and documented processes
The business offers multiple expansion paths, including launching on major marketplaces, entering new territories, developing adjacent product lines, and implementing subscription and retention strategies, none of which it currently pursues.
Asking price: $14.9M
EBITDA: $3.7M
Multiple: 4x
🔗 Opportunity linked here: lnkd.in/d3DGG5fC

New Deal: A chemical-free pest control brand doing $13.2M TTM revenue and $2.65M EBITDA has just landed on the Ecomswap deal floor.
Founded in 2024, the brand has grown its plug-in electronic pest repellers into a category leader in under two years, backed by +428% YoY growth.
A look at the numbers behind it:
• 80% gross margins with a founder-light operation, two founders at ~10 hours a week each on strategy
• A 150,000-subscriber Klaviyo list at a 52%+ open rate, plus 15,181 SMS subscribers
• A newly launched Amazon channel already estimated at $10k+/day
• 94.7% of revenue from the US, with Canada, the UK and the rest of world already contributing organically
• Full contractor and agency bench in place across creative, media buying, Amazon management and customer support, all willing to continue post-close
The business also offers multiple expansion paths, including new pest-control accessories building on the existing product line, Amazon and Walmart scale-up, retail and wholesale partnerships with hardware and home-goods chains, and underdeveloped paid channels across Google and TikTok Shop.
Asking Price: $11M
TTM EBITDA: $2.7m
Multiple: 4.1x
🔗 Opportunity linked here: ecomswap.io/dashboard/buyer/…

New Deal: Faith-based print-on-demand canvas wall art brand with $3.8M TTM sales and $947K EBITDA.
Built by a solo founder-operator over 1.5 years to +149% YoY growth, the brand runs a 100% print-on-demand model with zero inventory and no debt, selling exclusively through its own Shopify storefront.
A look at the numbers behind it:
• 73 original in-house designs, with the top 5 driving 58% of revenue and a long tail of 68 designs behind them
• A 77k-subscriber email list and 22.1k SMS list, backing a 4.5-star rating across 824 reviews
• 74% US revenue, with the remaining 26% already coming organically from the UK, Canada, Australia and Germany
• Fulfilment handled by a supplier network across six countries, with no stock-outs in eighteen months
• Lean cost structure: three contractor, no employees, no 3PL
The business also offers multiple expansion paths, including new formats and larger sizes on top of a catalog that's only sold vertical canvases to date, adjacent religious themes through the same supplier and audience, and diversifying paid acquisition beyond Meta into Google, TikTok, Pinterest and SEO.
Asking Price: $1.6M
TTM EBITDA: $947K
Multiple: 1.7x
🔗 Opportunity linked here: ecomswap.io/dashboard/buyer/…

New Deal: A practitioner-grade, transparency-led supplement brand doing $6.1M TTM revenue and $1.1M EBITDA has just landed on the Ecomswap deal floor.
Founded in 2017 and built on published Certificate of Analysis (COAs) rather than proprietary blends, the brand has made trust and transparency its moat in a category where most competitors lean on marketing claims instead.
A look at the numbers behind it:
• A 43-SKU catalog anchored by a cortisol-management hero product, alongside thyroid, hormone and gut health ranges
• ~$171k in subscription MRR with a 65-70% repeat purchase rate
• 19% EBITDA margin, with recent reinvestment into sales quality over volume
• A 38,800-contact Klaviyo list and a dormant ~8,000-contact SMS list ready to be reactivated
• Lean team structure (CEO, Ops Manager, Relationship Manager, Social Media Manager, Customer Support) supported by outsourced paid media, bookkeeping and 3PL
The business also offers multiple expansion paths, including two scoped product lines using existing manufacturers, a formalized wholesale channel across clinics, med-spas and gyms, and international expansion starting with Canada and Amazon's UK/EU marketplaces.
Asking Price: $5M
TTM EBITDA: $1.1M
Multiple: 4.4x
🔗 Opportunity linked here: lnkd.in/dD88EJQc

Ecomswap retweeted

Most founders understand how to build a business far better than they understand how to sell one and that gap matters.
An exit is one of the most consequential stages in the lifecycle of a business, and the moment when years of value creation are finally crystallized.
Looking forward to speaking at the @ooakbrands Mastermind in Tuscany alongside the some of the leaders shaping the DTC space.

Ecomswap retweeted

“You should exit when you don’t need to exit.”
Jad Kiwan (@ecom_jad), co-founder of @ecomswap (100+ ecommerce acquisitions), on when founders should actually sell:
“When you need to exit, your leverage flips to the buyer and you lose your edge.”
The best time to sell is when you’d be happy not to.

The biggest question in Ecom is should I be scaling 1 big brand vs a portfolio of multiple brands
Multiple brands = risk diversification
You can divest when needed, risk less in case the CPA goes up or anything on the acquisition side takes a hit.
1 brand = deeper brand equity
You can focus on going all in on the brand applying all your resources and time into it hence building a stronger asset.
The common denominator between scaling is building the right systems and teams.
Both of these strategies can be incredibly successful.
Which strategy do you think compounds the most in the long run?
New Deal: A sleep & wellness brand doing $23.2M TTM revenue and $1.8M EBITDA has just landed on the Ecomswap deal floor.
The business has scaled to more than $50M in cumulative sales in under 2.5 years, built around a premium wellness product sold through a sophisticated multi-channel acquisition engine spanning Meta, Google, YouTube, and Amazon.
What stands out operationally is the infrastructure behind the growth: • $200+ average order value • Recently launched Amazon channel already showing strong traction • 90-120 day supplier terms with established manufacturing relationships • Global team, dual 3PL setup, and proven acquisition systems already in place
The business also offers multiple expansion paths, including Amazon scale-up, retail and wholesale distribution, TikTok Shop, and broader international growth.
Asking Price: $7,000,000
TTM Net Profit: $1,818,000
x3.85 EBITDA Multiple
👇Reply ‘Bedding’ to access the opportunity.

New Deal: A category-leading AI-powered biohacking Mobile App business doing $11.8M TTM revenue has just been brought to market.
The App has built a subscriber base of more than 4.3 million users since launch and now generates $1.28M in monthly recurring revenue.
What stands out:
• $1.28M MRR
• 88% of revenue generated from subscription renewals
• #1 App Store ranking for "biohacking app"
• 4.04★ rating across 13,500+ App Store reviews
• Strong social following across platforms.
Upside:
• Email database of 4.3M never properly activated
• Organic content channels fully greenfield
• European markets untouched / US consolidation incomplete
Asking Price: $10,000,000
x0.8 Revenue
👇Reply ‘APP’ to receive access to the opportunity

We had two vetted buyers on the same deal last month.
Same CIM. Same diligence access. One offered on day three, clean number, deposit ready, no conditions. The other came back two days later with a higher offer and asked for another week to confirm internal capital allocation.
The seller took the first offer the same afternoon.
The second buyer's number was better. It did not matter.
A seller in a competitive process is not just reading your price. They are reading your certainty. A clean offer with conviction behind it beats a higher number with a question mark every time.
Proof of funds gets you into the deal. Committed capital, the kind where the internal conversation has already happened, is what wins it.
The week you spend confirming budget is the week someone else closes.
👇 If you are capital-ready and looking for EBITDA-positive e-commerce brands, view our live opportunities here: ecomswap.io/all-listing
