

Fintech & Web3 expert and author of https://nitter.gq/t.co/bQ8S3sMq7o championing financial inclusion.
New York
Joined June 2011
- Tweets1.7K
- Following801
- Followers749
- Likes364




Erick E. Pereda retweeted
💡 Banking's not where it's at! Discover why financial inclusion is THE mission of our time. 🌍💼 Ready to transform the future & redefine industry norms? Tap into the revolution! 🚀 Read the full scoop here: erickpereda.substack.com/p/t… #Fintech #Innovation #FinancialInclusion
Erick E. Pereda retweeted
Curious about why the future of banking isn't a bank? 🤔 Financial inclusion is the defining mission of our era! 🚀 Dive into the digital revolution changing the financial world. 👉 Click here to read more: substack.com/@erickpereda/no…
Erick E. Pereda retweeted
💡🚀 Ready for a money revolution? The future of banking isn't a bank! Dive into why financial inclusion is THE mission of our era. Curious? Read all about it 👉 nuel.ink/junAso 🌟💰 #BankingRevolution #FinancialInclusion

Erick E. Pereda retweeted
𝗙𝗿𝗼𝗺 𝗙𝗲𝗮𝘁𝘂𝗿𝗲 𝗙𝗮𝗰𝘁𝗼𝗿𝘆 𝘁𝗼 𝗔𝗴𝗲𝗻𝘁 𝗧𝗿𝗮𝗶𝗻𝗲𝗿: 𝗧𝗵𝗲 𝗟𝗲𝗮𝗱𝗲𝗿𝘀𝗵𝗶𝗽 𝗣𝗶𝘃𝗼𝘁
Inclusion is no longer just about giving someone an account number; it’s about enabling absolute financial agency.

Erick E. Pereda retweeted
Architecting the Global Economic Renaissance
The blueprint for a hyper-efficient, accountable financial future is live. By tokenizing assets and leveraging DLT, we can lower barriers for retail investors and move past the gatekeeper era.

𝗙𝗿𝗼𝗺 𝗙𝗲𝗮𝘁𝘂𝗿𝗲 𝗙𝗮𝗰𝘁𝗼𝗿𝘆 𝘁𝗼 𝗔𝗴𝗲𝗻𝘁 𝗧𝗿𝗮𝗶𝗻𝗲𝗿: 𝗧𝗵𝗲 𝗟𝗲𝗮𝗱𝗲𝗿𝘀𝗵𝗶𝗽 𝗣𝗶𝘃𝗼𝘁
Inclusion is no longer just about giving someone an account number; it’s about enabling absolute financial agency.
The market is moving at breakneck speed, with agentic AI projected to explode into a multi-billion dollar market by 2033. Discover why executive leaders are shifting from building features to training autonomous agents. nitter.gq/erickpereda/status/211…

𝗙𝗿𝗼𝗺 𝗙𝗲𝗮𝘁𝘂𝗿𝗲 𝗙𝗮𝗰𝘁𝗼𝗿𝘆 𝘁𝗼 𝗔𝗴𝗲𝗻𝘁 𝗧𝗿𝗮𝗶𝗻𝗲𝗿: 𝗧𝗵𝗲 𝗟𝗲𝗮𝗱𝗲𝗿𝘀𝗵𝗶𝗽 𝗣𝗶𝘃𝗼𝘁
Inclusion is no longer just about giving someone an account number; it’s about enabling absolute financial agency.
3
Erick E. Pereda retweeted
𝗧𝗵𝗲 𝗜𝗻𝗳𝗼𝗿𝗺𝗮𝘁𝗶𝗼𝗻 𝗔𝘀𝘆𝗺𝗺𝗲𝘁𝗿𝘆 𝗚𝗮𝗽: 𝗘𝗱𝘂𝗰𝗮𝘁𝗶𝗼𝗻 𝗮𝘀 𝗖𝗼𝗱𝗲
The "Poverty Tax" isn't just high fees—it's weaponized complexity.

Architecting the Global Economic Renaissance
The blueprint for a hyper-efficient, accountable financial future is live. By tokenizing assets and leveraging DLT, we can lower barriers for retail investors and move past the gatekeeper era.
It’s time to build a system that works for everyone. nitter.gq/erickpereda/status/211…
Architecting the Global Economic Renaissance
The blueprint for a hyper-efficient, accountable financial future is live. By tokenizing assets and leveraging DLT, we can lower barriers for retail investors and move past the gatekeeper era.
𝗧𝗵𝗲 𝗜𝗻𝗳𝗼𝗿𝗺𝗮𝘁𝗶𝗼𝗻 𝗔𝘀𝘆𝗺𝗺𝗲𝘁𝗿𝘆 𝗚𝗮𝗽: 𝗘𝗱𝘂𝗰𝗮𝘁𝗶𝗼𝗻 𝗮𝘀 𝗖𝗼𝗱𝗲
The "Poverty Tax" isn't just high fees—it's weaponized complexity.
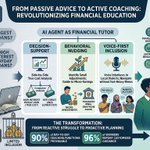
In our latest piece for Ledger Impact, we explore how 'Fintech 2.0' replaces static financial literacy with personalized 'Education as Code.' AI agents are turning passive financial guidance into active contextual coaching, dismantling the gates built by legacy systems. nitter.gq/erickpereda/stat…
𝗧𝗵𝗲 𝗜𝗻𝗳𝗼𝗿𝗺𝗮𝘁𝗶𝗼𝗻 𝗔𝘀𝘆𝗺𝗺𝗲𝘁𝗿𝘆 𝗚𝗮𝗽: 𝗘𝗱𝘂𝗰𝗮𝘁𝗶𝗼𝗻 𝗮𝘀 𝗖𝗼𝗱𝗲
The "Poverty Tax" isn't just high fees—it's weaponized complexity.
4
Erick E. Pereda retweeted
𝗩𝗶𝗿𝘁𝘂𝗮𝗹 𝗖𝗼𝗹𝗹𝗲𝗰𝘁𝗶𝘃𝗲𝘀: 𝗔𝘂𝘁𝗼𝗺𝗮𝘁𝗶𝗻𝗴 𝘁𝗵𝗲 𝗟𝗲𝗻𝗱𝗶𝗻𝗴 𝗖𝗶𝗿𝗰𝗹𝗲
What happens when you combine community lending circles with autonomous AI agents? You get 'Virtual Credit Collectives'—a new model for automated, community-led financial governance.

𝗩𝗶𝗿𝘁𝘂𝗮𝗹 𝗖𝗼𝗹𝗹𝗲𝗰𝘁𝗶𝘃𝗲𝘀: 𝗔𝘂𝘁𝗼𝗺𝗮𝘁𝗶𝗻𝗴 𝘁𝗵𝗲 𝗟𝗲𝗻𝗱𝗶𝗻𝗴 𝗖𝗶𝗿𝗰𝗹𝗲
What happens when you combine community lending circles with autonomous AI agents? You get 'Virtual Credit Collectives'—a new model for automated, community-led financial governance.
𝗧𝗵𝗲 '𝗜𝗻𝘃𝗶𝘀𝗶𝗯𝗹𝗲 𝗕𝗿𝗶𝗱𝗴𝗲' 𝘁𝗼 𝗛𝗶𝗴𝗵-𝗚𝗿𝗼𝘄𝘁𝗵 𝗘𝗾𝘂𝗮𝗹𝗶𝘁𝘆
For too long, traditional finance viewed financial inclusion as charity, allowing monopoly-like models to thrive. They were wrong.

The efficiency of this model is best illustrated through the "Invisible Bridge." My research shows that by 2030, underbanked families will interact with their finances through natural language interfaces.
ledgerimpact.com/

1
Erick E. Pereda retweeted
𝗧𝗵𝗲 '𝗜𝗻𝘃𝗶𝘀𝗶𝗯𝗹𝗲 𝗕𝗿𝗶𝗱𝗴𝗲' 𝘁𝗼 𝗛𝗶𝗴𝗵-𝗚𝗿𝗼𝘄𝘁𝗵 𝗘𝗾𝘂𝗮𝗹𝗶𝘁𝘆
For too long, traditional finance viewed financial inclusion as charity, allowing monopoly-like models to thrive. They were wrong.
Erick E. Pereda retweeted
The future of finance won’t be built on ledgers alone. From shared ledgers to intelligent agents, a major architectural shift is redefining how value, trust, and coordination work across banking and fintech.

Erick E. Pereda retweeted
For years, the phrase "regulatory barrier" was a death knell for fintech startups. Scaling a global financial product meant drowning in fragmented national red tape, necessitating armies of compliance officers and infinite administrative bandwidth.
But that landscape is rapidly shifting. We are entering the era of "Regulation as Code."
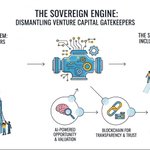
Instead of viewing compliance as external friction, the new generation of fintechs—part of what we call the "Sovereign Engine"—is embedding governance directly into their core architecture. By utilizing AI to automate KYC, transaction monitoring, and risk management, startups are transforming compliance from a costly administrative burden into a sustainable competitive advantage.
The evidence of this shift is global. In Europe, innovators are leveraging frameworks like the EU AI Act to build "trust-by-design" infrastructure. Meanwhile, in emerging markets, startups like NayaPay in Pakistan and Xepelin in Latin America are bypassing legacy banking systems entirely, using mobile sovereignty to bring high-quality financial tools to millions who were previously excluded.
This shift is critical. As we transition from "walled garden" banking to an open, inclusive financial utility, the cost of regulatory compliance is plummeting. This isn't just about operational efficiency; it is about democratization. When you lower the barrier to entry for the builder, you dramatically expand the reach of the service for the user.
We aren’t just automating finance; we are engineering social mobility. The foundation of the 2030 financial landscape is being written in code today.
#Fintech #Innovation #RegulationAsCode #SovereignEngine #AI #FinancialInclusion #FutureOfFinance

ALT https://www.ledgerimpact.com/
Ledger Impact argues that prioritizing the 'credit invisible'—those ignored by centralized bureaus—is actually a massive, high-growth frontier.
1
2
By leveraging ZK-Proofs and tokenized Real-World Assets (RWAs), we build the 'Invisible Bridge' to global equality and a fairer economy. Join the collective achievement by building a system that serves everyone.
ledgerimpact.com/ nitter.gq/erickpereda/status/211…
𝗧𝗵𝗲 '𝗜𝗻𝘃𝗶𝘀𝗶𝗯𝗹𝗲 𝗕𝗿𝗶𝗱𝗴𝗲' 𝘁𝗼 𝗛𝗶𝗴𝗵-𝗚𝗿𝗼𝘄𝘁𝗵 𝗘𝗾𝘂𝗮𝗹𝗶𝘁𝘆
For too long, traditional finance viewed financial inclusion as charity, allowing monopoly-like models to thrive. They were wrong.
3