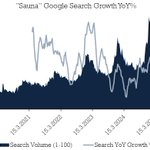
$HARVIA Based on "sauna" search data, growth was over 30% YoY on all weeks of Q4 in US. Despite tariff concerns and currency headwinds topline should be coming in strong. Japan even stronger and Europe showing return to growth.
2
8
1,287
My two key observations from $CSU.TO earnings
1. Last time we saw this high org. growth (5%) was Q42023 (Where is AI disruption of legacy SaaS??)
2. The incremental margins are insane; on Q2 with revenue growing 376M expenses grew 191M those are ~50% incremental EBITDA margins
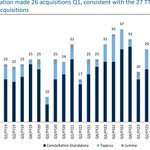
Larger ish M&A for $CSU.TO:
Volaris acquires Useall Software, a provider of enterprise management software to the electric utility sector, manufacturing, and distributors in Brazil.
+200 employees
+1000 clients
+50,000 users
Let's say avg. ARPU $500 this would be $25M rev
Extremely interesting insights from ex Head of M&A at $CSU.TO (Vencora, part of Volaris operating group)
...AI, competition, churn, organic growth, multiples paid, bonus structures, disruption risk, investment modelling and many more... 🔥🔥👀
Tune in, more below
1/x
$HARVIA is reporting on Thurs., let's look at their core growth driver US. Historically "Sauna" search volumes have been a nice indicator.
25Q1: search up 26%
25Q2: up 17%
YTD: up 22%
Takeaway Q2 looks slower. Last Q of Thermasol M&A contribution so total US growth ~40%.
1/2
So $HARVIA did not let us down Q1. As expected US showing very high growth in the middle of tariff turmoil...
-> US grew ~59%
-> Total Revenue ~23%
-> Operating profit ~23% of rev.
-> ROCE ~48%
-> cash conversion ~74%
Likely seeing more M&A in next 1 - 2 years...
What gives me confidence on continued US G% for $HARVIA?
Search volume for Sauna products has historically predicted growth decently. The delta will eventually become larger as consumers search for more specific products rather than "Sauna"
Q1 so far 29% search volume growth🔥
1
7
965
RBC latest updates on $CSU.TO
Topicus been leading deployment but CSU standing strong
$CSU.TO with new one in Brazil 🇧🇷; Nydus specializes in HR Management Systems & Payroll tailored to SME. 79 employees
Nydus serves construction, transportation, healthcare, business services and retail.
Nydus Systems Informatica Acquired by Volaris Group - Volaris Group
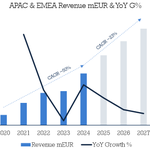
Another key $HARVIA market APAC & EMEA (mostly Japan & China) showing nice growth. I'm projecting +30% (25) -> 15% (27)
Here AOV likely 2x higher than Europe and margins also better with local China manufacturing plant ramping up.
The Sauna Boom-Japan: saunafromfinland.com/sauna-a…
1
7
966
What gives me confidence on continued US G% for $HARVIA?
Search volume for Sauna products has historically predicted growth decently. The delta will eventually become larger as consumers search for more specific products rather than "Sauna"
Q1 so far 29% search volume growth🔥
US/World is getting BLOATED and you get this for 19x PE, 15x EV/EBIT $NVO. ROTC % at 46% and guidance ~20% sales growth with operating profit growth of 20 - 25%, will be highly value accretive. How does this go wrong from these levels? From latest IR presentation below:
16
2,320
Favorite Finnish name $Harvia outlook strong. You get +30% ROIC business with projected 15 - 20% growth for EV/EBIT ~20x FY25.
World's leading sauna/spa company benefitting of the long tailwinds of wellness and continues to consolidate industry (M&A). Their US Biz below:
1/2
Former Senior Financial Analyst Vela $CSU.TO on EU VMS TAM:
"European market is still huge, we're not in year one, but I think that there's still a lot of room for us, like Eastern Europe and Balkan"
"I think it's thousands, from being honest, but I think that there's...
1/x
Now that $TOI.V has been more active in Poland decided to have a look at one of their deals they did a couple years ago in Poland (Simple Sa). They acquired the company 2021 and have transformed the company to mid teens EBITDA % margins with double digit growth %. ops wizards 🧙♂️
2
20
1,018
This is a bread and butter deal for them, 1mEUR EBITDA and HSD growth % Rev. CSU playbook is to keep the growth running but focus on profitability.
With average 3y growth and cash conversion (FCF) if we believe in better margin a 3year payback is not too optimistic
@CJ0pp3l
2/2
2
467