

Institutional Markets & Trading | Client Relationships | Business Development | Capital Markets | Market Commentary | Views my own, not financial advice.
Cape Town, South Africa
Joined October 2010
- Tweets650
- Following1.4K
- Followers603
- Likes575





#SouthAfrica #Manufacturing
SA manufacturing output declined 3.5% y/y in September, worse than the 2.0% contraction expected, but improving from August’s revised 4.1% decline. The largest drags came from motor vehicles (-15.0%), wood and paper products (-11.2%), furniture (-19.0%) and metals and machinery (-3.7%).
1
105
$BID #JSE Bidcorp Capital Markets Update – Four Months to October 2026
• Group revenue +2.4% in constant currency, but -4.3% in rand terms, reflecting adverse currency translation. Trading profit +8.2% in constant currency and +1.6% in rand terms.
• HEPS increased approximately 10.0% in constant currency and 3.2% in rand terms.
• Gross profit margin improved to approximately 25.0% from 24.0%. Cost of doing business increased to 19.1% of net revenue from 18.5%, while pre-IFRS 16 EBITDA margin improved to 6.6% from 6.1%.
• Europe revenue +2.0% and trading profit +6.0% in constant currency. UK revenue +3.0%, with trading profit growth exceeding 10.0%.
• Emerging Markets revenue was flat, while trading profit increased 14.0% in constant currency. South Africa maintained momentum, while Australasia recorded improvements in trading performance.
• Five bolt-on acquisitions completed since June 2026. A further 681,000 shares repurchased for R292m since July.
• Outlook: Early November trading in line with expectations. Food inflation expected to emerge over the coming months, while adverse rand translation effects are projected to moderate if current exchange rates persist. Consumer spending, energy costs and geopolitical uncertainty remain risks.
Trading update unaudited.
3
191
$JSE #Top40
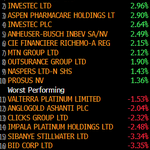
The Top40 closed 0.33% lower as losses across precious metals producers and diversified miners outweighed gains in banks and selected industrial heavyweights. Vodacom (+7.15%) and Investec Ltd (+2.96%) led gains, while Harmony (−5.26%) and Pan African Resources (−4.54%) were the biggest decliners. Naspers and Prosus advanced despite Tencent’s 0.14% decline in Hong Kong. Retailers were mixed, while Sasol remained under pressure.
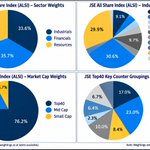
South Africa’s unemployment rate rose to 33.7% in Q3. Corporate announcements included H1 FY2027 results from Stor-Age Property REIT, Vodacom and Premier Group. Vodacom is seeking partners to develop AI data centres across Africa, while Absa expects to complete its African banking expansion within two years. MSCI’s November review is due on 11 November, with preliminary analysis suggesting a potential move of Clicks to small cap and possible inclusion of Aspen in the MSCI SA Index; neither change is confirmed.
Global equities were mixed, with Japanese and Hong Kong markets advancing while European markets diverged. US shares declined after stronger-than-expected inflation reinforced expectations of further Federal Reserve tightening, lifting Treasury yields and the dollar. Oil fell after Trump signalled restraint over further strikes against Iran. Gold, silver, platinum and Bitcoin declined, while technology shares faced continued concerns over AI valuations and infrastructure spending. China reported a sharp increase in exports and imports.
Elsewhere in Africa, Dangote Refinery’s IPO attracted $4.1bn in share bids. Nigeria also proposed reforms to facilitate cross-border bond trading across West Africa and broaden funding for infrastructure.
Roughly R27bn traded on the day, with the rand at R16.48/$ at the close.

$SSS #JSE Stor-Age Property REIT H1 FY2027 Results
• Property revenue +1.3% to R707.9m. Distributable earnings +10.4% to R318.6m, with distributable income per share +4.0% to 69.04c.
• HEPS +8.6% to 64.00c; EPS +26.3% to 136.12c. Interim dividend +4.0% to 62.14c/share, reflecting a 90% payout ratio.
• SA rental income +9.5% and net property operating income +9.3%. UK rental income +0.9% and net property operating income +1.7%.
• Closing owned portfolio occupancy was 89.3% (SA 91.4%; UK 81.5%). JV occupancy increased by 8,200m² YoY.
• SA REIT loan-to-value ratio 27.3%, with SA REIT NAV/share +4.7% to R18.12.
• Completed acquisitions in Ballito and Vredenburg totalling R105.5m. A further R95m acquisition in KwaZulu-Natal is expected to transfer in December 2026.
• Expansion: Agreed to acquire ten Xtraspace properties for R387m, subject to competition authority approval, with R38m in planned improvements and management contracts for six additional properties. Development projects progressing in SA and the UK.
• Dividend: 62.14c/share, ex-dividend 25 November, payable 30 November 2026.
$VOD #JSE Vodacom Group H1 FY2027 Results
• Revenue +25.6% to R102.5bn, reflecting the consolidation of Safaricom from Q2. Service revenue +29.4% to R85.1bn (+13.3% pro forma).
• EBITDA +40.0% to R42.7bn (+18.0% pro forma), with the reported EBITDA margin increasing to 41.6% from 37.3%.
• HEPS +25.7% to 587c. Interim dividend +7.6% to 355c/share.
• Financial services revenue +99.0% to R15.9bn (+19.2% pro forma), with financial services customers increasing 15.0% to 108m.
• Egypt service revenue +36.3% and EBITDA +31.3% in local currency. Safaricom service revenue +13.1% and EBITDA +27.5%.
• Operating free cash flow +68.2% to R16.9bn, while free cash flow declined 62.0% to R1.03bn. Net debt/EBITDA increased to 1.6x from 0.9x.
• Outlook: Medium-term early-teens EBITDA growth outlook reaffirmed, with performance tracking ahead of target. Safaricom consolidation remains subject to an ongoing Kenyan court appeal.
$PMR #JSE Premier Group H1 FY2027 Results
• Revenue +38.8% to R14.3bn, primarily reflecting the inclusion of RFG (Culinary). EBITDA +51.4% to R2.0bn, with the EBITDA margin improving 120bps to 13.9%.
• Operating profit +52.5% to R1.7bn. EPS +27.5% and HEPS +27.1%, both to 711.1c.
• Millbake revenue +1.3% to R9.4bn; EBITDA +23.7% to R1.6bn, with margins improving 300bps to 16.8%.
• Groceries revenue reached R4.9bn, with EBITDA of R513m and a 10.4% margin, including the acquired Culinary business.
• Operating cash generation +43.0% to R1.8bn. Net debt R2.3bn, leverage 0.7x and ROIC improved to 20.6%. Share repurchases totalled R207m.
• Outlook: Further RFG integration synergies expected in H2, with benefits from newly commissioned bakeries. Grain prices expected to remain deflationary through FY2027, with inflationary pressure anticipated thereafter. Cash generation to support capex, debt reduction and potential further buybacks.
$JSE #Top40
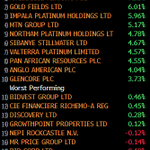
The Top40 closed 2.27% higher in a broad-based advance led by gold and platinum producers, with further support from diversified miners, banks and selected retailers. AngloGold Ashanti (+7.35%) and Gold Fields (+6.01%) led gains, while Sasol (−8.13%) and British American Tobacco (−1.88%) were the biggest decliners. Naspers and Prosus advanced despite Tencent’s 0.33% fall in Hong Kong.
Corporate announcements included MTN’s quarterly update for the period ended 30 September 2026, Omnia’s unaudited results for the six months ended 30 September 2026 and Raubex’s interim results for the six months ended 31 August 2026.
Global equities rebounded from last week’s technology-led selloff, with US, European and Japanese markets advancing. Renewed US-Iran diplomacy weighed on oil, with WTI falling 3.60% to $87.56/bbl. The dollar weakened, US Treasury yields eased and precious metals advanced across the board. Bitcoin slipped to $74,574.
Roughly R22bn traded on the day, with the rand at R16.42/$ at the close.

$JSE #Top40
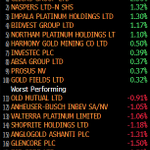
The Top40 closed 0.49% lower, with gains in gold producers and selected retailers offset by weakness across banks, diversified miners, Naspers and Prosus. AngloGold Ashanti (+4.95%) and Gold Fields (+3.91%) led gains, while Clicks (−4.14%) and British American Tobacco (−3.55%) were the biggest decliners. Investors also assessed stronger-than-forecast US job creation and indications that the ANC was heading for its weakest electoral performance yet in South Africa’s municipal elections.
Corporate announcements included Sappi’s Q4 and FY2026 results, Shoprite’s operational update for the four months to October 2026 and The Foschini Group’s H1 FY2027 results.
Global equities were mixed, with US technology shares rebounding while European and Asian markets declined. US payrolls rose by 165,000 in October, exceeding all forecasts, while unemployment fell to 4.1%. WTI was broadly flat at $90.58/bbl, the dollar strengthened and Treasury yields rose. Gold and palladium declined, while silver and platinum advanced. Bitcoin slipped 0.77% to $75,386.
Elsewhere in Africa, MTN Rwanda reported nine-month profit growth of 130.3% and EBITDA growth of 29.1%. Mauritius-listed Emtel reported profit growth of 29.9% and revenue growth of 8.8%.
Roughly R29bn traded on the day, with the rand at R16.55/$ at the close.

$SAP #JSE Sappi Q4 and FY2026 Results
• FY2026 revenue -3% to US$5.28bn; adjusted EBITDA -41% to US$294m. Net loss widened to US$747m from US$177m, including US$405m in special items and a US$269m negative forestry fair value adjustment.
• FY2026 headline loss increased to US69c/share from US15c. Adjusted EPS declined to a loss of US21c from earnings of US8c.
• Q4 revenue -5% to US$1.32bn; adjusted EBITDA -11% to US$99m. Quarterly net loss narrowed to US$116m from US$194m.
• Net debt +7% to US$2.05bn; FY2026 capital expenditure US$210m, below US$240m guidance. Available liquidity US$707m.
• DWP market prices reached US$920/ton at quarter-end. Approximately 38kt of DWP sales were delayed by Durban port congestion.
• European graphic papers JV with UPM remains under regulatory review, with a decision expected in early January 2027.
• Outlook: Q1 FY2027 adjusted EBITDA expected below Q4 FY2026, with planned maintenance expected to impact earnings by approximately US$41m. FY2027 capex estimated at US$240m.
$TFG #JSE The Foschini Group H1 FY2027 Results
• Group revenue +0.1% to R31.4bn; sales -0.4% to R29.0bn (+1.4% constant currency). Operating profit -6.5% to R2.1bn.
• HEPS -6.8% to 272.8c; EPS -9.8% to 262.4c. Interim dividend -6.9% to 121c/share.
• TFG Africa sales +3.8%, operating profit +2.7%. Online sales +53.3%, now contributing 10.9% of African sales.
• TFG London sales -2.2% in GBP; Australia -4.4% in AUD. Segment operating profits declined 32.5% and 28.5% in rand, respectively.
• Operating cash generation +20% to R3.7bn; pre-IFRS 16 net debt reduced by R0.9bn to R9.1bn.
• Group closed 178 stores and opened 71, reducing its footprint to 4,807 stores.
• Outlook: TFG Africa sales -0.7% for the five weeks to 31 October; Australia -5.3% in AUD. UK trading affected by a cyber incident at Phase Eight, Hobbs and Whistles. Consumer spending expected to remain constrained.
$SHP #JSE Shoprite Holdings Operational Update – Four Months to October 2026
• Group sales from continuing operations +6.4% YoY. Supermarkets RSA +7.1%, Non-RSA +7.0% in rand (+4.3% constant currency) and Other segments -1.5%.
• RSA internal selling price inflation was 0.7%. For July–September, RSA sales growth exceeded the rest of the market by 5.3 percentage points, according to NielsenIQ.
• Checkers Sixty60 sales +33.4%, supporting growth in Checkers and Checkers Hyper.
• Group opened a net 71 stores, including 61 in Supermarkets RSA.
• Pharmacy sales +17.6%, comprising Medirite and Medirite Plus +9.7% and Transpharm +21.3%.
• Other segments sales -1.5%, partly reflecting 51 OK Franchise store closures following a franchise agreement termination. OK Franchise trading profit growth remained positive.
• Sale of the SA Furniture division remains subject to Competition Tribunal approval. FY2027 interim sales update planned ahead of the interim results expected at the end of February 2027.
Operational update unaudited.
$JSE #Top40
The Top40 closed 3.99% higher in a broad-based rally, with buying in the MSCI South Africa ETF during yesterday’s JSE closure likely contributing to catch-up demand. The Democrats’ US midterm sweep raised expectations of closer scrutiny of AI spending and rotation into emerging markets, while early DA gains and weaker ANC support in municipal elections supported local sentiment and the rand.
Naspers (+10.36%) and Prosus (+8.04%) led gains, while Sasol (−4.27%) and Reinet (−2.44%) were the biggest decliners. Tencent gained more than 5% in Hong Kong following its Hy4 AI model launch, analyst upgrades and broader strength in Chinese technology shares. The advance came despite reports that US pressure had prompted Oracle to cancel a $7bn AI chip deal with Tencent.
Corporate announcements included Q3 2026 operating updates from Sibanye-Stillwater and Gold Fields, AngloGold Ashanti’s Q3 2026 results, Truworths’ FY2027 business update, PPC’s H1 FY2027 trading statement and Optasia’s 9M2026 trading update. Nedbank completed its acquisition of a 66% stake in NCBA, while Aspen completed its Ovestin divestment. Investec secured a European banking licence from the European Central Bank and Central Bank of Ireland.
Global equities weakened, led by a sharp selloff in US technology shares, while European markets were mixed. The Bank of England raised rates to 4%, while US jobless claims fell to 189,000. WTI rose to $89.71/bbl, the dollar edged higher and US Treasury yields declined. Gold, platinum and palladium advanced, while silver slipped.
Roughly R40bn traded on the day, with the rand at R16.44/$ at the close.

23
875
$ANG #JSE AngloGold Ashanti Q3 2026 Results
• EBITDA +12% YoY to US$1.57bn; attributable profit +18% to US$787m. HEPS increased to US155c from US132c.
• Gold production -9% YoY to 696koz; average realised gold price increased to US$4,239/oz from US$3,490/oz.
• Total cash costs rose to US$1,534/oz from US$1,225/oz; AISC increased to US$2,170/oz from US$1,720/oz.
• Free cash flow declined to US$722m from US$920m, reflecting higher taxes, capital expenditure and lower gold sales. YTD free cash flow reached US$2.62bn.
• Net cash increased to US$1.26bn. Q3 dividend declared at US71c/share (US$361m), bringing YTD dividends to US259c/share.
• FY2026 production guidance reaffirmed at 2.80–3.17Moz. North Bullfrog execution funding approved, subject to permits.
$SSW #JSE Sibanye-Stillwater Q3 2026 Operating Update
• Group adjusted EBITDA +9% YoY to R10.8bn, supported by higher commodity prices.
• SA PGM production 439.8koz (4E), +8% QoQ; AISC R26,598/4Eoz. SA gold production 155.4koz, broadly flat QoQ; AISC R1,668,973/kg.
• US PGM production -19% YoY to 59.4koz (2E), impacted by industrial action. AISC +39% to US$1,617/2Eoz.
• Century zinc production 25kt; adjusted EBITDA more than doubled to US$57m. Recycling adjusted EBITDA +54% to US$40m.
• FY2026 guidance unchanged except US PGMs: Production revised to 245–255koz (previously 280–300koz). AISC revised to US$1,700–1,760/2Eoz, or US$1,510–1,570/2Eoz including Section 45X credits.
6
207
$TRU #JSE Truworths FY2027 Business Update
First 17 weeks ended 25 October 2026:
• Group retail sales -4.3% to R6.5bn, reflecting weaker consumer spending, reduced promotional activity and rand strength.
• Truworths Africa sales -2.7% to R4.1bn. Account sales -0.2%, cash sales -8.6% and online sales +16.9%.
• Office UK sales +0.3% to £106.8m, but -6.9% in rand terms. Online sales -6.0% in sterling.
• Group account sales broadly unchanged, representing 46% of sales. Cash sales -7.5%.
• Africa gross profit maintained in rand terms; Office UK gross profit +approximately 2% in sterling.
• Outlook: November and December trading will be critical to H1 performance. Interim results expected around 25 February 2027.
2
132

$NED #JSE Nedbank Completes 66% NCBA Acquisition
• Final acceptances: 1.316bn shares (79.88%), before scaling and allocation.
• Issued 43.63m new Nedbank shares, increasing shares in issue to 520.90m.
• Cash consideration: KES 23.23bn (R2.93bn).
• NCBA remains listed on the Nairobi Securities Exchange.
5
155
$APN #JSE Aspen Completes Ovestin Divestment
• Aspen has completed the sale of Ovestin commercialisation rights and related intellectual property in Europe to Ennogen Healthcare International.
• Transaction consideration of €197m, plus the cost of related inventory.
• Ennogen's funding condition has been satisfied, with Aspen confirming receipt of the €197m purchase consideration on 3 November 2026.
• The transaction is now complete.
7
147
$PPC #JSE PPC H1 FY2027 Trading Statement
For the six months ended 30 September 2026:
• EPS and HEPS expected to increase 20%–38% to 30.00c–34.50c, from 25c.
• Pro forma EPS and HEPS expected to increase 17%–35% to 35.00c–40.50c, from an adjusted 30c.
• Pro forma figures exclude the after-tax impact of realised and unrealised foreign exchange losses on contracts hedging US dollar exposure for the RK3 cement plant construction.
• Earnings improvement reflects continued progress under PPC's ‘Awaken the Giant’ turnaround.
• Interim results expected on or about 16 November 2026.
Financial information has not been externally reviewed.
5
130
$GFI #JSE Gold Fields Q3 2026 Operational Update
• Attributable gold-equivalent production -3% YoY to 605koz, down from 634koz in Q2.
• AISC +26% YoY to US$1,965/oz; AIC +23% to US$2,266/oz, reflecting higher royalties, currencies and input costs.
• Salares Norte produced 136koz at AISC of US$437/oz. South Deep +5%, Tarkwa +4%, St Ives +4% and Gruyere +6% QoQ.
• Net debt increased to US$981m from US$437m in Q2 2026, following dividend payments and share buybacks. Net debt/adjusted EBITDA at 0.13x.
• Additional shareholder returns totalled US$1.11bn, comprising US$854m in share buybacks and a US$253m special dividend.
• Windfall received environmental approval. Tarkwa mining lease renewals remain uncertain.
• FY2026 guidance maintained: Production expected towards the upper end of 2.4–2.6Moz; AISC US$1,800–2,000/oz and AIC US$2,075–2,300/oz.
7
148