
Public equities/options, card product @mercury. Eternal superalloy cubes @ https://nitter.gq/t.co/fz34u7r194.
North America
Joined April 2014
- Tweets2.2K
- Following500
- Followers1.7K
- Likes22.8K





Well, apparently Belen Garijo has the cajones and more, betting more than a third the $SNY EV on $INSM…

(2/4) IMO comes down to whether $SNY's brand-new CEO Belen Garijo/board have the balls to actually bet most of remaining BS on $ABVX.
Though presumably Belen brought in with mandate to make moves given the dupi cliff (see next tweet).

474


Sadly in mobile doesn’t look like the quoted tweet shows if I add photos + tag a ticker, so re-sharing the tweet from @Rayanbiotech here:
3
577
Fantastic thread. Have to say, $ABVX has been the most painful stock I’ve ever held in max size. A real test of conviction. We’ll see what happens!

My outlook on $ABVX - What is there to say that hasn't been said? Whatever, here I go anyway...
In the $83s right now I think it has to be one of the worst mispricings (and thus, hopefully, best opportunities) I have ever seen in biotech. Honestly, given the post P3 status of this asset...I would probably be pretty comfortable calling it "the" worst mispricing I've seen.
The stock's performance this year has *easily* been the most frustrating disappointment I've experienced in >10 years of doing this. The stock is down almost 40% YTD, and its underperformance versus the $XBI this year is nearly -70%.
What makes this price action so particularly infuriating is how incredibly positive their updates throughout the year have been.
I would've guessed that $ABVX languishing in the $80s would have been the result of a mixed UC maintenance readout, perhaps with a CR delta around 20% or below...The reality was *twice* that (~40%) - tying the best clinical remission data *ever* shown (by multi-black box warning drug Rinvoq). And on top of that we got an even bigger blue sky surprise with truly unheard of, unprecedented endoscopic remission rates...
...Then, on top of that, a few months later an unrelated trial reads out at UEGW that once and for all confirms that the endpoint GI docs should be treating to is...Endoscopic remission! The exact endpoint where the runner up to $ABVX isn't even visible in the rear view mirror...On their recent call, $ABVX management called this a "perfect storm". I agree. Not only did they present ER data so positive that nobody had even *modelled* for it as a *possibility*, but then just a few months later, that very endpoint becomes *THE* key endpoint for the disease...incredible!


Wow. A scam/spam bot impersonating @AirCanada tracked down my email and emailed me. See spam comments in the replies too. Stay safe out there.


@AirCanada truly the worst customer experience of all airlines. Flight to NYC yesterday cancelled due to FAA ground stop, have waited on phone for TWO hours THREE TIMES and @AirCanada HANGS UP on me at the two hour mark.
On top of this, even regular call wait times are ALWAYS 1 hr+. Get your shit together @AirCanada. Hire more staff.
1
6
643


Must read transcript from $ABVX mgmt at Gugg. Super bullish in mgmt's own words:
-VERDICT->STRIDE-III updated guidelines->implications for obe given best-in-class endoscopic remission
-KOL at UEG saying this should be used in 1L in addition to 2L+
-200 advisory KOLs who agree safety is completely fine, better than others with higher freq of AEs like herpes zoster/infections
-For combo, want oral that matches safety, ie no testing, no monitoring required
-NDA by end of year, being reviewed/edited by former senior FDA gastro officials
-Going for one ph3 CD trial vs two


Just read the fire late draft of a paper my wife is about to arXiv and am seriously considering not mentioning minor grammatical errors I find so as to make it even more clearly not-LLM generated 🤔
1
2
692
John Mason retweeted

Top-notch communication from both today. My assumptions:
1) Ex-FDA GI division reviewers writing/reviewing NDA content. NDA submission in Nov.
2) Looking at Oral combo only. Their own oral α4β7 or IL-23 combo with Obe may be announced in Jan with some cheap Chinese partner. This move makes Gilead, Lilly and J&J oral pipeline and combination redundant. They need to act fast.
3) CD- Can see blinded data from blinded arms. Can see arm 1 (placebo) bad, arm 2 slightly better (12.5 mg) and arm 3 (25 mg) and 4 (50 mg) exceedingly doing well compared to 1 and 2. Not much difference in 2 and 3. That gives confidence in CD.
4) Final CD induction enrollment announcement in Dec. March last 12 week visit. April - May data.
4) They are reading BioX.
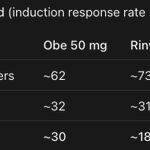
I appreciate @ldbioinv's skepticism re: $ABVX, it's been helpful pushback re: induction. But I think the below table summarizes the core argument for obe's future as the best drug in UC:
You can argue about obe's lower/wider induction CR range. But at the end of the day, on obe you have almost a 1 in 3 chance of getting to endoscopic remission. On Rinvoq/Tremfya you have a 1 in 5 chance.
With the VERDICT treat to target trial showing data pointing towards endoscopic remission as THE endpoint now, it's just a matter of that difference (plus Tremfya-equiv safety) sinking in for GI docs that see obe's data.


This was really good

In honor of some “pods blowing up” and me being traveling I will outline some concepts about pod risk management about which I do know a thing or two, as my name might suggest.
It is a common perception that pods are factor beta neutral and thus largely hedged. That is not quite true. A truer statement is that they are factor beta neutral to the extent they can measure the exposures.
Most equity risk models are derivatives of the original axioma and barra factor models. There are now many things that go into this but at their core they are a 12 (IIRC) variable linear regression. And mathematically, the unexplained remainder, the error term, is assumed to be the alpha (Upon which the team gets paid). You well recognize most of these factors: size, momentum (short and long), quality, dividend, domicile, sector, etc.
Now even the dull among you may note that there are in fact many other things that go into a stock. That’s true and that’s one reason why many people at the pods are very rich. There is though a very active and live debate to the highest level of these firms as what you “want” in the other bucket. On the one extreme, scheduling a proprietary drone flyover on the Aurora AV truck up fitting facility to measure parking lot activity vs expected timeline….that feels like pretty good alpha. On the other extreme, going long the Canadian listing rather than the U.S. listing because the Canadian listing diversifies the domicile score so you get a higher portfolio level idio score…..that doesn’t feel like great alpha. But the range is wide: paying GS a billion dollars so your team is the first meeting at the conference? That’s kind of the pod scale advantage. Albeit less so if every other pod is in the room. Going balls long large cap domestic U.S. GLP-1 manufacturers vs non GLP-1? Well that kind of is thematic alpha (depending on the work put in by analyst), but even if you’re of the opinion fuck it, let the kids rip (a reasonable view) you also know at the levered portfolio level that we aren’t measuring that risk completely. This line can really be illustrated with the concept of a “custom factor”. Maybe going long a shit load of SPACs is alpha, maybe it isn’t, but how the FUCK are you gonna build a portfolio level SPAC factor exposure loading in late 2021 when spacs didn’t functionally exist until 2021????
Anyways, interesting & active philosophical debate but there are some downstream derivatives.
Firstly, as a well known matter, 6 sigma events happen in finance all the time. There’s one every year in some corner of the market. So ex ante we know our models aren’t “great”.
Second, everyone knows the agent is an unobserved blind spot. It’s impossible to actually “know” why the analyst and PM are doing anything. You like to think they’re doing it on the back of deep fundamental quality work, but the median analyst and PM isn’t good at their job. So that assumption is known to be unreliable. The capital allocation solution to this is momentum chasing at the portfolio level: you allocate more to winning pods and you cut the losers fast. This is a brilliant approach because it means the pod business model is capital light- they identify and scale the good teams without actually having to invest in knowing which pods have “good” process. It’s worth really appreciating that point because it’s one of the true genius aspects of the model, and at its core it’s why the GPs are so fucking rich. (Deep finance readers will note that some of the original papers on factors saw that one of the earliest possible explanations for the decade-long trend nature for factor performance is implicit fund flow pressure from the momentum chasing nature of capital at the LP level)
(Continued in reply)
511
Could not agree with this more.
But I’ll add: the true value is in the searching. Have to wade through those mediocre opportunities to both find, recognize, and build conviction in the great ones.

The longer I invest the more I realize you get 1-2 great opportunities every few years. The rest of the time is spent wondering if you will ever get another great opportunity again and convincing yourself to own mediocre opportunities while you wait. Mediocrity is the price you pay for impatience.
microcapclub.com/active-pati…
2
642