Gonna reload buyback another 1B 1st of Jan... Leverage below 3.75x, guess they take another stab at it into YE... Equity investors are a bunch of pussies. Jared rides rockets into space. No maturities until '32. 馃敤馃敤馃敤馃殌馃殌馃殌
You think mngmt does a bit of self-reflection when they lower guidance and drop this line "this performance is not without room for criticism"... But then they blame it on macro factors: Travel disruptions, currency fluctuation, inflation! Kinda Trump'ish being honest馃槵
After taking a yuuuge loss by (somewhat) trusting Walgreens' former CFO (at $FIS), I'm plowing into $Adyen, where Klarnas' new CFO will soon be wielding his influence. Ride or die.馃ぁ馃殫 馃殌
Getting hard to justify $CSU.TO > $FIS ... Sure, culture and all that, but FIS sells the stickiest shit & has LT contracts, is (much) cheaper, has more torque (cheap leverage!) & ~organic growth ~the same
$GPN amending bylaws, I'm no lawyer and Gemini thinks it's nothing. My initial thought was co. wants to limit risk of litigation (in response to takeover?). What say the masses? Usual corporate hygiene or something else?
Intelligence has never been cheaper and more abundant, and yet people seem as dumb as ever. I understand people don't like the democratic candidates, but the blatant grift is wild. Clectocratic family looting the Country like a banana republic.
$IPCO earnings+conference call was A+. Everything that matters look good (Blackrod). "Early results indicating encouraging subsurface performance" > expansion most likely starting in '28. Massive (and scarce) asset. Wonder if they see it through or someone comes for it.
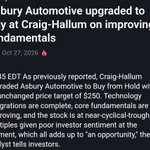
"The current environment strongly favors allocating capital toward share repurchases and as such we have secured Board authorization for an additional $1 billion in share repurchases" $AN up pre-market, $GPI and $ABG up biggly since the lows... These things shouldn't trade ~7x
Stock down 10% as co. scraps midterm margin guidance. I'd be interested if I could gain comfort in mngmt, but having a CFO as CEO - and doing a 180 on acquisitions without much explanation - doesn't give me comfort. Also- hiring a new CFO from Klarna is just a massive red flag.
$GPI reported, their death was exaggerated... "In the U.S. we grew same-store customer pay revenue and repair orders 3% and 4% YOY"... UK turnaround progressing well... Sold stores worth ~325m to reduce debt post acquisition of Hennessy...
Analysts and investors freaked out about comments re P&S last Q, as customer affordability gets squeezed.. But $GPI and $ABG results show there's plenty of work to go around... Warranty work is episodic, but LT trajectory seems up & to the right... Tight mkt given lack of techs