



Long-term overhaul
Overallocated, I consolidated on the price dip. (This is 70%)
$NBIS - 30%
$MU - 20%
$LITE - 20%
High Conviction (Each around 5%)
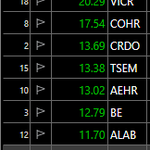
$NTSK, $RDDT, $CRDO, $APP, $ALAB, $AAOI
Killed the third bucket
nitter.gq/mmonis/status/21075027…


The best opportunity is in tech: AI, optics, and memory.
Don't let other folks fool you into believing otherwise.
The funny part is that these tickers don't know where their declining MAs are. They run and run hard nonetheless.
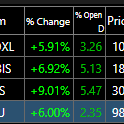
$NBIS - 23% in 3 days; if you are waiting for MA's, whose fault is it
Many examples: $AAOI, $MU, $LITE etc


A shoe company sends two sales folks to a remote place where people do not wear shoes
A classic business parable. The company gets two very different telegrams back:
Salesperson 1: “No opportunity. Nobody here wears shoes.”
Salesperson 2: “Huge opportunity. Nobody here wears shoes!”
The story usually highlights the difference between a fixed/pessimistic mindset and an opportunistic one—same data, opposite conclusions.
I believe in the latter mindset. When the market is moving down, I believe it creates an imbalance between a company's value and its stock price.
I trust that company growth, profitability, margins, income, and FCF tell a better story than most far-out predictions.


Major Market Movers, Wed Oct 28
Market
Fed day: The FOMC decision is at 2:00 PM ET, with Warsh’s press conference to follow; the expected outcome is a hawkish hold that sets up a December hike.
Oil risk premium building: UBS lifts its year-end Brent forecast to $110, the US warns ships to avoid the Strait of Hormuz, and WSJ reports Gulf allies were told to prepare for a short, intense Iran campaign after the midterms.
September goods trade deficit widened to $134.9B (est. $130.2B) on a 7.5% jump in capital-goods imports; mortgage applications rose 3.4% as the 30-year rate eased to 7.41%.
KOSPI jumped ~6% overnight on memory-chip strength; in the US, the equal-weight S&P is beating the cap-weighted index by 4 points in October as leadership broadens beyond AI.
Stock Movers
$AVGO - CEO Hock Tan personally rescued the $63B Anthropic chip financing (~1.7GW of XPU compute, deliveries from 2027); also seen benefiting as OpenAI moves to buy Google TPUs
$MU - SK Hynix says memory shortages last through 2030, with 2027 DRAM demand growing 20%+ and over half of 2027–28 capacity locked under long-term deals
$NVDA - Oracle expands Vera Rubin superclusters to multi-gigawatt scale and puts Vera CPUs into production for OpenAI’s agent workloads
$CBRS - Cerebras and Oracle partner to bring Cerebras inference to Oracle Cloud in 2027; stock rose 9%
$META - Upsized $25B share sale priced at $625 drew ~5x demand
$AMZN - FCC approves the Globalstar acquisition, bringing Amazon Leo into satellite-to-phone service
$CEG - Secures a conditional DOE loan commitment of up to $5B to expand nuclear output
$VRT - Q3 crush (revenue $4.3B vs $3.76B est., organic orders +100%), FY26 guide raised; up ~16% premarket
$HOOD - Down ~7% after Q3 revenue and EPS came in light and crypto revenue fell 55% YoY
Earnings Reported
$STX - Earnings beat:
Revenue $4.2B vs $4.14B est., adj. EPS $7.68 vs $7.42; Q2 guide $4.8B revenue / $9.20 EPS, both well above consensus
LTM Revenue: $13,767M, NTM Revenue: $20,768M, Revenue growth %: 50.9%
EV: $153,540M, EV/NTM Revenue: 7.4x, Adj: 0.15
$GEV - Earnings beat: revenue $12.6B vs $11.99B est.; orders $29.3B (+96% organic), backlog $197B; FY26 revenue guide raised to $46.5–47.5B
LTM Revenue: $43,999M, NTM Revenue: $51,289M, Revenue growth %: 16.6%
EV: $228,064M, EV/NTM Revenue: 4.4x, Adj: 0.27
$SKHY - Earnings beat on revenue and operating profit: revenue $78.9B vs $74.8B est., operating profit $62.8B vs $58.5B (80% margin), net profit miss; ~$75B in 2026 shareholder returns
LTM Revenue: n/a, NTM Revenue: $338,466M, Revenue growth %: n/a
EV: $1,010,569M, EV/NTM Revenue: 3.0x, Adj: n/a
Earnings Today After Market
$GOOG - Alphabet
$NOW - ServiceNow
$MSFT - Microsoft
$KLAC - KLA
$FTNT - Fortinet
$VKTX - Viking Therapeutics


$CLS :
Checks on FCF, EPS Growth and PEG is 0.21
Why PEG?
A P/E on its own can’t tell a cheap stock from a slow-growing one. A 15x P/E is expensive for a company growing earnings 5% a year and cheap for one growing 70%.
PEG divides the P/E by the growth rate, which turns the question into “what am I paying per point of earnings growth?”
It’s the earnings-side twin of Adj, which does the same thing with EV/Sales and revenue growth.
The usual benchmark is 1.0, from Peter Lynch’s rule of thumb that a fairly priced company’s P/E roughly equals its growth rate:
- Below 1: you’re paying less than one turn of P/E per point of growth, conventionally “cheap for its growth.”
- Around 1: fairly priced on that heuristic.
- Above 1: paying up. For context, mega-cap quality names often trade at 1.5–2.5+ on consensus.

